
Did Raised Outlook Just Shift Exponent (EXPO) Stock's Investment Narrative?
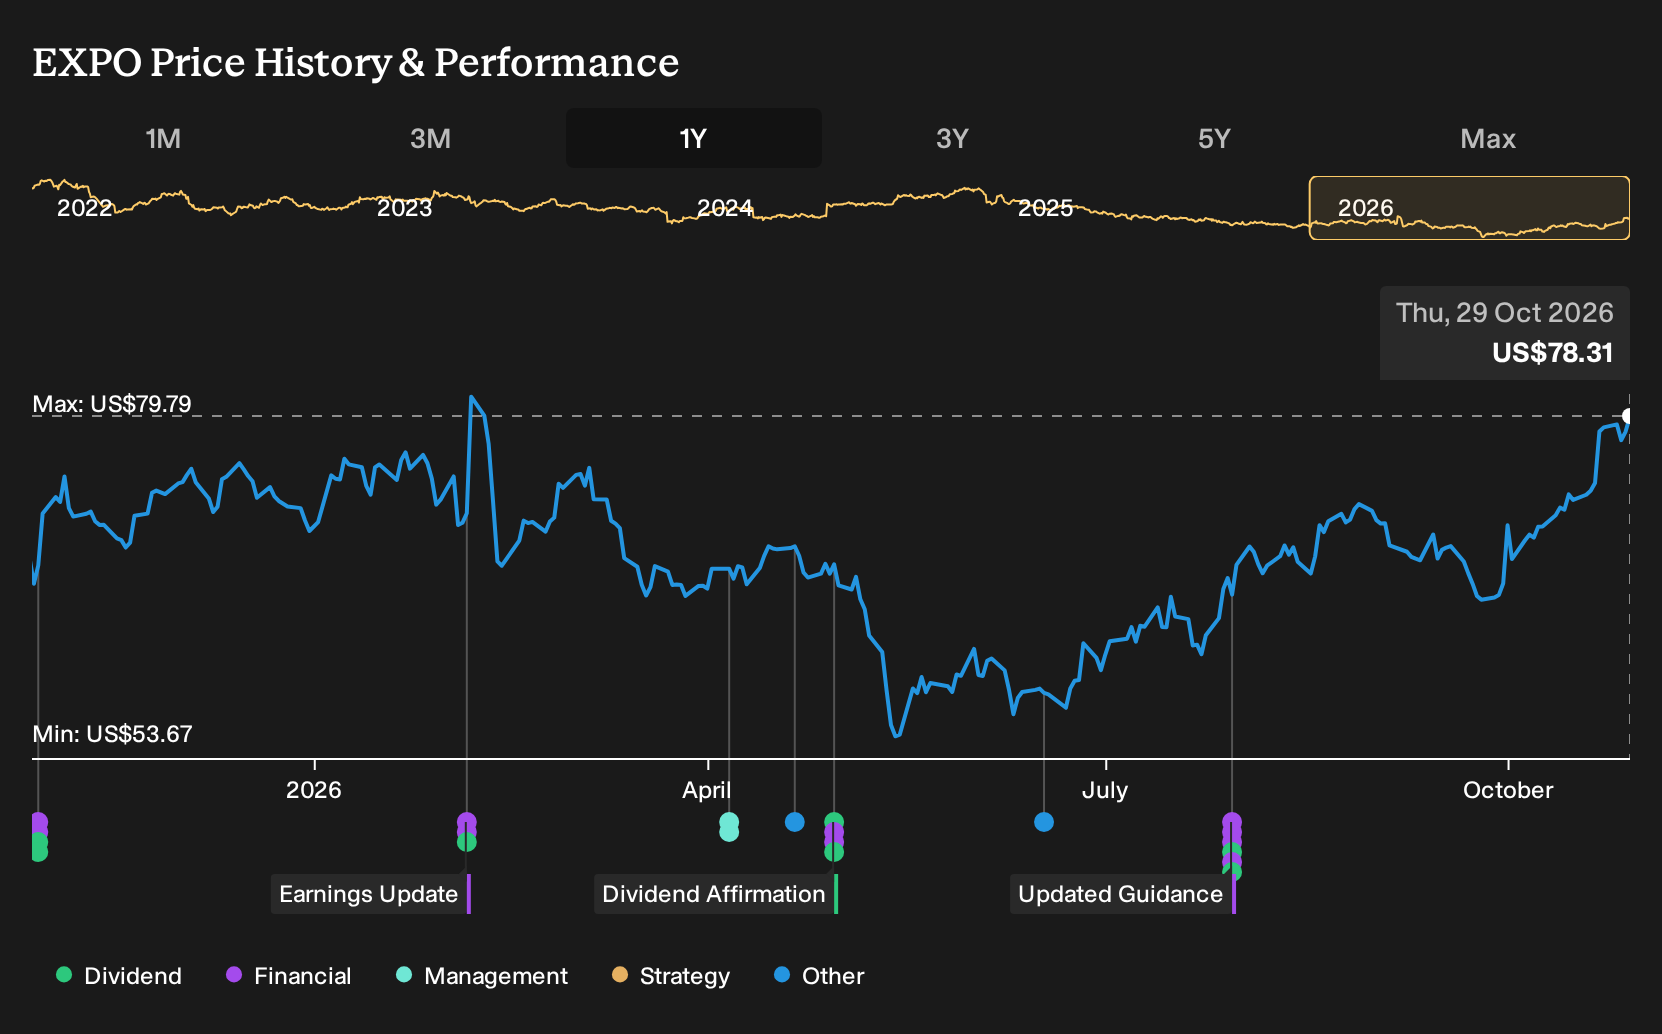
- Exponent reported Q3 2026 and nine-month results with higher revenue, net income and EPS from continuing operations, plus a US$0.31 quarterly dividend declared for payment in December 2026.
- AI related consulting has become a meaningful contributor to Exponent's activity in 2026, with management indicating that a mid-teens percentage of business is tied to AI oriented work, alongside a raised full year outlook.
- Attention now turns to how Exponent's upgraded full year guidance could reshape the investment narrative, which had already focused on complex consulting demand.
Exponent Investment Narrative Recap
To own Exponent, you need to believe this consulting specialist can keep converting complex engineering, regulatory and AI heavy problems into steady project demand without letting expenses eat into profitability. The fresh Q3 print, with higher revenue, net income and EPS versus last year, keeps that thesis intact. The near term swing factor is whether AI related mandates and infrastructure work keep utilization high as the year closes.
The biggest risk still sits in margin pressure. Management has previously flagged sensitivity to items like lease renewals, travel and stock based pay. Even with raised full year guidance, any renewed cost creep or client pushback on premium pricing, especially as AI tools mature, could cap the benefit of today’s stronger top line.
The Q3 2026 earnings release is the key update tying this together. Exponent reported US$173.73 million of revenue for the quarter and US$511.65 million for the first nine months, alongside US$30.94 million of quarterly net income. EPS from continuing operations reached US$0.64 for Q3 and US$1.83 diluted for the nine month period.
Those figures, plus management’s higher full year outlook, relate directly to the current catalysts investors are watching. AI related consulting, now in the mid teens of 2026 business by management’s estimate, is already embedded in reported numbers rather than just a slide deck promise. The task from here is execution, keeping billable hours and pricing power strong while managing operating costs that have previously pressured EBITDA margins.
Analysts see Exponent reaching US$753.5 million of revenue and US$146.0 million of earnings by 2029, which corresponds to a forecast 9.9% yearly revenue growth rate and implies an earnings increase of about 31% from US$111.8 million today.
Discover how Exponent's fair value indicates a 7% potential upside to its current price before the market closes the discount.
Exploring Other Perspectives
One alternate view focuses on AI related consulting as a bigger swing factor than the baseline narrative suggests. The most optimistic analysts were already modeling Exponent to reach about US$847.3 million of revenue and US$154.6 million of earnings by 2029. That is a stronger path than consensus, and this fresh Q3 news could nudge those projections in either direction once models are updated. It therefore makes sense for you to compare several narratives rather than rely on a single storyline.
Explore 3 other Exponent fair value estimates, including one that suggests as much as 58% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Exponent research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Exponent. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Exponent's overall financial health at a glance.
Looking For More Ideas Beyond Exponent?
If Exponent has sharpened your interest in specialist businesses with clear earnings stories, it can help to line it up against a wider watchlist. The Simply Wall St Screener gives you a way to scan for stocks that match specific traits so you are not relying on a single case study.
- For investors who want potential upside without compromising on financial quality, consider running a screen using the 30 high quality undervalued stocks based on solid fundamentals.
- If income is a key part of your plan, you could focus on companies with stronger yield support through the 7 dividend fortresses that target higher payout levels.
- When capital preservation matters most, you might prioritise sturdier balance sheets and more resilient profiles through a curated 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com