
Smucker (SJM) Stock Stays Above Fair Value On Uncrustables News
J. M. Smucker shares have logged a strong year to date gain, which naturally raises the question of whether the current price still lines up with what the business earns. With the stock now trading around recent highs, the key issue is how that move stacks up against the company's underlying earnings power.
- The stock is up 30.7% year to date, which puts more weight on the question of whether recent earnings can support the higher valuation investors are paying today.
- Uncrustables crossing US$1b in sales and expanding into a refrigerated format may support expectations for steadier revenue and profit contributions from that brand over time. This in turn feeds directly into how much investors are prepared to pay for each dollar of earnings.
- The analysts covering J. M. Smucker have run their own numbers. See what analysts think J. M. Smucker's shares could be worth.
The issue now is whether J. M. Smucker's current share price is adequately supported by its earnings when viewed through this lens.
If you want to see how J. M. Smucker's earnings story compares with other quality focused opportunities, line it up against companies in the 30 high quality undervalued stocks.
Has J. M. Smucker Run Too Far on Earnings?
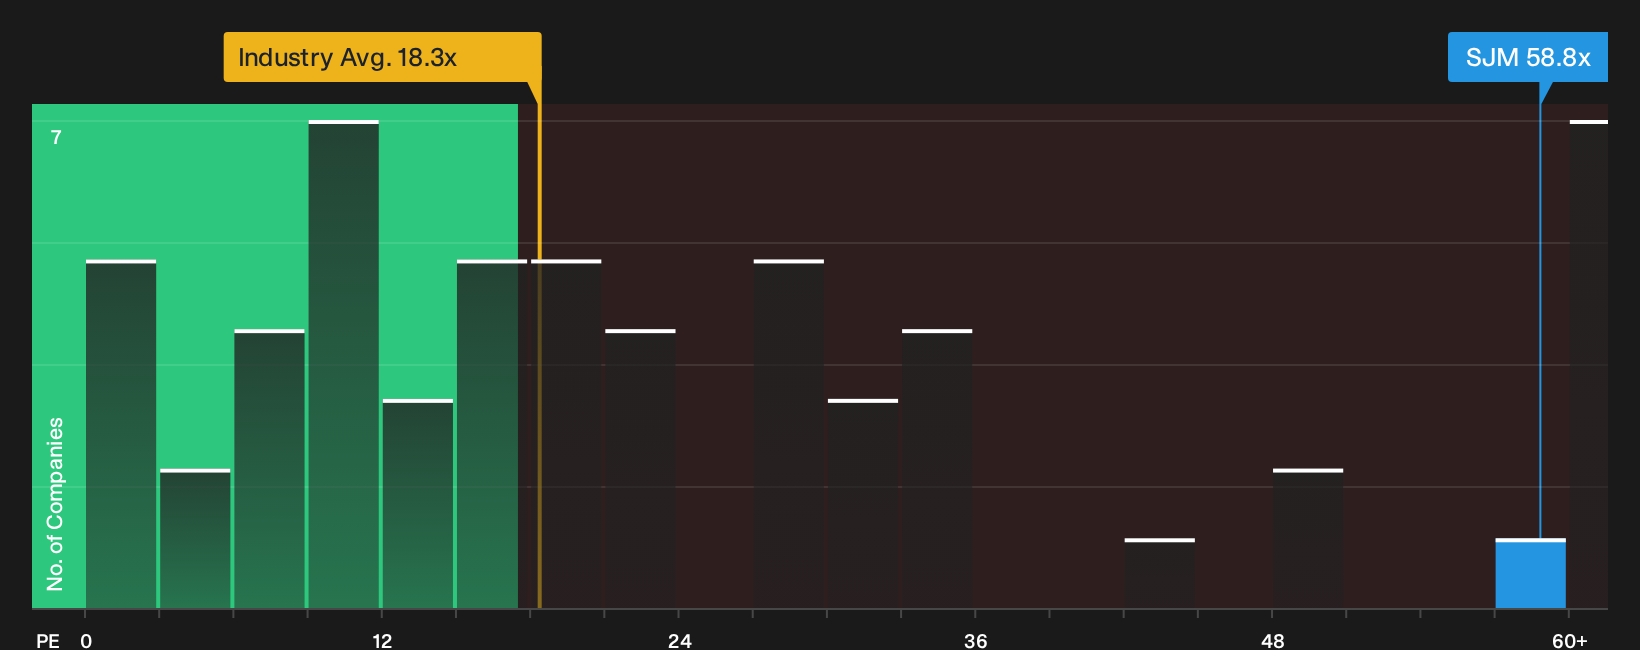
The P/E ratio fits J. M. Smucker because earnings sit at the center of how investors usually judge a mature branded food business. On this yardstick, the stock trades on a P/E of 58.8x, which is far above the food industry average of 18.3x and also stands well above peers at 22.0x. That signals investors are currently willing to pay a much higher price for each dollar of J. M. Smucker earnings than they are for comparable companies.
Because the company specific fair P/E, which reflects its own mix of growth potential, profitability and risk, sits meaningfully below the current 58.8x level, the shares screen as overvalued on this framework. The market is clearly factoring in a strong outlook for J. M. Smucker, and because Uncrustables has crossed US$1b in sales and now stretches into a refrigerated format, recent product momentum may be helping support that richer multiple in investors' minds. For anyone assessing whether to engage with the stock at this valuation, the key question is whether that premium P/E is justified by the future earnings the business can actually deliver in the years ahead. Explore the numbers behind J. M. Smucker's P/E valuation.
The J. M. Smucker Narrative: What Would Justify Today's Price?
Narratives for J. M. Smucker pick up where this valuation puzzle leaves off. They spell out which paths for revenue growth, profitability and earnings would need to play out for the stock to be worth materially more or less than it is today, and they sit on Simply Wall St's Community page. Where a single ratio offers one neat figure, those scenarios unpack the future that number relies on so you can watch whether reality lines up with it.
Community views on J. M. Smucker split between one camp that sees more upside in the brand portfolio and another that thinks much of that promise is already reflected.
Bull case: 11% undervalued
"The main factor that has to go right is that J. M. Smucker converts momentum in core growth brands and ongoing cost discipline into sustained free cash flow around the current US$1.1 billion level while it continues to deleverage and manage the Hostess turnaround..."
Discover why this Narrative puts J. M. Smucker at 11% undervalued.
Bear case: roughly fairly valued
"Growth in at home coffee consumption and the expansion of Cafe Bustelo into new roast profiles and younger demographics support higher branded volume over time. However, the pass through nature of coffee pricing and recent tariffs can limit sustained margin expansion and keep segment profit growth dependent on disciplined cost control and pricing execution..."
Explore why this Narrative puts J. M. Smucker at roughly fairly valued.
One more J. M. Smucker check that belongs beside the headline valuation story
Price multiples and growth narratives only tell part of the J. M. Smucker story, because internal checks have also flagged specific risk signals that deserve your attention before you weigh the stock further. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com