
Missed Generac's Rally? Here's What Holders Bought Into
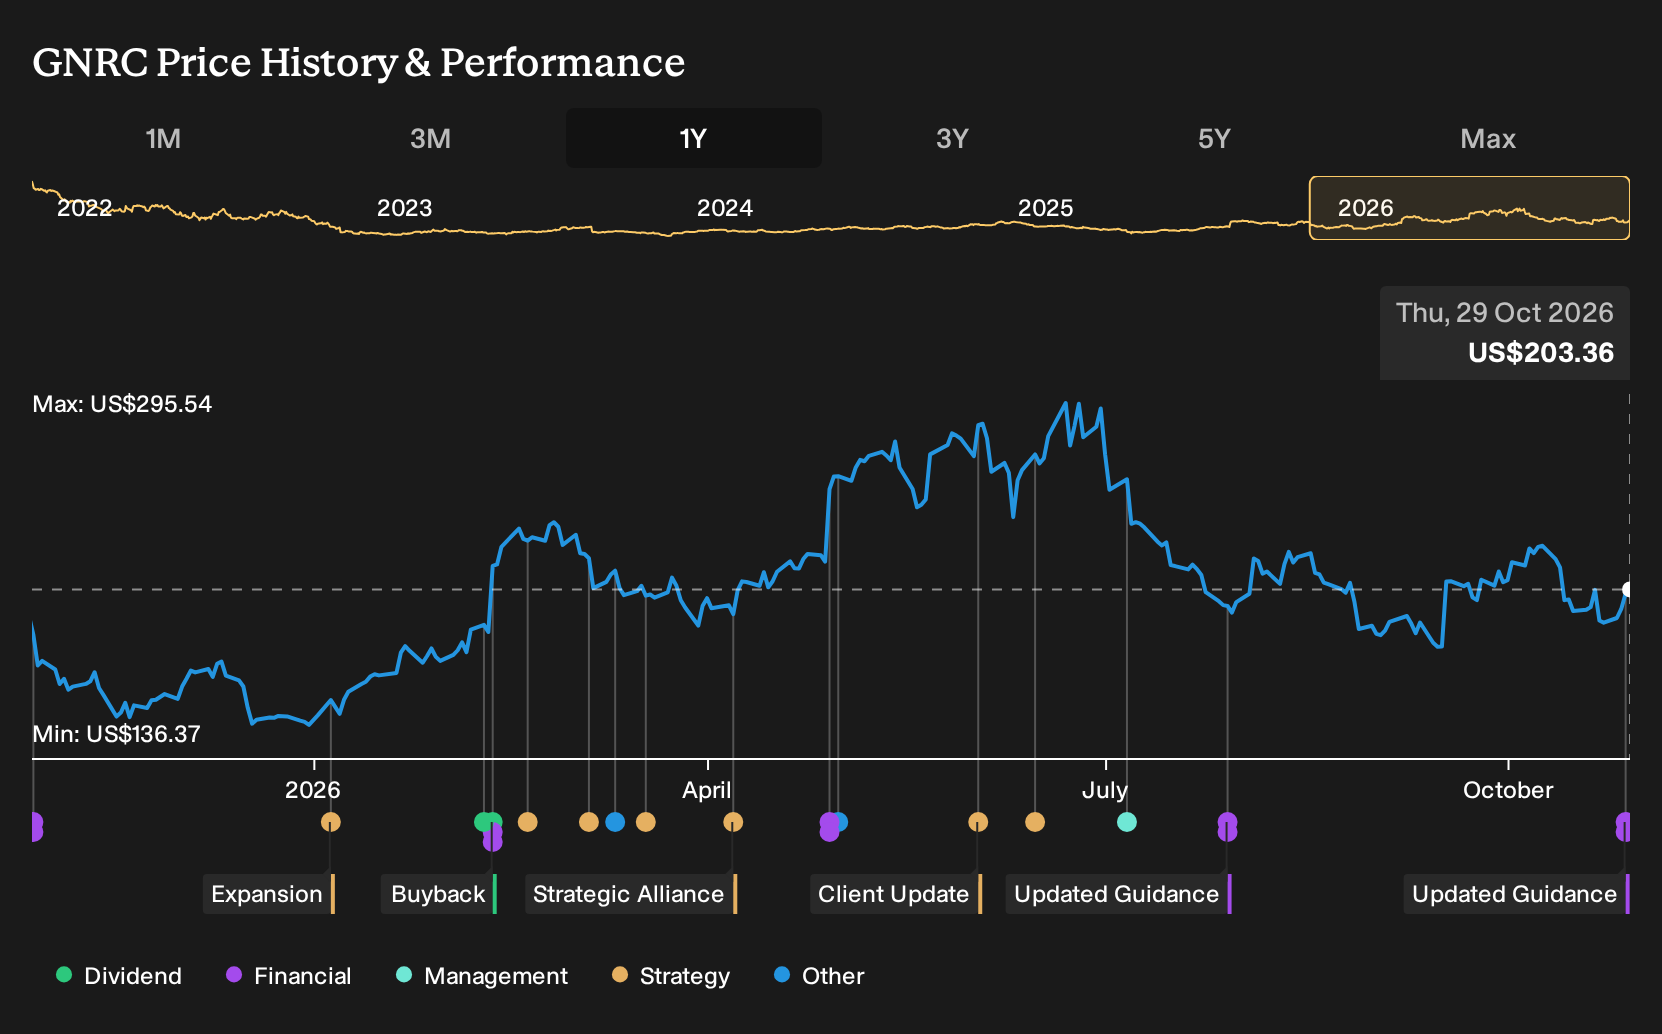
Generac has had a busy year, from deepening its role in data center backup projects to drawing mixed headlines about valuation and insider selling. Investors who held Generac over the past year are up 22.7%, including dividends. If you were deciding on 29 October 2025 whether to buy, hold, or avoid the stock, how much weight would you have put on early data center contracts versus concerns that grid modernization could slowly erode generator demand?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Generac is not the only name tied to this theme. Zero in on 43 power grid technology and infrastructure stocks and compare how each one is priced.
The Argument Generac Investors Were Actually Having
The shares cost US$181 at the start of the period, and anyone looking at Generac then had to choose between two sharply different stories about where the business might head next.
The bullish Narrative put Fair Value at US$207, 14% above the start price, built on assumed revenue growth of 7.4% a year and profit margins rising to 10.8%, with future earnings supported by data center backup demand and grid vulnerability.
The bearish Narrative set Fair Value at US$138, 24% below the start price, focused on grid modernization reducing conventional generator demand and the risk that regulatory pressure on diesel products would weigh on Generac’s core revenue streams.
What The Facts Did To The Generac Thesis
The biggest new fact for Generac was the long term data center backlog, including a US$2.4b Amazon contract and Q3 2026 net sales of US$1.29b. That tilt clearly backed the optimistic data center story. At the same time, critics pointing to valuation and insider selling did not get an answer on grid erosion, only that net margin moved from 5.9% to 8.4%. Overall, the evidence cut both ways.
For a different stock, treat any big-contract narrative the same way. Track whether signed backlog and reported margins actually line up with the growth and profitability assumptions baked into each side of the debate.
What Generac's Current Price Already Assumes
Generac now trades at US$203 after a 22.7% gain over the past year, and this selected Narrative argues that its Fair Value sits above that level.
The thesis focuses on data center scale, higher margin potential, and recurring revenue. A buyer today would need confidence that large megawatt capacity is used at the levels management is planning for.
"The main factor is Generac Holdings scaling its expanded large megawatt and residential platforms efficiently enough to support higher margins and recurring revenue from data center, telecom, rental, and connected home customers. The current valuation implies the market is not fully pricing in the narrative that Generac Holdings is undervalued relative to its long term growth and earnings potential."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Which Company Could Surprise You Next?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 43% below our estimate - targets merchants in developing economies shifting more payment flows onto platform tools.
- Company 2 - 36% below our estimate - expands capacity for high horsepower engines used in power and large data projects.
- Company 3 - 38% below our estimate - builds manufacturing and supply capacity centered on higher margin film and installation work.
Three companies from the same screener. Open the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com