
How Investors May Respond To Onto Innovation (ONTO) AI Memory Expansion Role
- Onto Innovation has been pulled into the spotlight after SK Hynix highlighted a prolonged AI memory shortage and credited the company’s defect prevention and metrology systems on high bandwidth memory lines as essential to planned capacity additions.
- The recognition from a major memory producer underscores how Onto Innovation’s tools sit directly in the path of expanding AI oriented memory and packaging projects, tying its day to day tool shipments to concrete build outs rather than abstract AI optimism.
- We will now look at how Onto Innovation’s investment narrative could be affected by SK Hynix spotlighting its high bandwidth memory role.
Scan beyond Onto Innovation and see which other chip equipment stocks are lining up behind the AI memory buildout with our hand picked 54 AI infrastructure stocks
Onto Innovation Investment Narrative Recap
To own Onto Innovation, you need to believe AI driven advanced packaging, HBM and panel level tools remain the main engine for its process control portfolio. The SK Hynix spotlight ties that thesis more tightly to real capacity projects and reinforces the near term focus on converting backlog in Dragonfly, Atlas and related systems into shipments.
The immediate swing factor is how quickly constrained HBM and AI packaging lines translate into tool orders and factory throughput, especially as extended factories already ship most systems. The biggest near term risk remains weaker semiconductor capex or power segment softness lasting longer, which could blunt that AI packaging strength and keep margins choppy.
The most relevant recent data point is SK Hynix flagging a long AI memory shortage and directly naming Onto Innovation’s defect prevention and metrology systems on HBM lines. That reference gives extra support to the existing narrative that large multi year Dragonfly commitments linked to HBM customers underpin revenue visibility into 2027.
For you as a shareholder, the catalyst is execution. Onto Innovation needs to turn that HBM recognition, the advanced packaging guidance lift for 2026 and extended factory footprint into clean shipments and better profitability, while managing risks like the Rigaku X ray spend and ongoing legal reviews that could add cost or distraction.
What The Onto Innovation Forecasts Assume
Onto Innovation's narrative projects US$2.4b revenue and US$832.7 million earnings by 2029. This is consistent with analyst assumptions for 29.5% yearly revenue growth and an earnings increase of about US$700 million from US$132.6 million today.
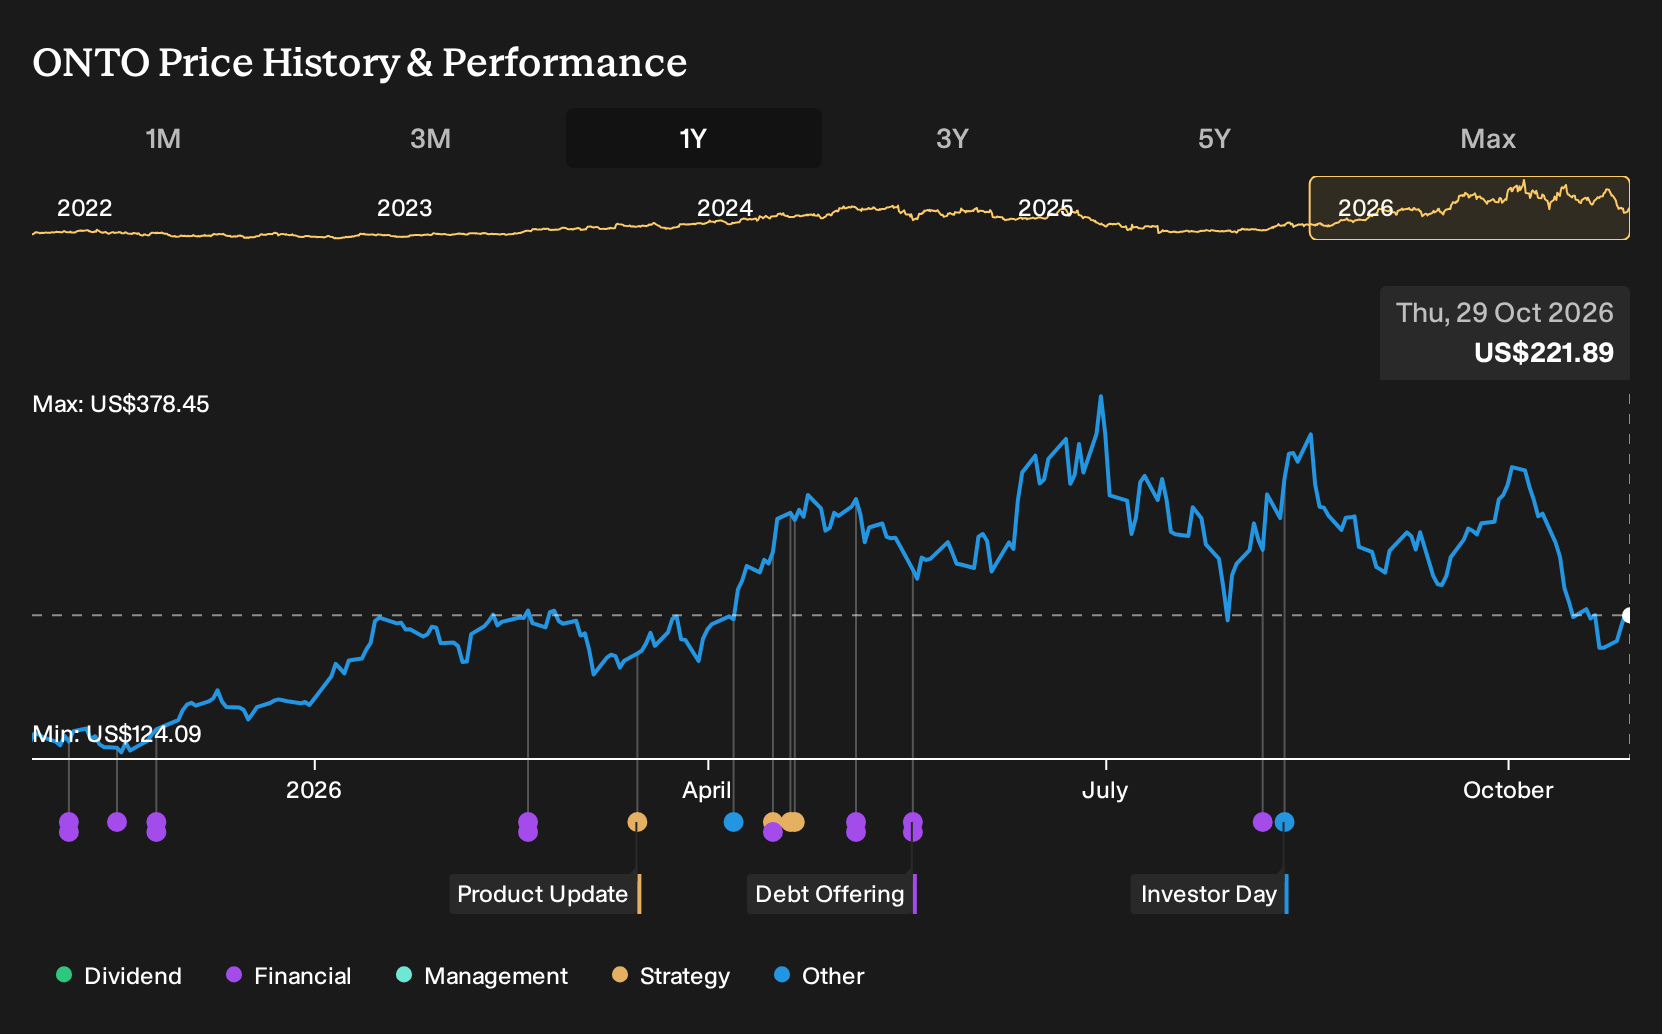
Uncover how Onto Innovation's fair value indicates a 74% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on Onto Innovation focuses on the bullish catalyst of richer recurring software and service revenue on top of Dragonfly and Atlas placements. The most optimistic analysts were already pencilling in about US$2.8b of sales and US$845.9 million of earnings by 2029. Those projections came before this SK Hynix spotlight, so views across the analyst spectrum may evolve and diverge further from here.
Explore 4 other Onto Innovation fair value estimates, including one that suggests there could be as much as 74% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Onto Innovation research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Onto Innovation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Onto Innovation's overall financial health at a glance.
Looking For More Investment Ideas Beyond Onto Innovation?
Once you have formed a view on Onto Innovation, it can help to compare it with other stocks that fit clear, rules based criteria using the Simply Wall St Screener.
- If you want potential growth with a small starting price, scan through 9 elite penny stocks with strong financials that already pair tiny share prices with stronger financial profiles.
- For investors who care about quality at a reasonable entry point, sift through a 30 high quality undervalued stocks that combine solid business strength with more modest valuations.
- If capital preservation matters most to you, focus on a 30 resilient stocks with low risk scores that score well on resilience and downside protection.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com