
Does Lowered 2026 Guidance Change The Bull Case For Oshkosh (OSK)?
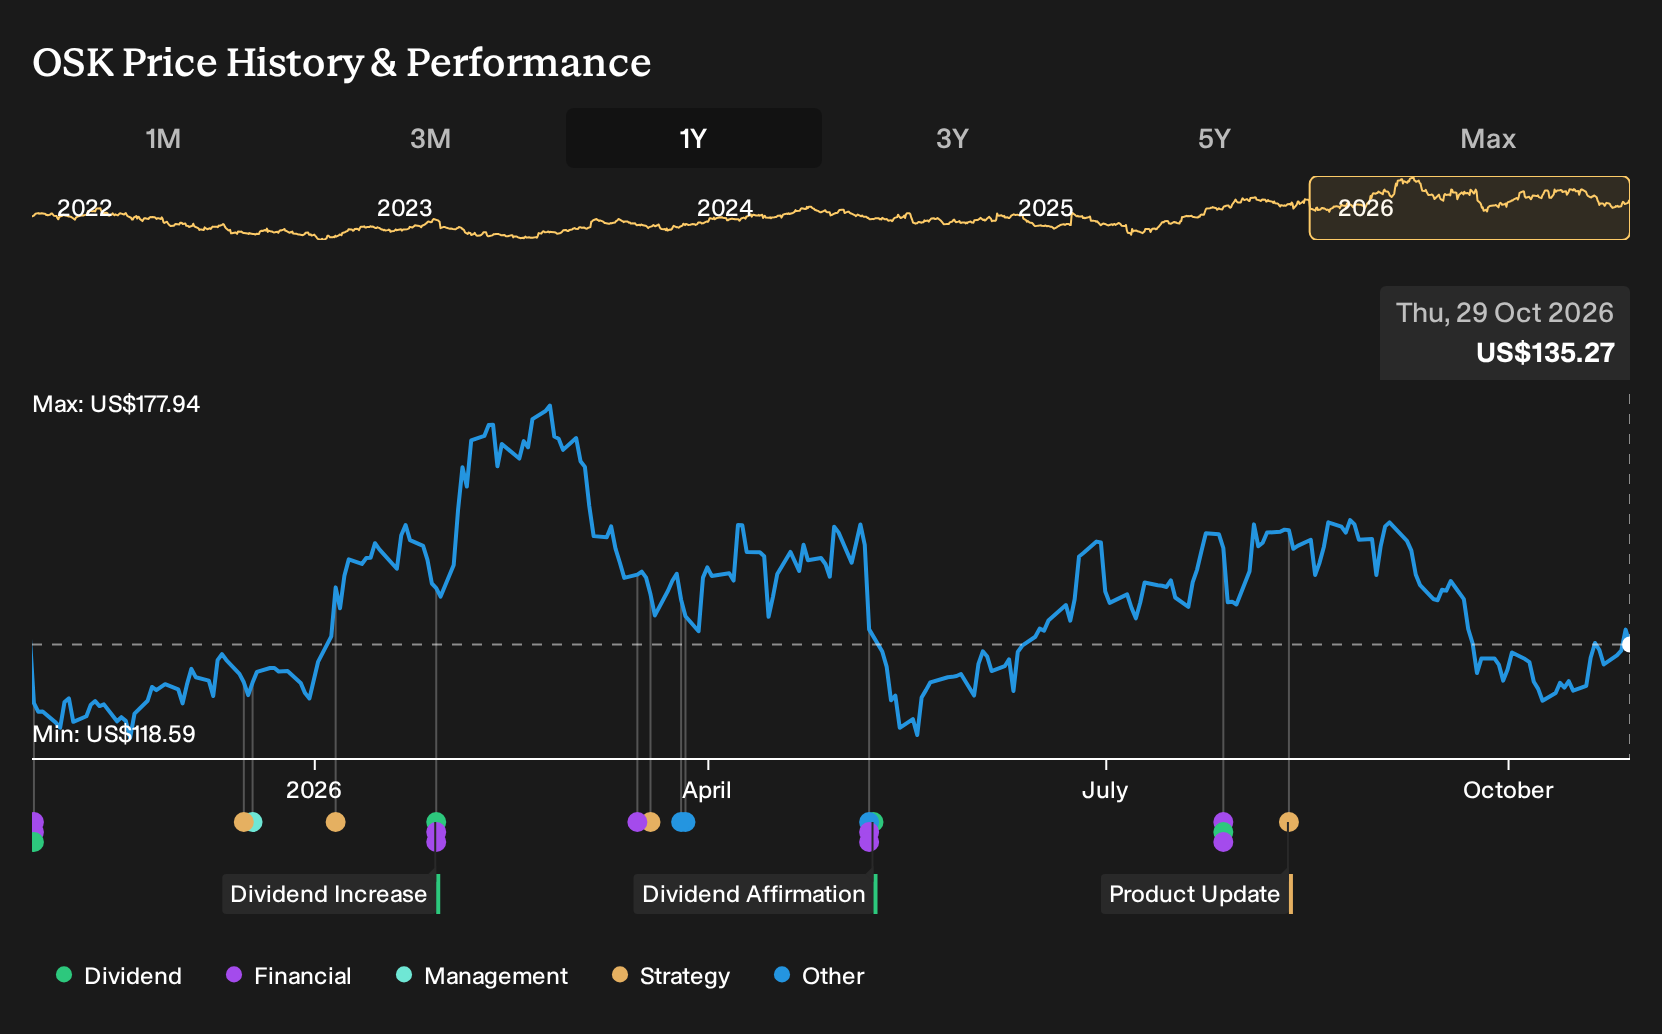
- Oshkosh cut its 2026 outlook after reporting third quarter 2026 results that showed higher sales but lower earnings and margins. Revised guidance calls for US$8.00 to US$9.00 in diluted EPS and about US$11.0b in net sales, citing weaker fire apparatus and NGDV production alongside strength in the Access segment.
- The guidance range now directly ties Oshkosh earnings to execution on U.S. Postal Service NGDV orders. Management noted that the low end assumes no 2026 NGDV award, which alone could affect results by up to US$0.50 per share and highlights how dependent the business has become on large contract timing.
- The focus now shifts to how Oshkosh's longer fire truck production ramp and lower 2026 guidance reshape the existing investment narrative.
Oshkosh Investment Narrative Recap
To stay invested in Oshkosh, you need to believe the fire apparatus transformation eventually translates into steadier Vocational margins, while Access keeps benefiting from infrastructure and data center demand. The lowered 2026 EPS and sales guidance directly tests that belief. In the near term, the key swing factor is how fast Oshkosh can clean up fire truck throughput without further production hiccups.
The biggest short term catalyst now lies in resolving those manufacturing inefficiencies and proving the new high flow processes actually work at scale. The largest risk is clear: a slower fix in fire trucks or weaker than expected NGDV volume could keep margins and earnings below what the existing longer term story assumes.
The earnings release for the third quarter of 2026 is the announcement that matters most here. Oshkosh reported quarterly sales of US$2,841.6m with net income of US$138.4m, alongside a lower 2026 EPS range of US$8.00 to US$9.00 and net sales guidance of about US$11.0b. That pairing of operational data and reduced outlook reframes near term expectations.
This report also sharpened investors’ focus on execution risk in NGDV and fire apparatus, just as Access segment demand remains a relative bright spot. The guidance link to possible 2026 NGDV orders, with up to US$0.50 per share at stake, puts contract timing and production quality control at the center of Oshkosh’s next leg of results.
Oshkosh's narrative projects US$12.9b revenue and US$1.1b earnings by 2029. That implies 6.7% yearly revenue growth and an earnings increase of about US$544m from US$556.3m today.
Explore how Oshkosh's fair value points to a 21% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate view on Oshkosh leans heavily on Access segment risk. The lowest analysts were already penciling in only 5.8% annual revenue growth and about US$819.3m in 2029 earnings before this guidance cut. That is a far more cautious story. Use this as a prompt to compare several narratives before deciding what you believe.
Explore 3 other Oshkosh fair value estimates, including one that suggests it could be worth just $163.48!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Oshkosh research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Oshkosh. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Oshkosh's overall financial health at a glance.
Looking for more investment ideas beyond Oshkosh?
If the Oshkosh story has you thinking about position sizing, contract exposure, and balance sheet resilience, it can help to set it alongside a wider watchlist of potential opportunities that fit different roles in your portfolio. The Simply Wall St Screener is built for exactly that kind of comparison, letting you filter the market by fundamentals rather than headlines.
- If you want potential mispriced opportunities with room for a re rating, scan through 30 high quality undervalued stocks and see which candidates merit a closer look on your watchlist.
- For investors who care most about financial strength and staying power, start with a list of solid balance sheet and fundamentals (23 results) to find businesses with the kind of resilience that can support a long holding period.
- When capital preservation is front of mind and you prefer steadier profiles, check out a 30 resilient stocks with low risk scores that filters for companies with lower risk scores and more defensive fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com