
Is Strive (ASST) Getting Too Rich for Its Book Value?
Strive has climbed 44.1% year to date even after a recent pullback, which puts a spotlight on whether the current share price still lines up cleanly with the company’s book value. With that kind of move already on the board, investors are increasingly asking how much of the balance sheet is already baked into the stock.
- The 44.1% gain year to date puts real pressure on the question of whether Strive’s present valuation can be explained by the net assets backing each share.
- The recent pricing of Strive’s upsized US$630m preferred SATS Stock offering may support plans that change the mix of assets and leverage on the balance sheet, which can shift how investors read the common equity’s book value support.
- The analysts covering Strive have run their own numbers. See what analysts think Strive's shares could be worth.
The stock’s next move may depend on whether Strive’s latest share price is well grounded in its book value relative to the industry average.
If you want a broader starting point while you weigh Strive against its balance sheet, apply the same book value lens to 30 high quality undervalued stocks.
Is Strive Getting Expensive on Book Value?
P/B fits Strive because the balance sheet and tangible backing matter more here than near term earnings or revenue.
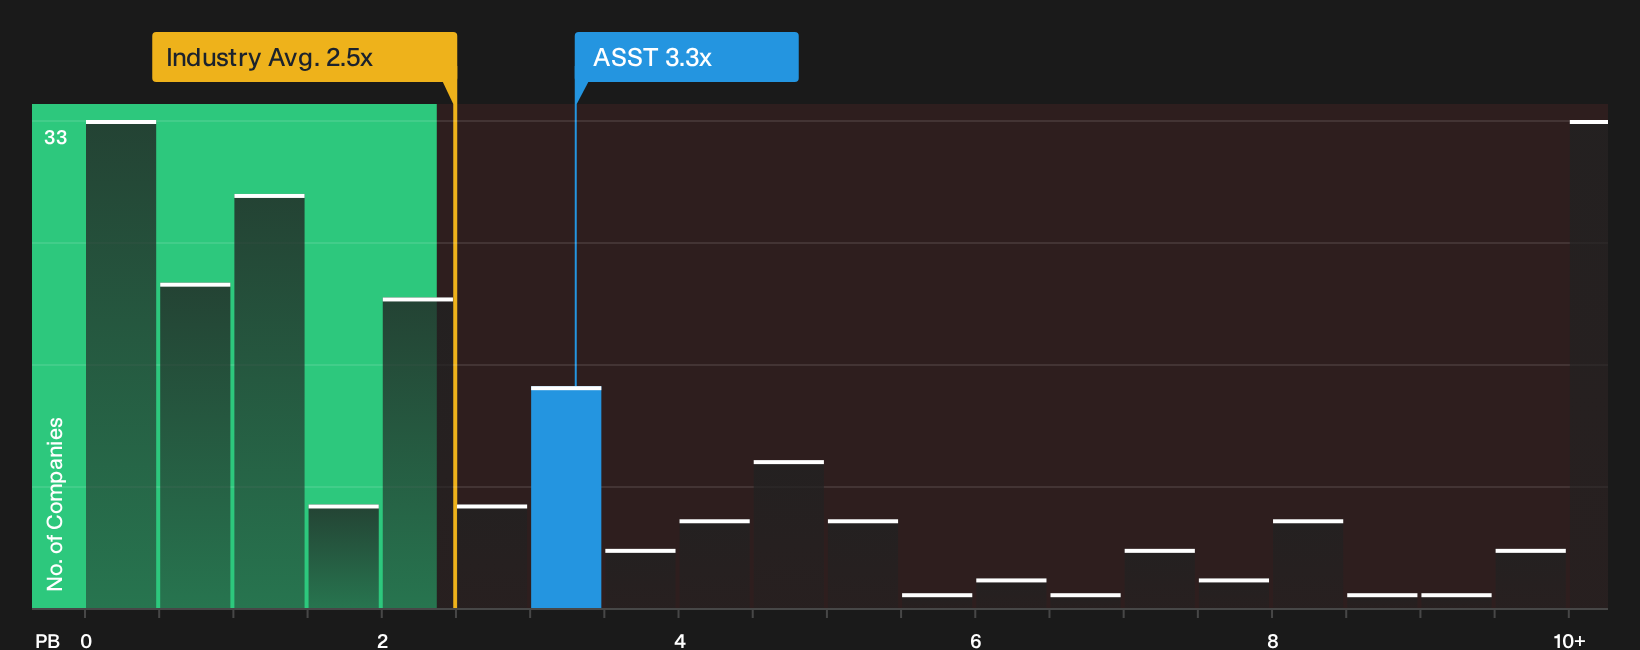
The stock currently trades on a P/B of 3.3x, which is above the Medical Equipment sector average of 2.5x and below peers at about 4.8x. Despite the recent preferred SATS Stock deal highlighting how aggressively Strive is using capital, the share price still values each dollar of book equity higher than the broader industry benchmark, which points to an overvalued reading on this metric. For you as a shareholder or potential buyer, the key question is whether that richer price against book is justified by what the asset base can realistically earn over time, or whether the premium is leaning too heavily on confidence in management’s capital allocation moves. Explore the numbers behind Strive's P/B valuation.
The Strive Narrative: What Would Justify Today's Price?
Strive’s valuation puzzle sets up a simple question that Narratives try to answer for you. They sketch out the kind of future on growth, profitability and earnings power that would need to play out for the stock to be worth much more or meaningfully less than today’s price, and they turn a single valuation output into a set of assumptions you can follow over time on Simply Wall St’s Community page.
A clear, written Narrative on Strive gives you a single, number driven view that pins current expectations about book value, returns on its asset base and balance sheet risk to specific assumptions you can monitor as fresh data arrives. With the recent US$630m SATS preferred stock deal reshaping Strive's capital structure, that kind of mapped out thesis also helps you track whether the use of proceeds and the 15.00% dividend burden are lining up with the valuation the market is putting on the common shares.
Share your own Narrative for Strive and set out the assumptions behind your valuation.
Strive’s price is only one piece of the decision
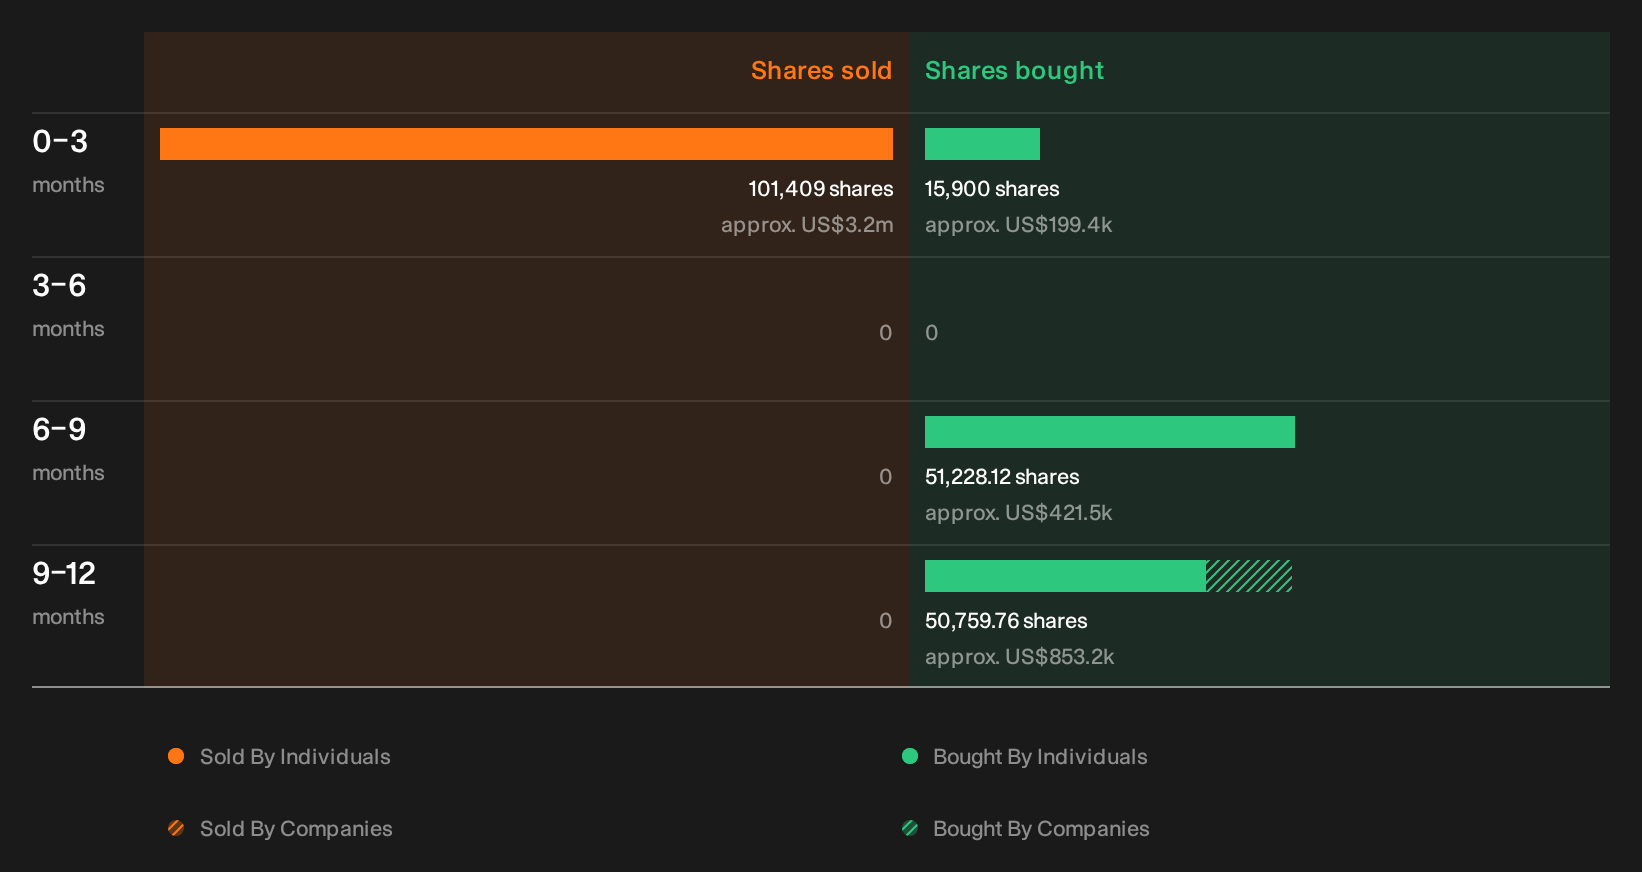
Book value and multiples tell part of the story, but recent trading by people inside Strive may reveal a different message about risk and conviction that you should check for yourself. See the recent insider selling flagged for Strive.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com