
Learn Why The Bull Case For Modine Manufacturing Stock Could Change Following Earnings Estimate Cuts
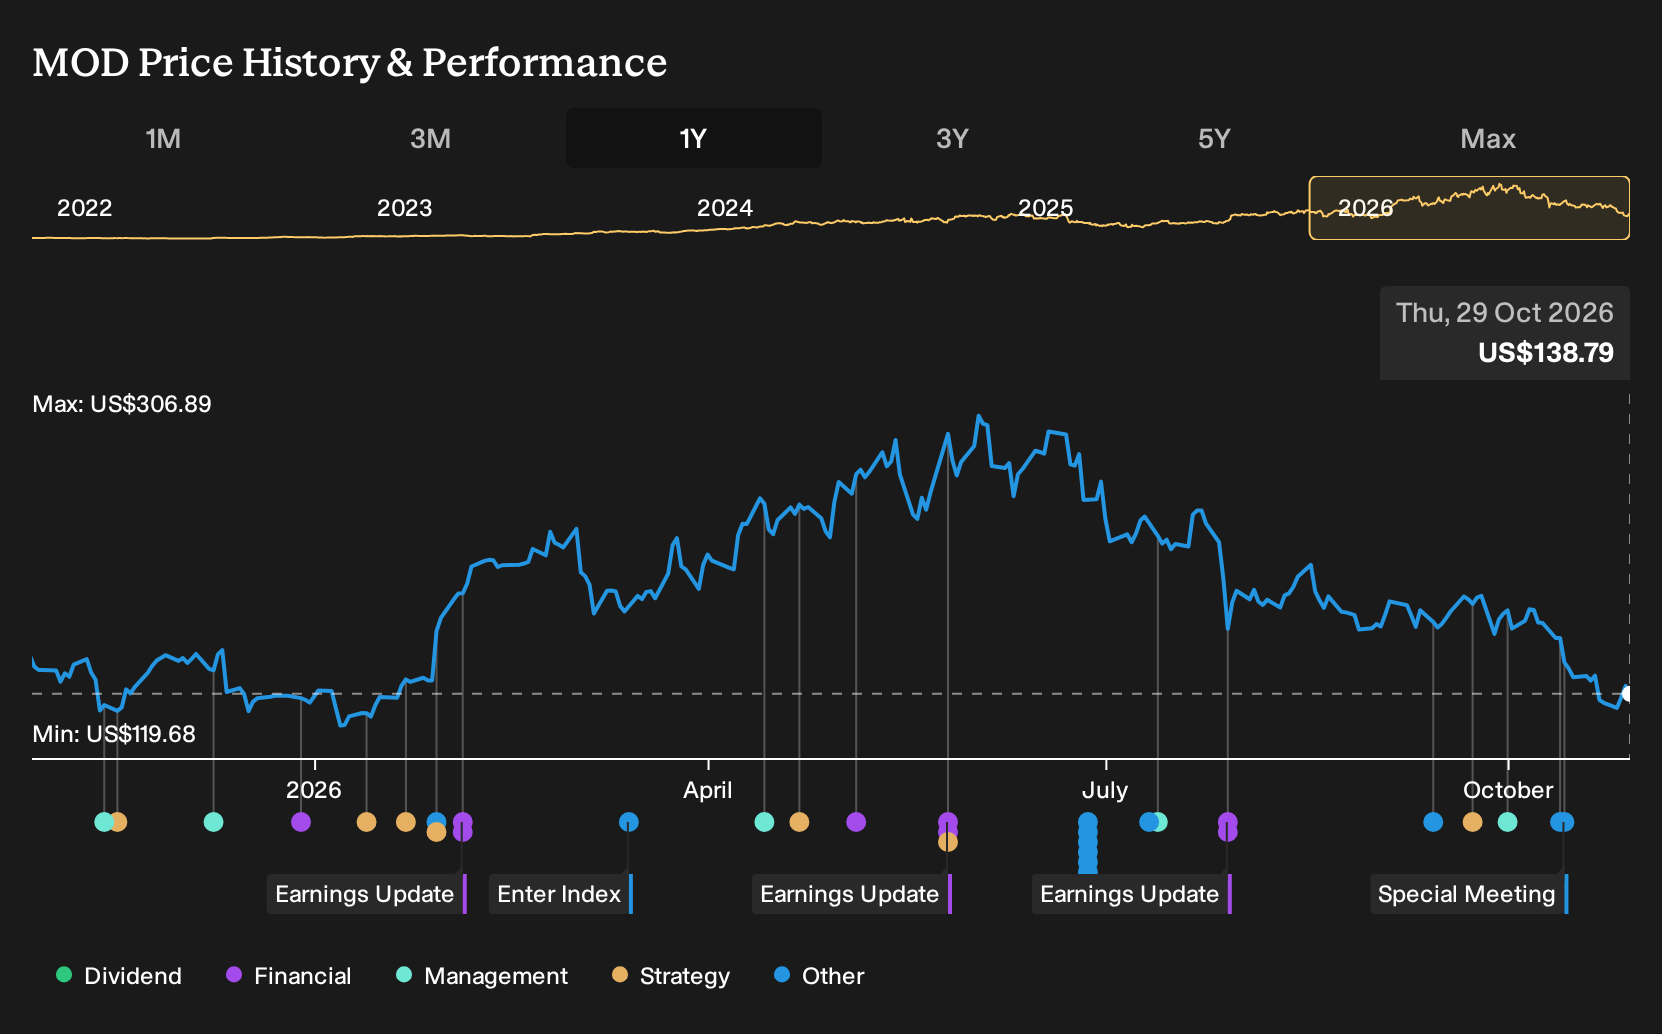
- Modine Manufacturing has recently faced downward revisions to earnings estimates for the current quarter and fiscal years, even as analysts still reference past revenue and profit growth in their commentary.
- The tension between weaker near term earnings expectations and a business that is focused on data center and climate solutions places Modine Manufacturing’s execution and cost control firmly in the spotlight.
- We will now examine how Modine Manufacturing’s investment narrative is affected by these earnings estimate cuts and the implied execution questions.
Modine Manufacturing Investment Narrative Recap
To own Modine Manufacturing, you essentially need to believe the shift toward data center and climate solutions can offset lumps in near term profitability. The recent drop in earnings estimates puts more pressure on near term execution, especially around filling new cooling capacity and managing mix so that lower margin products do not dilute already compressed 4.3% net margins.
In the short term, the most important catalyst is clean, predictable conversion of Modine Manufacturing’s large data center backlog into revenue as new capacity ramps. The biggest operational risk is that supply chain constraints or pricing on future contracts keep margins under strain. The latest estimate cuts highlight this risk but do not fundamentally change it.
The most relevant recent development is the company’s long term capacity agreement for more than US$4b of data center cooling product sales from 2027 to 2029. That contract, together with Modine Manufacturing’s target of about US$2b in data center revenue by fiscal 2028, frames why near term estimate volatility matters mainly through its impact on execution credibility.
That agreement is backed by a US$165m upfront payment and roughly US$100m of planned U.S. manufacturing investment, which ties directly into upcoming earnings reports. For you as a shareholder or potential shareholder, the key question is whether management can bring those assets online on time and at acceptable margins while avoiding the kind of supply constraints that already hurt gross margin by 340 basis points in Q1 fiscal 2027.
What The New Modine Manufacturing Forecasts Actually Assume
Modine Manufacturing's narrative projects US$4.6b in revenue and US$959.3m in earnings by 2029. Analysts are building in 10.5% yearly revenue growth and an earnings increase of about US$815.1m from US$144.2m today to reach that target.
Uncover why Modine Manufacturing's fair value indicates a 118% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For a very different angle on Modine Manufacturing, focus on the bullish view that treats the long data center capacity agreements as a powerful catalyst. Some of the most optimistic analysts were penciling in about US$7.3b of revenue and US$974.5m of earnings by 2029. Those pre news forecasts may shift, so consider them as one of several viewpoints to evaluate, not a script to follow.
Explore 2 other Modine Manufacturing fair value estimates, including one that suggests there could be up to 125% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Modine Manufacturing research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Modine Manufacturing. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Modine Manufacturing's overall financial health at a glance.
Looking For More Investment Ideas Beyond Modine Manufacturing?
Once you have a view on Modine Manufacturing, it often helps to compare it with other opportunities that match your risk tolerance and income goals. The Simply Wall St Screener can surface a wide range of alternatives that fit different portfolio roles, from stability to income to mispriced potential.
- If capital preservation is your priority, start with resilient businesses highlighted in our 30 resilient stocks with low risk scores that focus on steadier risk profiles.
- If you are hunting for mispriced quality, check out companies filtered in the 30 high quality undervalued stocks that combine solid fundamentals with more modest expectations baked into their prices.
- If consistent income matters most, focus on dependable payers in the 7 dividend fortresses that offer higher yields alongside an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com