
Is Delek US Holdings (DK) Trading At A Premium After Its 5 Year Run?
Delek US Holdings has delivered very strong long term returns, and after a sharp year to date rise, investors are increasingly asking whether the current share price still lines up with what its earnings can reasonably support. The question is simple but important for anyone looking at Delek US Holdings today: is the earnings power of the refiner keeping pace with the stock chart?
- Over the past 5 years the stock has returned about 3.7x, which puts a lot of weight on the idea that earnings can sustain or improve on the performance implied in that move.
- The recent decision by the US administration to use the Defense Production Act for oil production and refining may support capacity expansion at Delek US Holdings' Texas refinery, which can influence future profitability and the timing of cash flows tied to new projects.
- Your read on Delek US Holdings is one view; the desks covering it have another. See what analysts think Delek US Holdings's shares could be worth.
The stock's next move may depend on whether Delek US Holdings' current earnings justify the valuation investors are placing on it after this multi year run.
If you want a broader starting point while you weigh Delek US Holdings' earnings against its share price, a focused screen of 30 high quality undervalued stocks can help surface more ideas for your watchlist.
Does Delek US Holdings Look Pricey on Earnings?
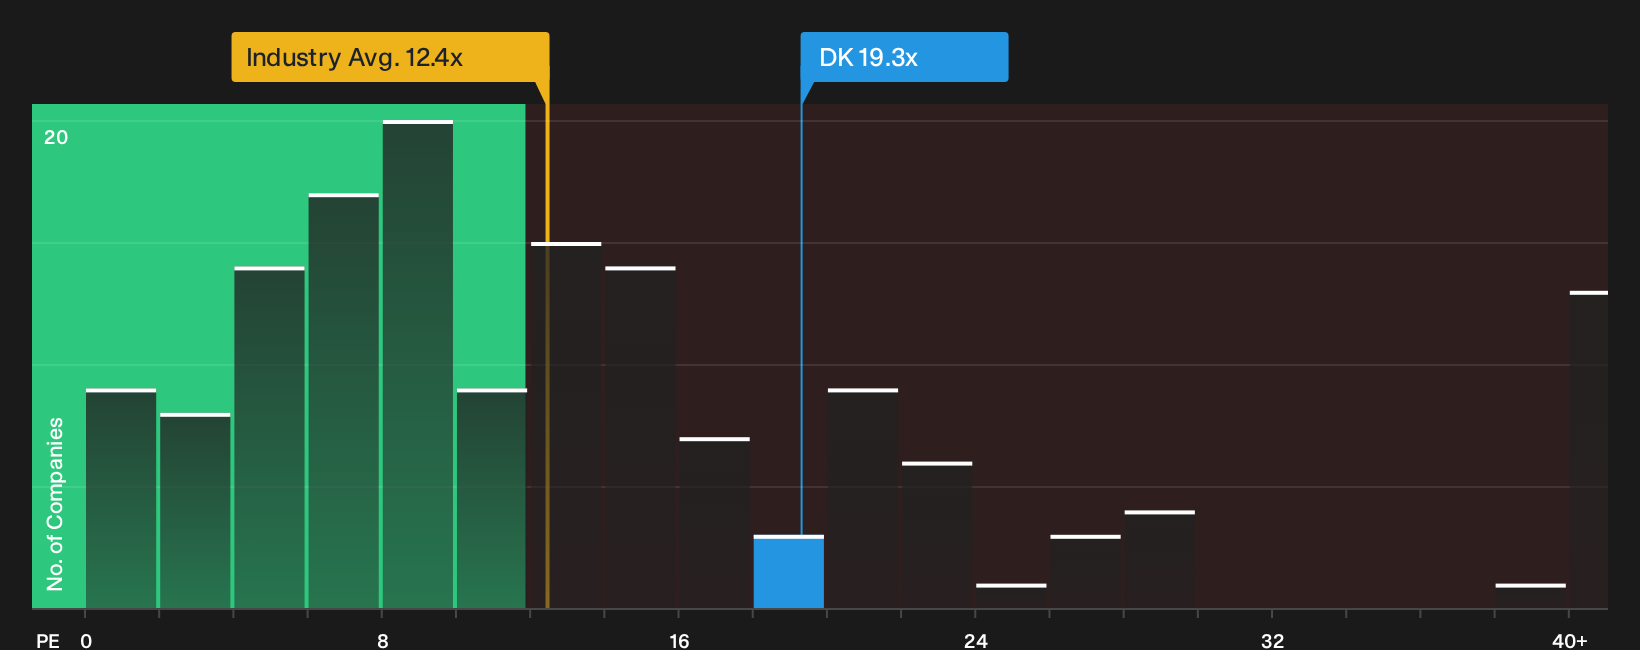
For Delek US Holdings, the P/E ratio is a clear way to see what the market is paying for each dollar of current earnings. The stock trades on about 19.3x earnings, which is above the Oil and Gas sector average of roughly 12.4x but below the peer group on about 26.1x.
Because the Defense Production Act support could reshape expectations for its Texas refinery economics, that mid pack positioning against peers still aligns with a richer price tag than the tailored fair multiple estimate suggests. On this framework, Delek US Holdings screens as overvalued because its P/E stands above the level implied by its own mix of growth prospects, profitability and risk, even though it does not fully match the more expensive peer group. Explore the numbers behind Delek US Holdings's P/E valuation.
The Delek US Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Delek US Holdings leaves off, by spelling out which assumptions on future growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price. Rather than relying on a single multiple or model output, each narrative lays out the moving parts behind its view of fair value so you can compare those expectations with Delek US Holdings' actual results as they are reported. Narratives live on Simply Wall St's Community page and give you a clearer line of sight between the story around the stock and the numbers that would need to follow.
Community views on Delek US Holdings split between margin-led improvement and regulatory plus cost pressure pulling the other way.
Bull case: 16% undervalued
"Delek's sustained operational improvements, driven by its enterprise optimization program (EOP), which targets structural changes in refinery operations, procurement, and product sales, are expected to deliver $130–$170 million of annualized cash flow enhancements…"
Discover why this Narrative puts Delek US Holdings at 16% undervalued.
Bear case: 15% overvalued
"Regulatory decisions on small refinery exemptions remain critical, and despite a recent 2025 exemption decision that Delek US Holdings welcomed, the company still faces a projected 2026 Renewable Fuel Standard cost of about US$750 million at a US$1.50 blended RIN price…"
Explore why this Narrative puts Delek US Holdings at 15% overvalued.
One more Delek US Holdings check that belongs beside the earnings discussion
Price and earnings only tell part of the story for Delek US Holdings, because Simply Wall St's broader review has also flagged specific risk checks that deserve a closer look before you form a view. Take a closer look at 4 warning signs (2 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com