
Does Earnings Decline Change The Bull Case For QXO (QXO)?
- QXO is expected to report earnings for the September 2026 quarter that decline compared with the prior year, even though quarterly revenue is projected to be higher, reflecting pressure on profitability despite top line growth.
- Technoform North America recently selected QXO as a new distribution partner for warm edge spacers in the western U.S., highlighting how the business is trying to build operational scale while near term earnings expectations are under pressure.
- We will look at how QXO's investment narrative is affected by weaker earnings expectations alongside its new Technoform distribution partnership.
Scan how QXO's setup compares with other distributors facing similar margin pressure by reviewing our hand picked list of solid balance sheet and fundamentals (23 results).
What Is QXO's Investment Narrative?
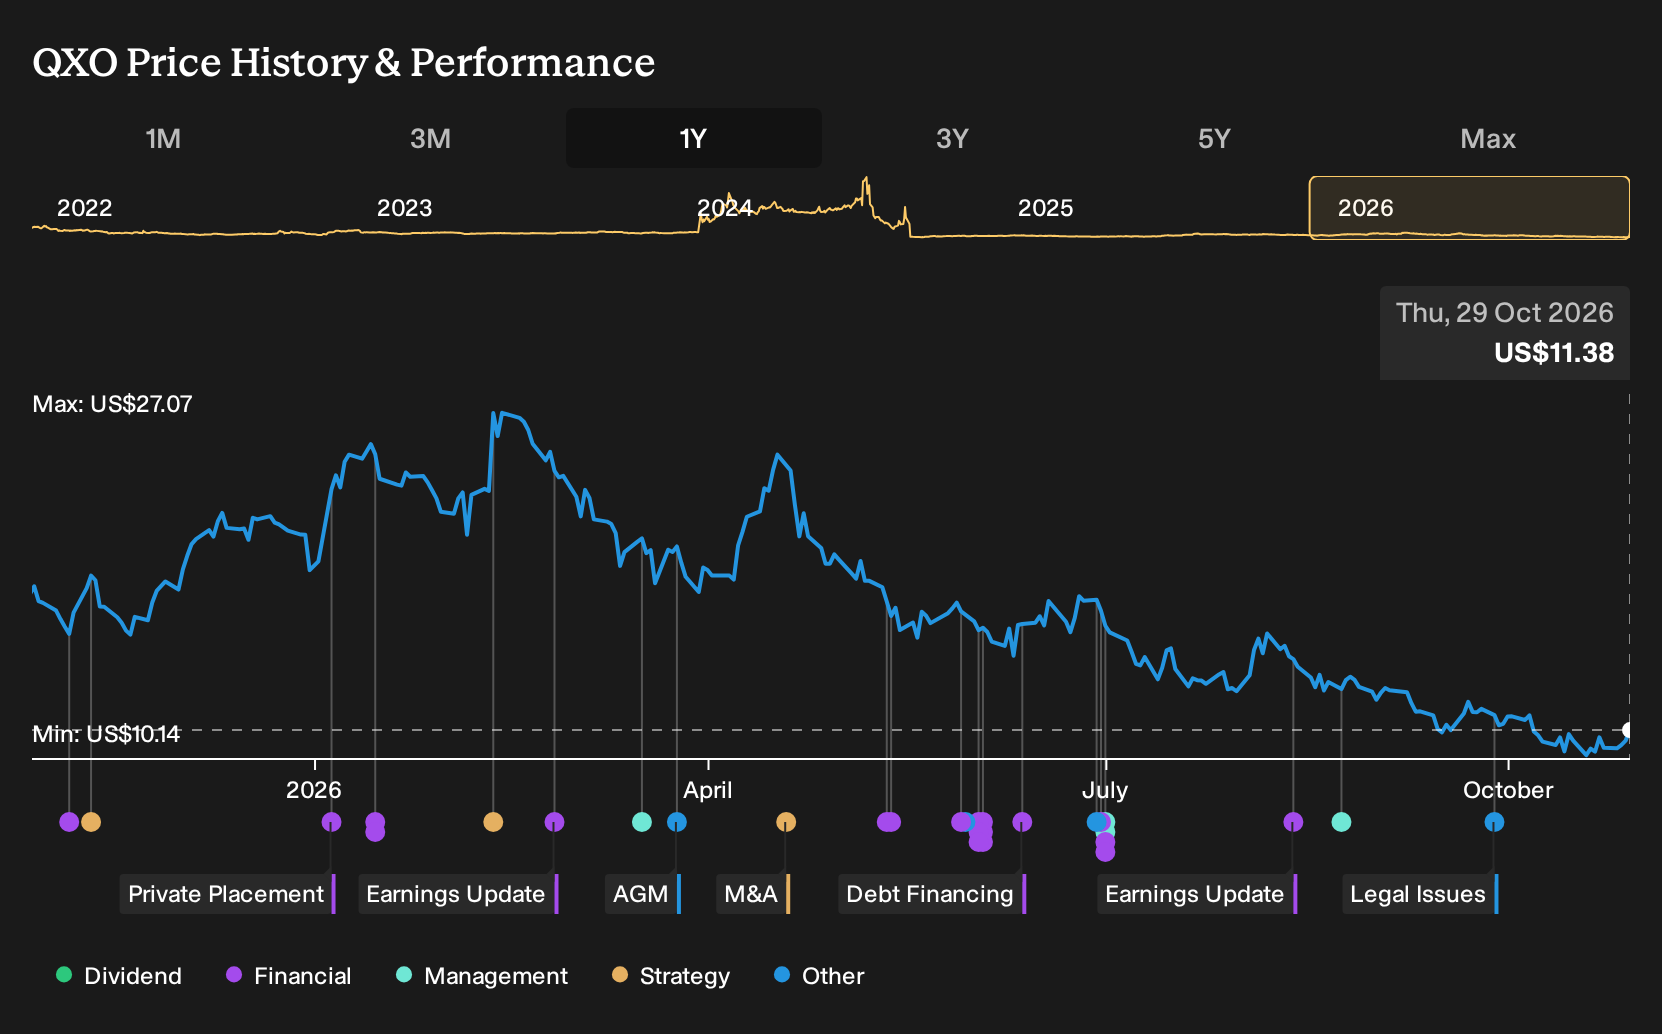
For a shareholder, the core belief around QXO is simple. You are backing a building products distributor that is chasing scale, higher volumes and better customer reach while still working through unprofitability and margin pressure. The Technoform North America deal sits squarely in that story. It helps QXO deepen its footprint in glass and fenestration products, tighten lead times in the western U.S. and potentially improve warehouse utilization, even as near term earnings expectations, including that weaker September 2026 EPS setup, point to ongoing profit strain.
The near term catalysts are mostly about execution. Investors are watching whether QXO can translate mid 20s style revenue growth forecasts into cleaner unit economics, steady pricing and better cost control, without leaning too hard on higher risk borrowing or fresh equity after prior dilution. The Technoform partnership looks helpful for demand and service levels, but it does not change the key risk that the business remains loss making today and that recent earnings misses keep short term expectations fragile if operating expenses or capital needs step up again.
That said, there is one structural issue around QXO that could matter far more than any single quarter or contract win...
There's only one way to know the right time to buy, sell or hold QXO. Head to Simply Wall St's company report for the latest analysis of QXO's Fair Value.
Exploring Other Perspectives
Fair value estimates for QXO from three Simply Wall St Community members span roughly US$24.06 to US$41.35, a wide spread for such a small sample. Those views were formed before the recent EPS downgrades and new Technoform distribution deal, so treat them as a starting point and explore multiple fresh perspectives.
Explore 2 other QXO fair value estimates, including one that suggests it could be worth just $24.06!
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your QXO research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for QXO. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate QXO's overall financial health at a glance.
Looking For More Investment Ideas Beyond QXO?
If QXO is on your radar, it often helps to stack it up against other potential opportunities and build a broader watchlist using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, scan through 30 high quality undervalued stocks that may warrant a closer look.
- For readers who care most about income resilience, focus on companies in the 7 dividend fortresses that target higher yields with an emphasis on durability.
- If capital preservation matters just as much as upside, start with the 30 resilient stocks with low risk scores that screen for resilience and lower risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com