
Earnings Miss Could Be A Big Test For First Busey Stock (BUSE)
- First Busey reported third quarter 2026 net income of US$55.85 million on net interest income of US$153.15 million, with diluted earnings per share from continuing operations of US$0.61 and materially higher net charge-offs of US$11.37 million versus the prior year period.
- The bank cited a partial commercial credit charge-off of US$10 million and a non accrual designation as key pressures, even as deposits grew at an 11% annualized rate for a second straight quarter and the loan to deposit ratio improved.
- The important consideration is how this earnings miss, combined with a spike in charge-offs, could reshape First Busey’s investment narrative.
What Is First Busey's Investment Narrative?
For anyone considering First Busey, the core belief is that a conservative regional bank model with a mix of traditional lending, wealth management and payments can still create steady value, even when credit costs flare. The latest quarter tests that idea. Earnings per share from continuing operations held at US$0.61 on net interest income of US$153.15 million, yet a US$10 million partial commercial credit charge-off, higher net charge-offs of US$11.37 million and a non accrual designation put the focus squarely on underwriting, workout execution and loan review.
In the short term, the key swing factors now are credit quality trends, deposit behaviour and how consistently management prices risk in a slow growth revenue backdrop. Deposits growing at an 11% annualised rate and an improving loan to deposit ratio point to stable funding, while a 3.53% dividend yield and a P/E of 11.3x frame how the market values that stability. The key question is whether the recent spike in one off items and charge-offs is an isolated clean up or a sign investors in First Busey should brace for more credit pressure.
That said, there is one uncomfortable angle to this credit story that does not show up cleanly in the quarterly tables...
There's only one way to know the right time to buy, sell or hold First Busey. Head to Simply Wall St's company report for the latest analysis of First Busey's Fair Value.
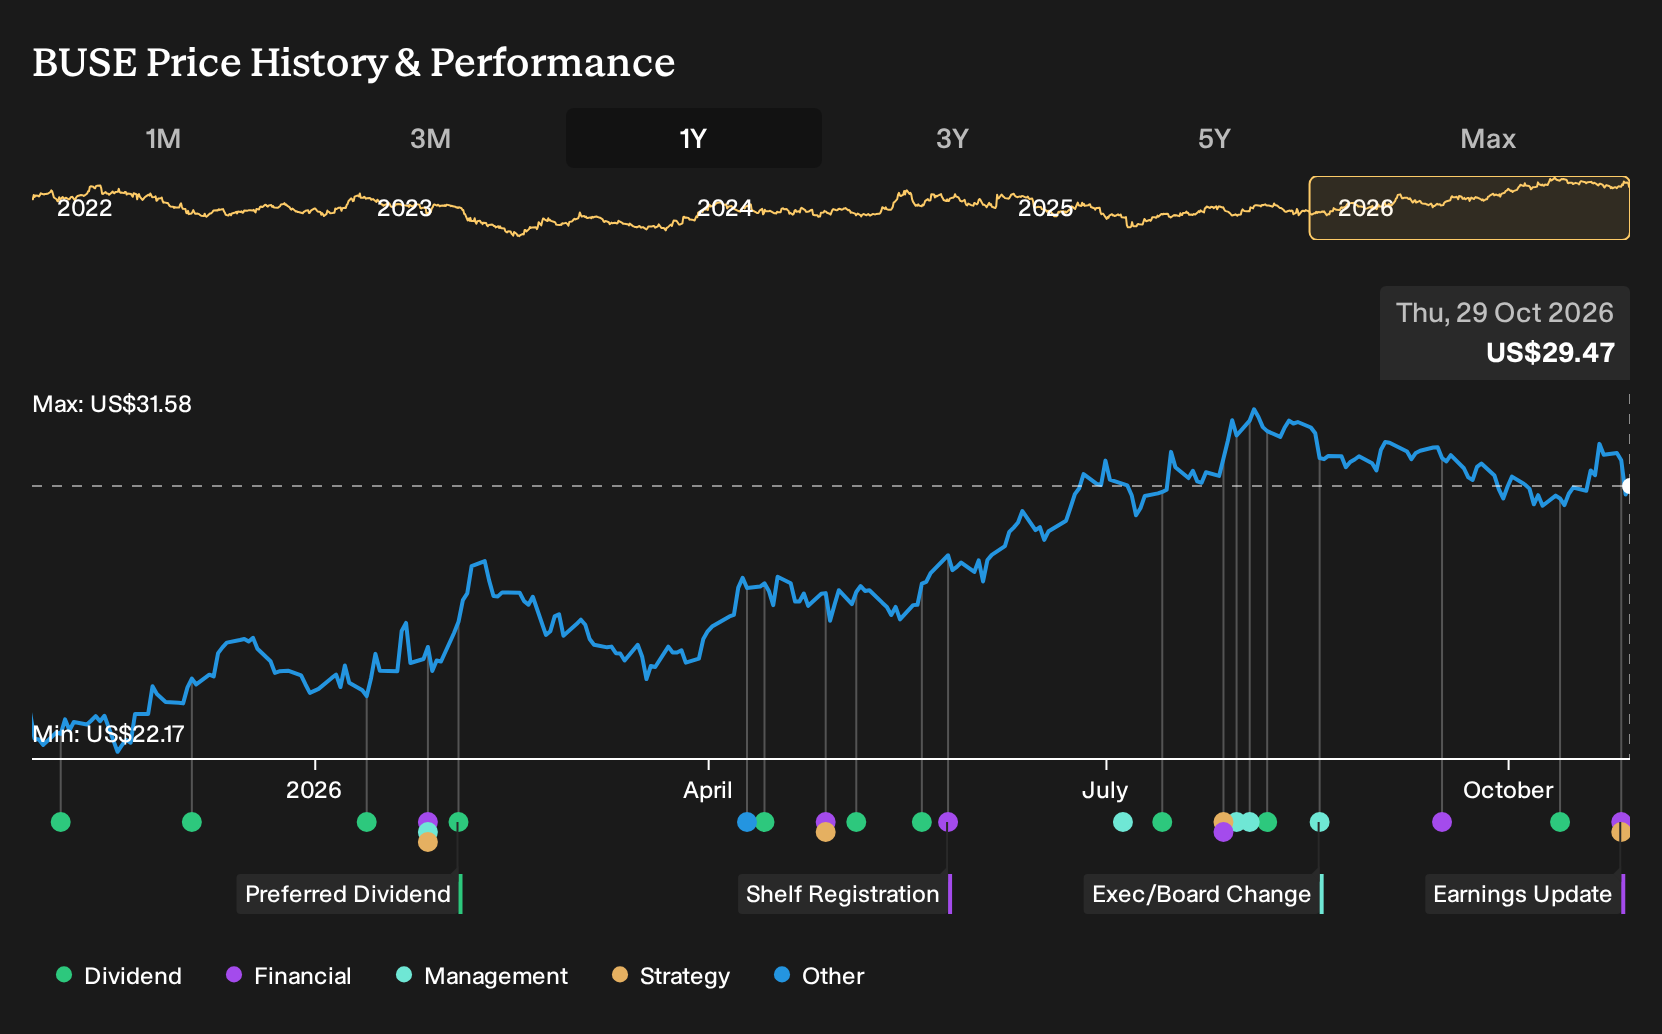
Exploring Other Perspectives
Fair value views on First Busey from the Simply Wall St Community span roughly US$32.29 to US$49.46 across 2 individual analyses. This already shows how far apart private investors can be. Those estimates pre date the October 27 earnings and credit charge-offs, so you should weigh them against fresh information and conflicting opinions.
Explore another First Busey fair value estimate, including one that suggests it could be worth just $32.29.
The Verdict Is Yours
Do not just follow the ticker; dig into the data and build a conviction that is truly your own.
- A great starting point for your First Busey research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for First Busey. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Busey's overall financial health at a glance.
Looking For More Investment Ideas Beyond First Busey?
If this earnings story has prompted you to widen your watchlist beyond First Busey, the Simply Wall St Screener can help you quickly surface other opportunities that better fit your risk, income or value preferences.
- If capital preservation sits high on your list, start with a curated set of resilient businesses through the 30 resilient stocks with low risk scores.
- If income is the priority, focus on companies with stronger yields using the 7 dividend fortresses.
- If you prefer to hunt for mispriced quality, scan for potential bargains in the 30 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com