
Should Earnings Outlook Require Action From Acadia Pharmaceuticals (ACAD) Investors?
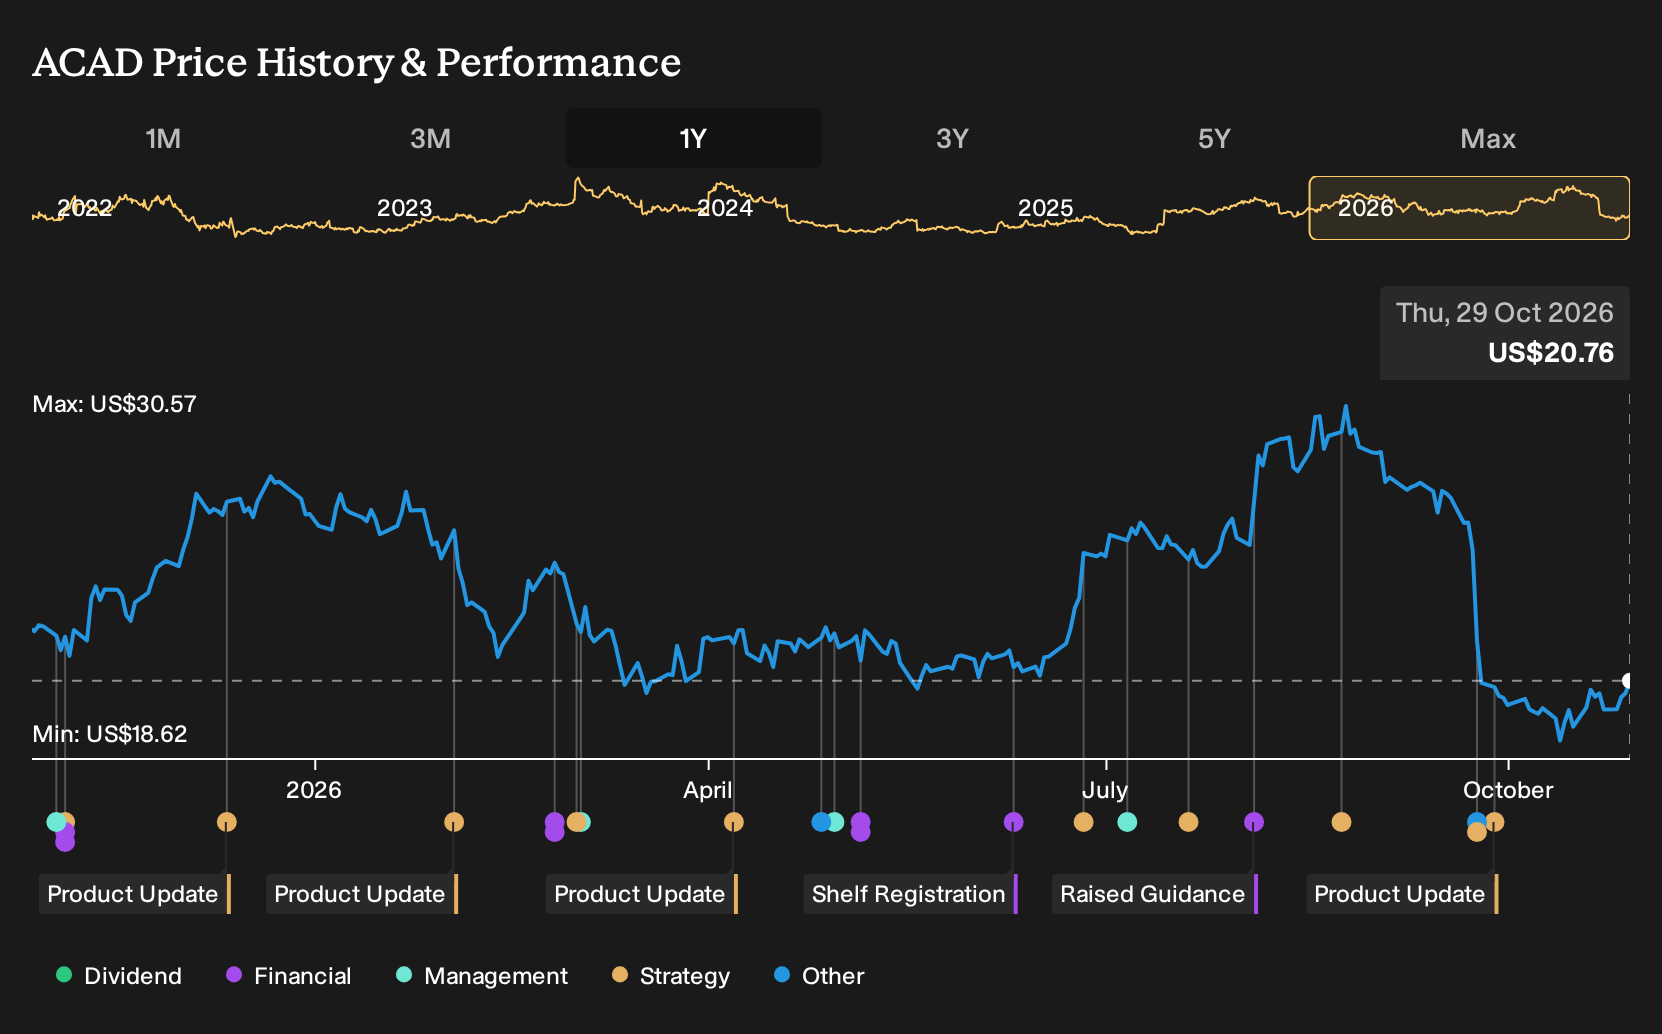
- Acadia Pharmaceuticals recently drew attention with expectations for its September 2026 quarter, where analysts project earnings per share of $0.21 and revenue of about $334.87 million, while the company also prepared to appear at the UBS Global Biopharma Conference.
- The mix of projected lower earnings and higher sales puts Acadia Pharmaceuticals' cost structure and product profitability in focus, as investors consider how efficiently new and existing therapies are being scaled.
- This article now examines how Acadia Pharmaceuticals' expected earnings decline, despite higher revenue, could shape its broader investment narrative.
Scan beyond Acadia Pharmaceuticals and compare its setup with hand-picked biopharma players in our 18 high quality undiscovered gems that may be flying under the radar.
Acadia Pharmaceuticals Investment Narrative Recap
To own Acadia Pharmaceuticals, you need to believe the current product engine in neurological and rare diseases can support durable revenue while the pipeline creates new options beyond DAYBUE and NUPLAZID. The near term hinge remains clean execution on launches and formulary access. The projected mix of higher sales and softer earnings keeps efficiency, rebates and commercial spending squarely in focus.
The biggest risk is that key programs like remlifanserin or broader pipeline assets fail to translate into the multi billion opportunity some models reference, especially as R&D spending is trimmed. The coming earnings print looks important for reading unit trends, gross margin quality and how aggressively management is funding late stage trials.
The upcoming fireside chat at the UBS Global Biopharma Conference puts Acadia Pharmaceuticals in front of a concentrated healthcare audience right after an earnings release that is expected to show lower EPS with higher revenue. That timing matters. Management will be pressed on whether the current cost base is right for the growth ambition and on how it thinks about prioritizing programs.
For catalysts, investors will likely listen most closely for incremental color on DAYBUE uptake, NUPLAZID durability and how remlifanserin plans evolve after the mixed Phase II outcome. Any extra operational detail on ex US trofinetide rollout or R&D phasing could either reinforce confidence that earnings pressure is temporary or highlight that margin compression risk is sticking around.
Acadia Pharmaceuticals' narrative projects US$1.7b revenue and US$329.3 million earnings by 2029. This assumes 13.5% yearly revenue growth and an earnings decrease of about US$51.2 million from current earnings of US$380.5 million.
Uncover why Acadia Pharmaceuticals' fair value indicates a 47% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle focuses on DAYBUE and NUPLAZID as bigger long term drivers for Acadia Pharmaceuticals than the baseline view implies. The most optimistic analysts were penciling in about US$1.9b of revenue and US$583.6 million of earnings by 2029, before this UBS conference news. That is a far brighter story than the consensus, and it may shift again once fresh commentary lands.
Explore 5 other Acadia Pharmaceuticals fair value estimates, including one that suggests potential upside of up to 337% from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Acadia Pharmaceuticals research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Acadia Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Acadia Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Acadia Pharmaceuticals?
Once you have a handle on Acadia Pharmaceuticals, it can help to widen the lens and compare it with other businesses that fit different risk, value, and income profiles using the Simply Wall St Screener.
- Prefer steadier profiles with fewer red flags over rollercoaster charts? Then scan through our 30 resilient stocks with low risk scores for candidates that may better match a capital preservation mindset.
- If value is the priority and you want stocks where quality fundamentals meet potentially attractive pricing, start with this curated 30 high quality undervalued stocks and see which businesses line up with your checklist.
- For readers who care most about income and cash flow support, review this hand picked 7 dividend fortresses to find higher yielding payers that might warrant a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com