
What Is Behind Chongqing Rural Commercial Bank (SEHK:3618) Shares Climbing Today?
Why Chongqing Rural Commercial Bank’s latest earnings matter
Chongqing Rural Commercial Bank (SEHK:3618) just released nine month figures to 30 September 2026, with net interest income and net income both higher than the same period a year earlier.
Basic and diluted earnings per share from continuing operations came in at CNY 0.99 versus CNY 0.92 previously, drawing attention to how this regional lender is converting its balance sheet into profit.
Investors have reacted quickly to the results, with Chongqing Rural Commercial Bank’s share price rising to HK$6.775 and delivering a 4.31% 1 day share price return. The 1 year total shareholder return of 12.47% sits on top of a very large 5 year total shareholder return that suggests momentum has been building over a longer horizon.
Scan how Chongqing Rural Commercial Bank’s earnings momentum compares with other financials by reviewing our hand-picked list of solid balance sheet and fundamentals (203 results)
After Chongqing Rural Commercial Bank’s sharp move on the back of these earnings, the key question is straightforward: Is this already a fair price for the progress so far, or does waiting risk missing more upside if valuation still looks modest?
Preferred P/E of 5.1x: Is it justified?
On today’s numbers, Chongqing Rural Commercial Bank trades on a P/E of 5.1x, which places the share price of HK$6.775 roughly in line with the wider Hong Kong Banks industry but slightly above the direct peer average.
The P/E ratio compares what investors are paying for each unit of current earnings. For a lender like Chongqing Rural Commercial Bank, this measure often reflects how the market weighs its profitability, balance sheet strength, and perceived risk relative to other banks listed in Hong Kong.
Here the picture is mixed. The stock is described as expensive against the peer average P/E of 5x, yet it is characterised as good value compared with the Hong Kong Banks industry average P/E of 5.1x and an estimated fair P/E of 6.9x. That suggests the current multiple leaves some room for the P/E level to move toward that fair ratio if earnings progress and risk perceptions stay consistent with what is implied by the model.
3618 is considered good value based on its P/E of 5.1x versus the estimated fair P/E of 6.9x, which points to a discount that might attract investors who focus on earnings based valuation benchmarks.
Explore the SWS fair ratio for Chongqing Rural Commercial Bank.
Result: Price-to-earnings of 5.1x (UNDERVALUED)
Still, the Chongqing Rural Commercial Bank story can be knocked off course if asset quality weakens or if tighter funding conditions squeeze future profitability.
Find out about the key risks to this Chongqing Rural Commercial Bank narrative.
Another view on Chongqing Rural Commercial Bank’s value
While the P/E of 5.1x makes Chongqing Rural Commercial Bank look inexpensive against its own fair ratio of 6.9x, the SWS DCF model presents an even lower implied value. With the share price at HK$6.78 and the model suggesting HK$20.68, the gap is wide enough to make any investor ask what the market is pricing in.
Look into how the SWS DCF model arrives at its fair value.
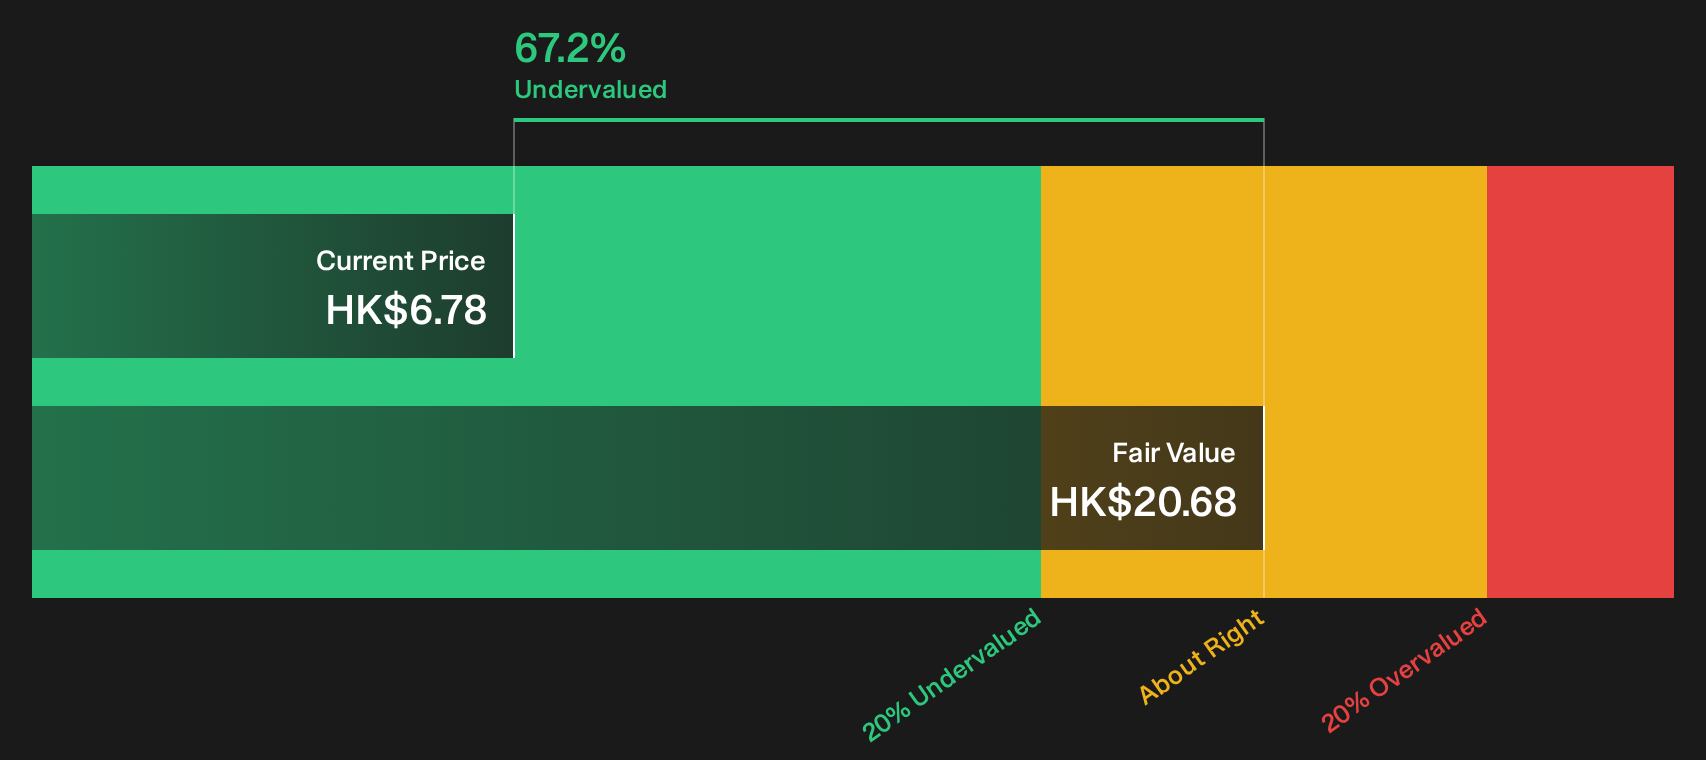
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Chongqing Rural Commercial Bank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 200 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Chongqing Rural Commercial Bank is mixed. If you want to move quickly and shape your own view, it helps to see both sides of the story in detail with the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Chongqing Rural Commercial Bank?
If Chongqing Rural Commercial Bank has caught your attention, do not stop here. Broaden your watchlist and give yourself more choices before the next move.
- Explore potential mispricing by scanning companies that look attractively valued on both quality and fundamentals through the 200 high quality undervalued stocks.
- Review companies with higher yields that pass strict balance sheet checks via the 222 dividend fortresses to help strengthen your income stream.
- Focus on businesses that clear tough resilience filters in the 220 resilient stocks with low risk scores to help dial down overall portfolio risk.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com