
Buyback Boost Could Be A Game Changer For First Commonwealth Financial Stock
- First Commonwealth Financial reported third quarter 2026 net interest income of US$116.32 million and net income of US$44.94 million, alongside lower net charge offs of US$4.58 million compared with the same period in 2025.
- The bank paired these results with a higher quarterly dividend and an expanded US$100 million share repurchase plan, which indicates continued use of excess capital for shareholder returns while credit costs remain contained.
- We will now look at how First Commonwealth Financial's larger buyback authorization could influence the existing investment narrative for the bank.
Scan how First Commonwealth Financial's share repurchase and dividend decision fits into a broader pattern of disciplined capital return by reviewing a hand picked set of 30 resilient stocks with low risk scores.
First Commonwealth Financial Investment Narrative Recap
For a shareholder in First Commonwealth Financial, the core belief is that a relatively solid net interest margin, a more granular loan mix and growing fee lines can keep earnings resilient. The latest quarter broadly fits that picture, with higher net interest income and net income alongside sharply lower net charge offs of US$4.58 million, which keeps credit quality from being the near term swing factor.
The more immediate swing factor now sits with funding costs and deposit competition, since those will influence how much of that margin the bank keeps. The key risk remains pressure on deposits and loan growth if digital capabilities lag peers or large commercial payoffs persist, and this earnings print does not materially change that risk balance.
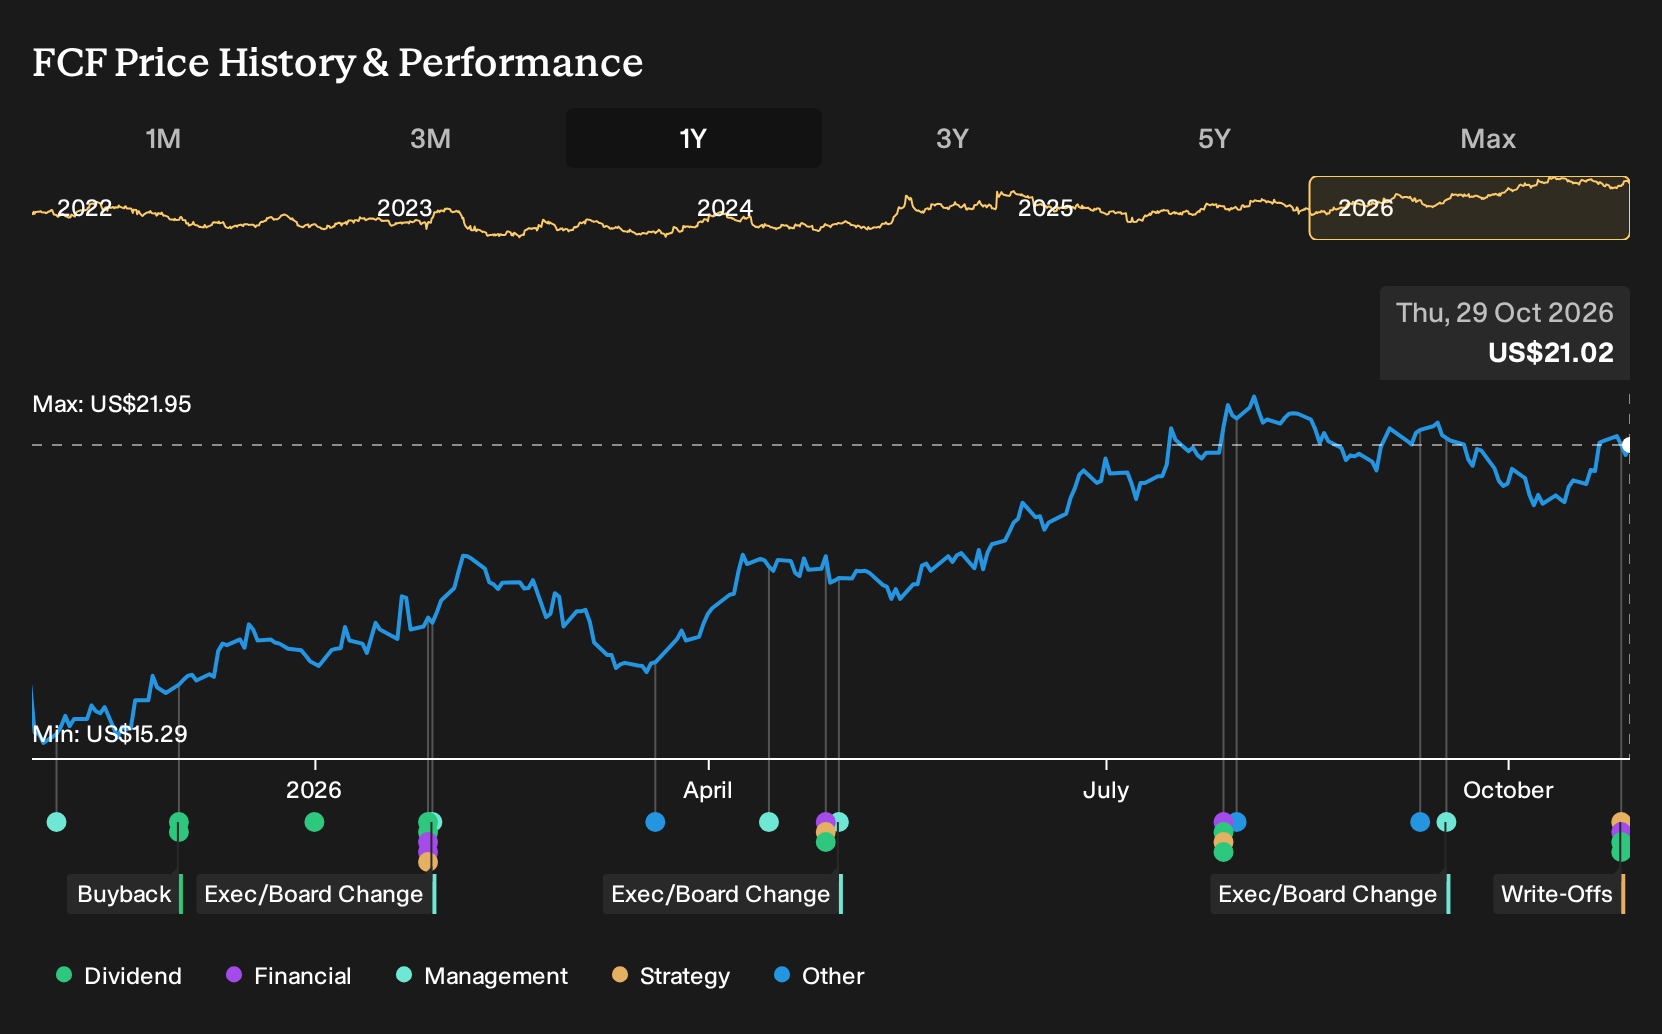
The most relevant fresh data point for this story is the US$100 million buyback plan and the repurchase of 4,802,459 shares, or 4.76% of the base, through September 30, 2026. That capital return choice leans on the view that earnings quality, credit costs and capital ratios can support ongoing distributions while the business keeps investing in lending and technology.
For you as an investor, the repurchases and higher dividend intersect directly with the main catalysts and risks. They amplify the impact of any future progress on deposit pricing, loan mix and fee income, but they also leave less room if funding costs rise or digital investments need to accelerate, so execution around deposits and tech remains central to the First Commonwealth Financial story.
First Commonwealth Financial's analyst narrative points to revenues of US$661.2 million and earnings of US$224.9 million by 2029, based on forecast revenue growth of 9.2% per year and an earnings increase of about 34% from US$168.3 million today.
Uncover how First Commonwealth Financial's fair value indicates a 15% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$24.07 to US$37.79, so private investors are already assigning a wide range of outcomes to First Commonwealth Financial. Consider those views in the context of tighter loan growth, rising digital banking risks and higher deposit competition, then compare multiple viewpoints before updating your own stance.
Explore another First Commonwealth Financial fair value estimate, including one that suggests it could be worth just $24.07.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your First Commonwealth Financial research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for First Commonwealth Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Commonwealth Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond First Commonwealth Financial?
If the First Commonwealth Financial setup has you thinking about portfolio balance, use the Simply Wall St Screener to find other businesses with traits that fit your risk and income goals.
- For investors who want to keep downside in check, start with a curated 30 resilient stocks with low risk scores that screen well on resilience and overall risk profile.
- If reliable balance sheets are the priority, scan a list of solid balance sheet and fundamentals (23 results) that already pass strict financial health filters.
- When you want income on top of stability, focus on a 7 dividend fortresses that combine higher yields with more robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com