
How Earnings Beat Will Impact Itron Stock (ITRI)
- Itron reported past third quarter 2026 basic EPS from continuing operations of US$1.63 and diluted EPS of US$1.61, alongside updated guidance calling for fourth quarter revenue of US$621 million to US$636 million and full year revenue of US$2.37b to US$2.385b.
- Beyond the headline numbers, Itron is pairing earnings guidance with customer focused initiatives such as its SmartMark collaboration, which links grid edge intelligence with customer engagement to help utilities run more efficient and flexible networks.
- Next, the focus will be on how Itron's higher EPS and refreshed revenue guidance could influence the investment narrative around grid intelligence.
Scan beyond Itron and explore how other grid and energy infrastructure plays are lining up for potential breakouts with our curated 43 power grid technology and infrastructure stocks.
Itron Investment Narrative Recap
Itron appeals to shareholders who believe utilities will keep investing in smart meters, grid edge intelligence and resiliency software, and that the firm can convert its US$4.4b style pipeline into deployments despite choppy project timing. The latest quarter, with higher EPS and specific Q4 and full year revenue guidance, supports that execution narrative in the near term.
The key short term catalyst remains the pace of converting large Networked Solutions projects and software heavy contracts into revenue without eroding record gross margins near 40%. The biggest risk is still delays from regulators and affordability concerns, which could stretch timelines and make quarterly earnings more volatile, even with healthy backlog.
The SmartMark collaboration looks most relevant here because it ties directly into Itron's focus on grid edge intelligence and Outcomes. By pairing SmartMark's customer education expertise with Itron's grid data and analytics, utilities can better link what happens behind the meter with how the grid is run.
For investors, this matters because it targets one of Itron's clearest growth drivers: higher margin software and services that sit on top of deployed hardware. Success would lean into existing catalysts around recurring revenue and resiliency solutions, while still carrying execution risk if utilities slow program rollouts or interoperability work proves more complex than expected.
Itron's narrative projects US$2.7b revenue and US$339.3 million earnings by 2029. This aligns with analysts' assumption of 6.1% yearly revenue growth and implies an earnings increase of about US$65.3 million from US$274.0 million today.
Discover how Itron's fair value indicates a 37% potential upside to its current price, which could materialize faster than many investors expect.
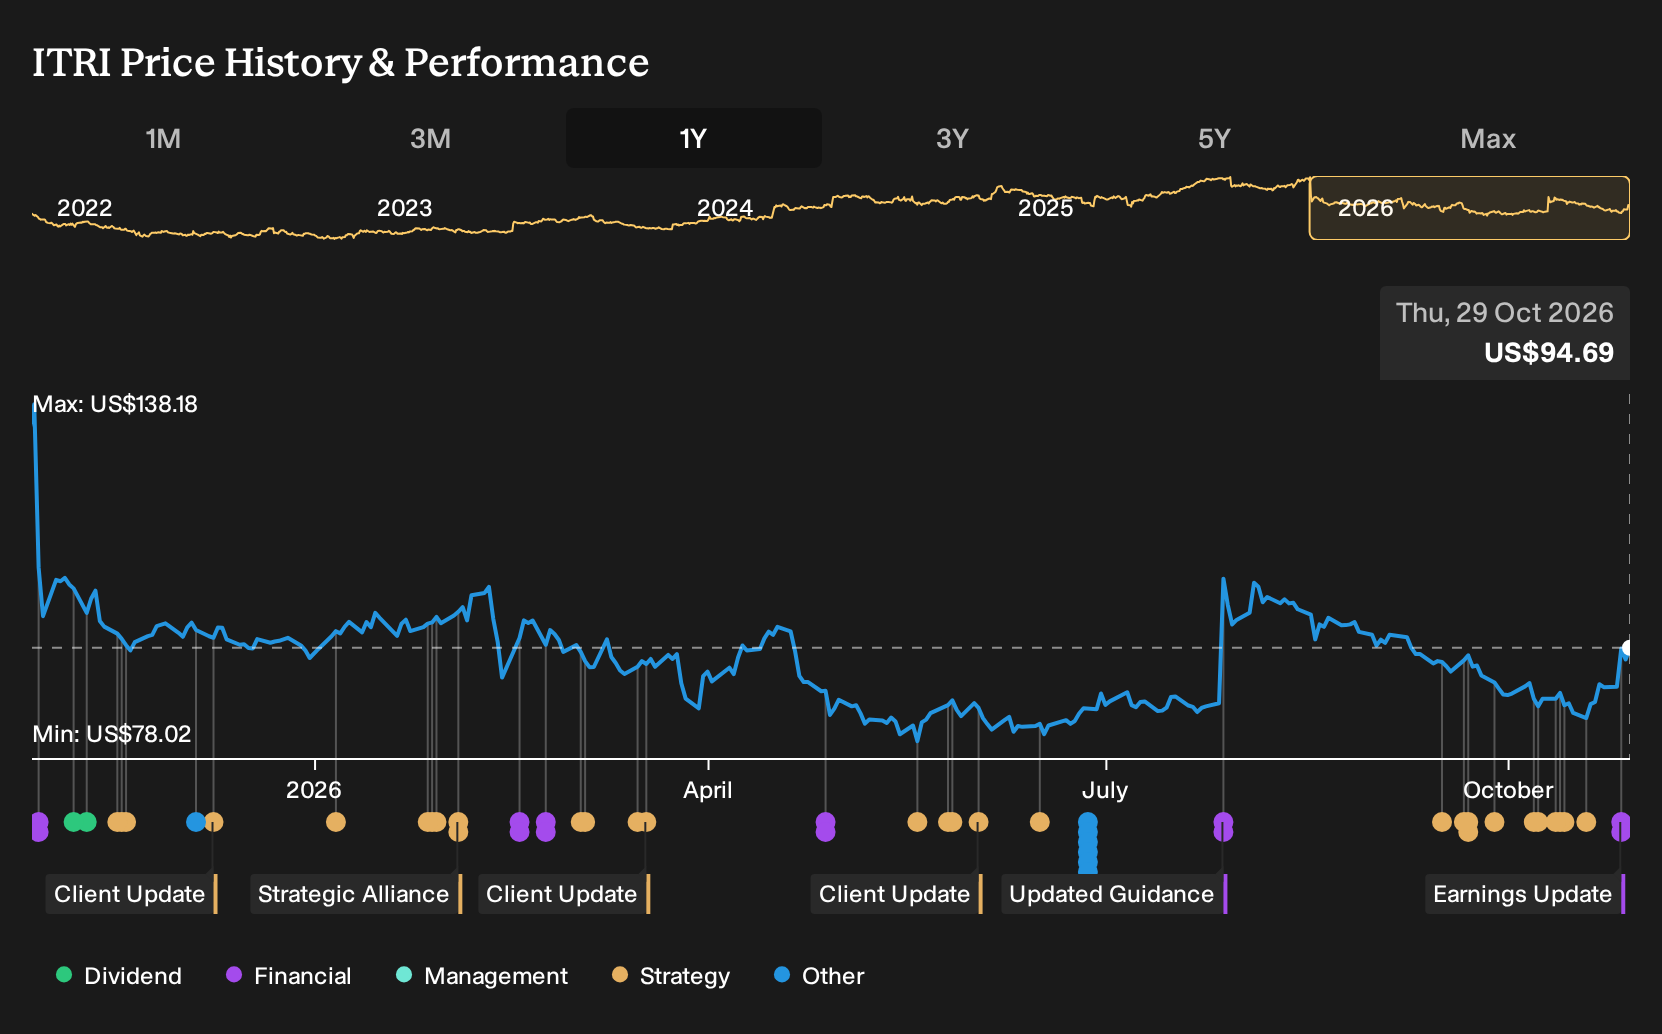
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$71.5 to US$129.6, so some members see Itron trading far below their forecasts while others are more restrained. These views were formed before the recent earnings and SmartMark news. Treat them as starting points and compare several opinions before leaning on any single narrative.
Explore 3 other Itron fair value estimates, including one that suggests potential upside of as much as 37% from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Itron research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Itron. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Itron's overall financial health at a glance.
Looking for more investment ideas beyond Itron?
If Itron has sharpened your interest in grid intelligence and earnings quality, broaden your watchlist with a few focused sets of opportunities built using the Simply Wall St Screener.
- Hunting for potential mispricing in quality companies, scan a curated 30 high quality undervalued stocks that combine stronger fundamentals with appealing valuations.
- If capital preservation comes first for you, start with a 30 resilient stocks with low risk scores that filters for businesses scoring well on stability and financial resilience.
- Prefer sturdier balance sheets before anything else, focus on a list of solid balance sheet and fundamentals (23 results) and see which companies pair robust finances with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com