
UBER Stock: Here’s What to Expect From Uber's Q3 Earnings Report
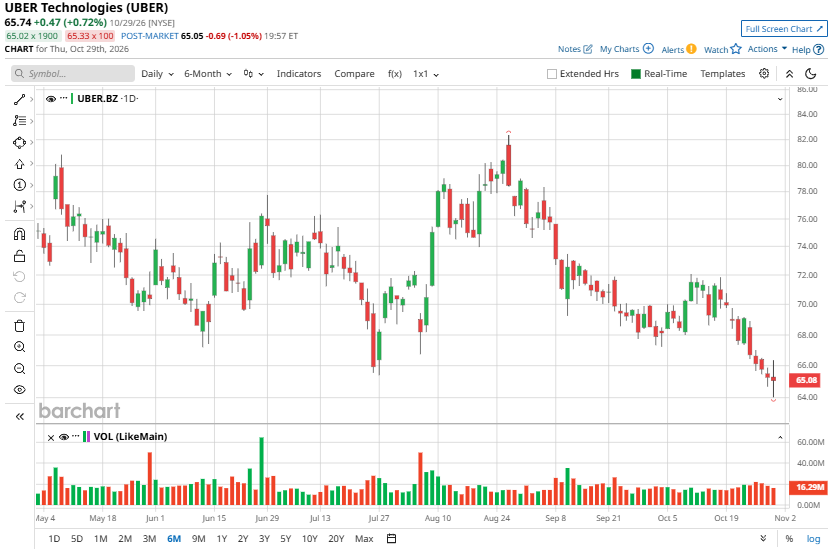
Uber (UBER) will release its third-quarter earnings on Wednesday, Nov. 4, 2026. So far, 2026 has been a terrible year for UBER stock investors. Shares are down about 20% year-to-date (YTD). While UBER has underperformed so far this year, it has consistently delivered strong revenue and EPS growth.
Momentum will likely continue in Q3. Uber is expected to post another quarter of solid growth, with its Mobility and Delivery businesses continuing to drive performance. As Uber scales operations and manages costs more efficiently, improved operating leverage could provide a solid boost to earnings.
Uber's Q3 Outlook
Uber is positioned to sustain healthy growth in the third quarter, supported by broad-based momentum across its Mobility, Delivery, and Freight businesses. However, geopolitical uncertainties, particularly the ongoing conflict in the Middle East, could weigh on overall performance in the near term.
Management expects Q3 Gross Bookings to reach $58.25-$60.25 billion, implying year-over-year (YoY) growth of 18%-22% on a constant-currency basis. The outlook reflects sustained momentum in Mobility, which delivered 20% Gross Bookings growth in Q2 alongside continued improvement in segment profitability.
The U.S. Mobility business is expected to remain a key growth driver, driven by increasing adoption across both premium and value-oriented offerings. Uber's continued penetration into less densely populated markets and reinvestment of insurance-related cost savings to enhance affordability will likely support trip volumes. Notably, suburban and lower-density markets are emerging as attractive growth avenues, with trip growth remaining solid and at favorable margins. This allows Uber to expand its addressable market while improving its profitability mix.
Growth across customer segments also remains encouraging. Value-oriented products are strengthening Uber's appeal among price-conscious consumers, while stable pricing and improved driver availability are supporting engagement across its core ride-hailing platform. At the higher end, premium offerings are contributing positively to the business mix and supporting margin expansion. Additionally, Uber for Business continues to demonstrate strong traction.
The Delivery segment is also expected to maintain its strong growth trajectory, following 25% YoY growth in Gross Bookings in Q2. Favorable demand trends, strong customer retention, increasing Uber One penetration, and continued expansion in Grocery & Retail (G&R) will support growth.
G&R remains a particularly attractive growth opportunity as Uber broadens its platform beyond restaurant delivery into everyday local commerce. The segment continues to outpace the core restaurant delivery business, benefiting from rising consumer adoption, an expanding product assortment, and ongoing platform innovation. Beyond contributing to Gross Bookings growth, the increasing scale of G&R could enhance customer engagement and create additional opportunities to leverage Uber's existing logistics network.
Meanwhile, Freight is showing signs of a meaningful recovery, with Q2 Gross Bookings growth accelerating to 25% YoY alongside healthy volume expansion. Sustained enterprise demand and deeper customer engagement should help preserve this momentum. Importantly, improving cross-selling opportunities augur well for growth.
From a profitability perspective, continued strength in Delivery and U.S. Mobility should support Q3 earnings, given their margin-accretive growth characteristics. An improving business mix and disciplined cost management will support its bottom line. Uber expects Q3 earnings to be $0.84 to $0.88 per share, representing YoY growth of 28%-35%. Overall, Uber is expected to sustain strong growth momentum in Q3.
Growth Story Remains Intact Despite UBER Stock's Weakness
Uber is expected to deliver another quarter of strong revenue and earnings growth, supported by sustained momentum across Mobility and Delivery, improving Freight trends, and disciplined cost management. Expanding operating leverage and a favorable business mix should further strengthen profitability. However, despite solid operating performance, Uber stock has underperformed so far this year, suggesting investor sentiment remains cautious.
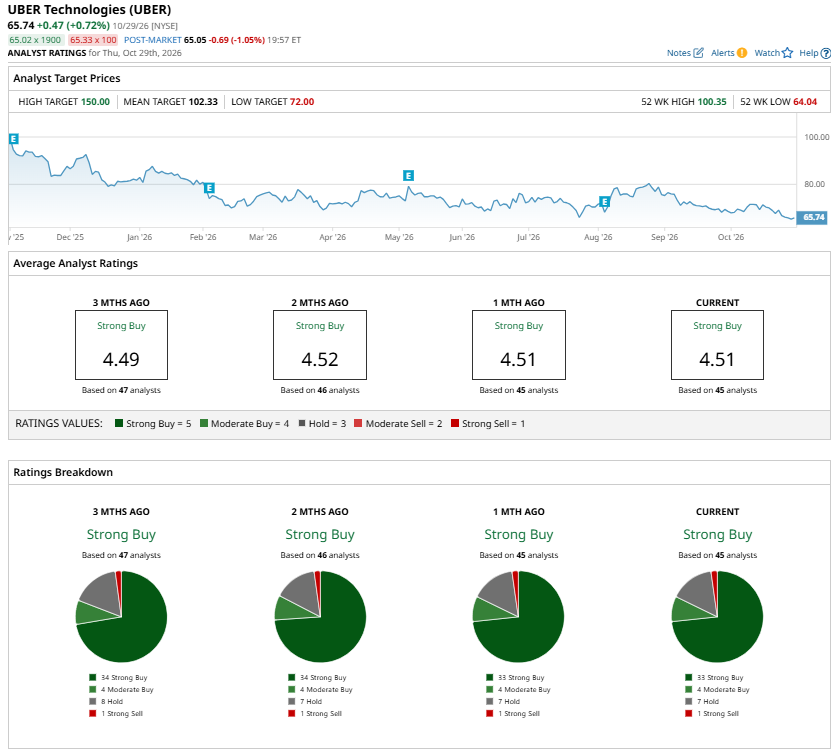
In contrast, analysts are bullish on UBER stock's prospects and maintain a “Strong Buy” consensus rating ahead of the Q3 earnings report.
On the date of publication, Amit Singh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.