
What Palfinger (WBAG:PAL)'s Profit Turned to Loss Means For Shareholders
- Palfinger reported nine-month 2026 sales of €1,616.67 million compared with €1,556.3 million a year earlier, but moved from €72.38 million net income to a €61.55 million net loss, with basic and diluted EPS from continuing operations shifting from €2.04 earnings to a €1.64 loss.
- The combination of higher sales and a sizeable net loss suggests rising costs, operational frictions or one-off charges are weighing on Palfinger's profitability despite top-line progress.
- This article will now look at how Palfinger's swing from profit to net loss could affect the investment narrative around Strategy 2030+.
Compare Palfinger's recent swing into a net loss with peers by scanning a curated shortlist of list of solid balance sheet and fundamentals (203 results) that may be handling earnings pressure differently.
Palfinger Investment Narrative Recap
For a shareholder in Palfinger, the core belief is that the Reach Higher Strategy 2030+ eventually translates the heavy capital spending and portfolio reshaping into steadier earnings. The recent nine month net loss challenges that idea in the short term, because it points to cost pressure and possible frictions in the industrial footprint while those projects are still being absorbed.
The immediate catalyst most investors will watch is execution on service and Marine, which previously carried higher margins and more recurring revenue. The biggest near term risk remains that soft demand in key regions, together with ongoing tariffs and a high debt load, limits how quickly profitability can recover from the current loss making period.
The most relevant disclosure for this discussion is the earnings announcement for the nine months to 30 September 2026. Sales of €1,616.67 million sit ahead of the prior year, yet Palfinger reported a €61.55 million net loss and a €1.64 basic and diluted loss per share from continuing operations, compared with earnings of €2.04 per share a year earlier.
That swing into the red keeps attention squarely on cost control, pricing power and any operational bottlenecks tied to Strategy 2030+ investments. For catalysts to matter, such as growth in North America or further Marine backlog conversion, the business first needs to show that higher volumes can again coexist with positive margins and support the balance sheet.
Palfinger's narrative projects €2.7b revenue and €161.7 million earnings by 2029. This assumes 4.7% yearly revenue growth and an earnings increase of about €67 million from €94.6 million today.
Uncover why Palfinger's fair value indicates a 47% potential upside to its current price, before enthusiasm around Palfinger's discount starts to fade.
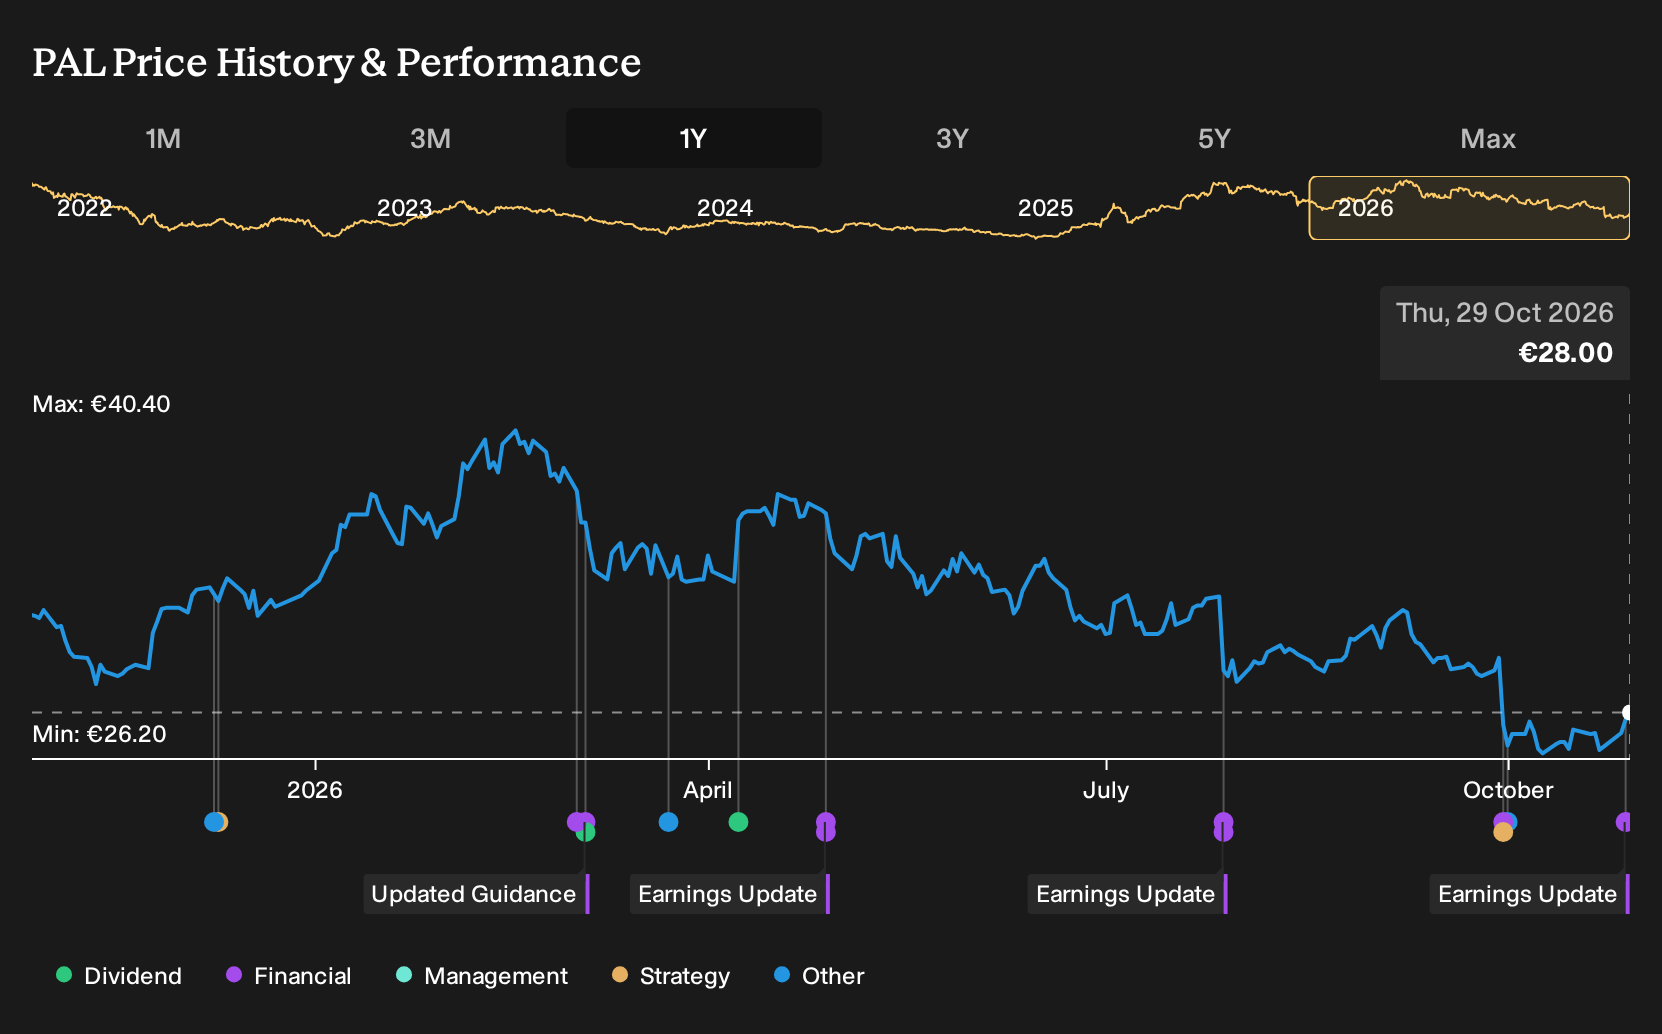
Exploring Other Perspectives
Some of the most optimistic analysts framed Palfinger around a different catalyst: a long infrastructure and reconstruction cycle in Europe, the U.S. and Ukraine that could, in their view, support revenue of about €2.8b and earnings near €200.2 million by 2029. Those pre earnings call forecasts are far from guaranteed and they may look very different once you and analysts reassess the fresh nine month loss.
Explore 4 other Palfinger fair value estimates, including one that suggests as much as 65% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Palfinger research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Palfinger. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Palfinger's overall financial health at a glance.
Looking for more investment ideas beyond Palfinger?
Once you have formed a view on Palfinger, it can help to widen the lens and compare it with other opportunities that suit different risk profiles and income goals.
- For investors who want potential bargains with solid fundamentals and fewer question marks on quality, scan our 200 high quality undervalued stocks, which already clear a high bar on cash flows and balance sheet strength.
- If capital preservation and a smoother ride matter more to you than big swings, filter for 220 resilient stocks with low risk scores, which score well on resilience and financial robustness.
- When you want to get ahead of the crowd and research companies that the wider market may not be focusing on yet, comb through our 605 high quality undiscovered gems with strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com