
What Is Behind New Oriental Education & Technology Group (EDU) Stock's Latest Drop?
New Oriental Education & Technology Group (EDU) just packed earnings, a dividend increase, fresh guidance, and a completed buyback into one announcement, giving investors several moving pieces to weigh at once.
The sharp 16.3% decline in the 7 day share price, including a 3.2% drop to US$49.09 on the latest close, shows investors reacting to the earnings mix and margin pressure. This comes even though the 5 year total shareholder return of about 150% still reflects a strong longer run outcome.
Pursue other education and consumer-focused plays reacting sharply to earnings and guidance shocks by scanning our curated list of 18 high quality undiscovered gems alongside New Oriental Education & Technology Group.New Oriental Education & Technology Group now trades well below both its internal value estimate and the average analyst target after this pullback. Is that a genuine mispricing, or a fair warning label on margin risk?
Most Popular Narrative: 13.1% Undervalued
On the most followed view, New Oriental Education & Technology Group screens as undervalued, with a Fair Value of $56.50 against a $49.09 last close. This puts the spotlight firmly on whether its spending plans can really support that gap.
Even as new educational initiatives such as non academic tutoring and intelligent learning devices report strong recent revenue growth, sustained high investment needs in these areas combined with only partial monetization through the New Oriental Home ecosystem could stretch payback periods and keep group level operating and net margins below what the current growth narrative implies.
See why 1 investors see New Oriental Education & Technology Group as 13% undervalued.
Result: Fair Value of $56.50 (UNDERVALUED)
Still, two things could flip that script fast: cost savings from restructuring and AI tools lifting margins, and New Oriental Home engagement strengthening revenue quality.
Find out about the key risks to this New Oriental Education & Technology Group narrative.
Another View: How New Oriental Education & Technology Group Looks On Earnings
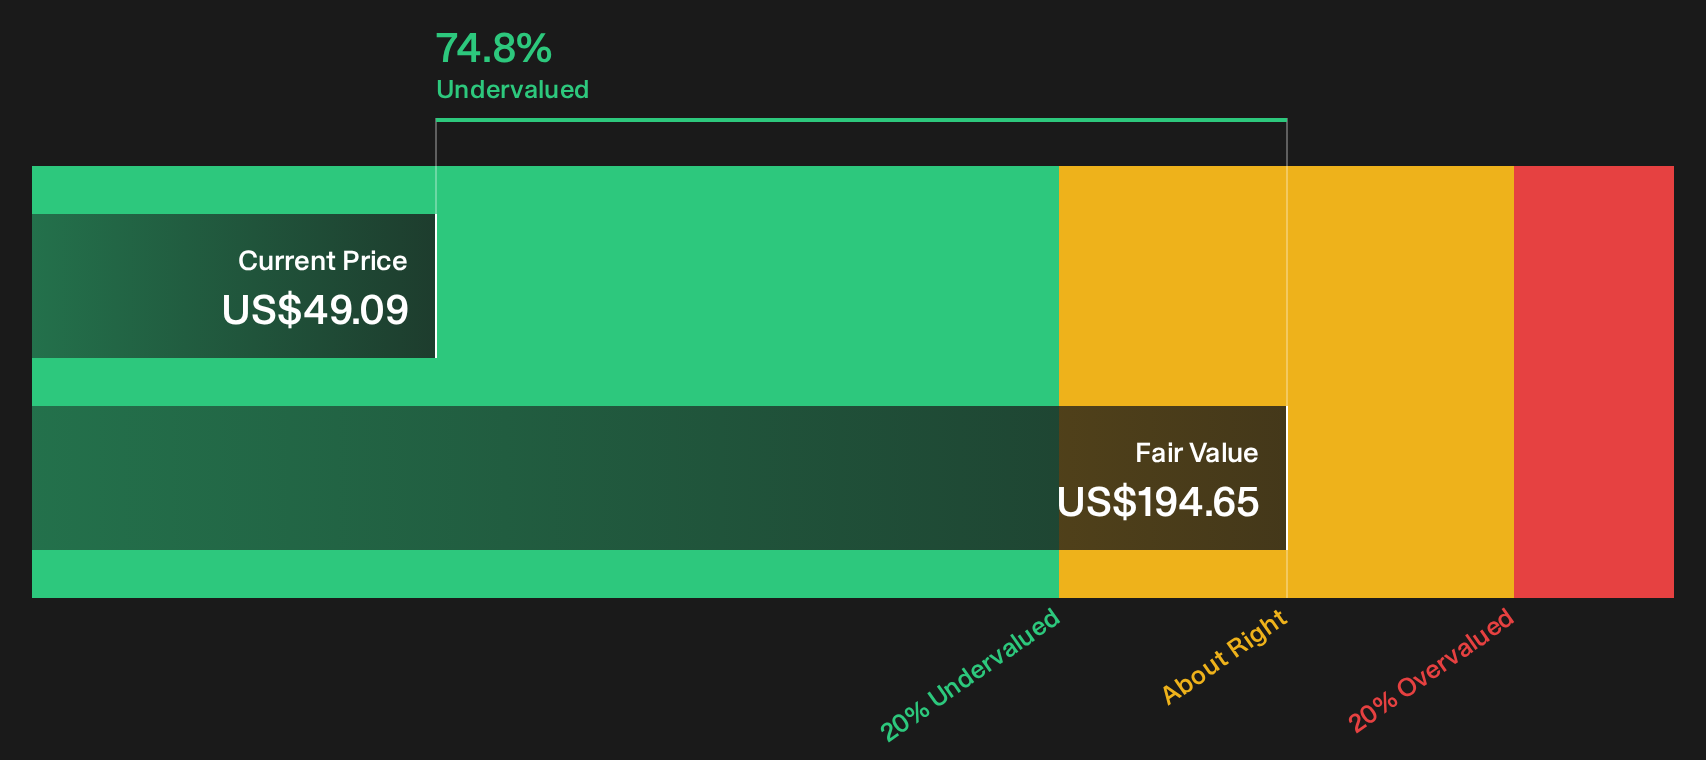
There is a wrinkle. While the SWS DCF model flags New Oriental Education & Technology Group as good value on long term cash flows at $194.65 versus a $49.09 share price, that result leans heavily on long dated assumptions that can move quickly if margins or reinvestment plans shift.
Some investors prefer to start with how that DCF is actually built before trusting such a large implied gap. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed reactions like this rarely stay neutral for long. Move quickly, look through the data yourself, and weigh the 4 key rewards and 1 important warning sign.
Looking For More Ideas Beyond New Oriental Education & Technology Group?
If you stop with New Oriental Education & Technology Group, you risk missing other compelling setups. Cast the net wider and let the data surface fresh candidates.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (23 results), which can help anchor your portfolio when sentiment swings.
- Spot potential mispricings early by running through the 30 high quality undervalued stocks, which highlights companies where fundamentals and current prices tell two very different stories.
- Prioritise sleep at night holdings with the 30 resilient stocks with low risk scores, which focuses on businesses with more stable risk profiles and fewer financial red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com