
Is Byline Bancorp (BY) Undervalued On Strong Q3 Results And New Guidance?
Byline Bancorp (BY) drew fresh attention after issuing fourth quarter 2026 net interest income guidance of US$103 million to US$105 million, following its third quarter earnings release and updates on dividends, buybacks, and credit charge offs.
At a share price of US$38.96, Byline Bancorp has logged a 1-day share price return of 0.75% and a 7-day share price return of 2.55%, with recent attention likely tied to the third quarter earnings beat, new net interest income guidance, the confirmed dividend and the completed buyback tranche. Despite some cooling over the past 90 days, where the share price slipped 0.79%, a 34.16% year to date share price return alongside a 47.52% 1-year total shareholder return and 108.02% 3-year total shareholder return points to momentum that has been building over a longer horizon rather than fading.
Spot 30 high quality undervalued stocks that share Byline Bancorp's mix of earnings momentum, shareholder returns, and balance sheet focus.After Byline Bancorp's strong run and fresh guidance, the question is simple: Does paying up today for that momentum make more sense than waiting for a cheaper entry that may never arrive?
Most Popular Narrative: 10% Undervalued
Byline Bancorp's most followed valuation story pegs fair value at $43.20, which sits above the latest close of $38.96 and frames the current enthusiasm as rooted in operating execution rather than pure sentiment.
The successful integration of First Security, including immediate cost synergies and system upgrades, has expanded Byline Bancorp's lending and deposit base while improving operational efficiency. This is presented as setting the stage for higher net interest income and improved net margins going forward. Byline's continued investment in digital banking upgrades, highlighted by recent enhancements to online platforms and payments capabilities, is described as a factor that is expected to attract and retain more relationship deposits while supporting fee based services, which can lift revenue and support operating margins.
See why 0 investors see Byline Bancorp as 10% undervalued.
Result: Fair Value of $43.20 (UNDERVALUED)
Still, the narrative around Byline Bancorp can break if a tougher Chicago and Midwest loan market squeezes spreads, or if post US$10b regulatory costs climb faster than modeled.
Find out about the key risks to this Byline Bancorp narrative.
Another View: What Byline Bancorp's P/E Is Really Saying
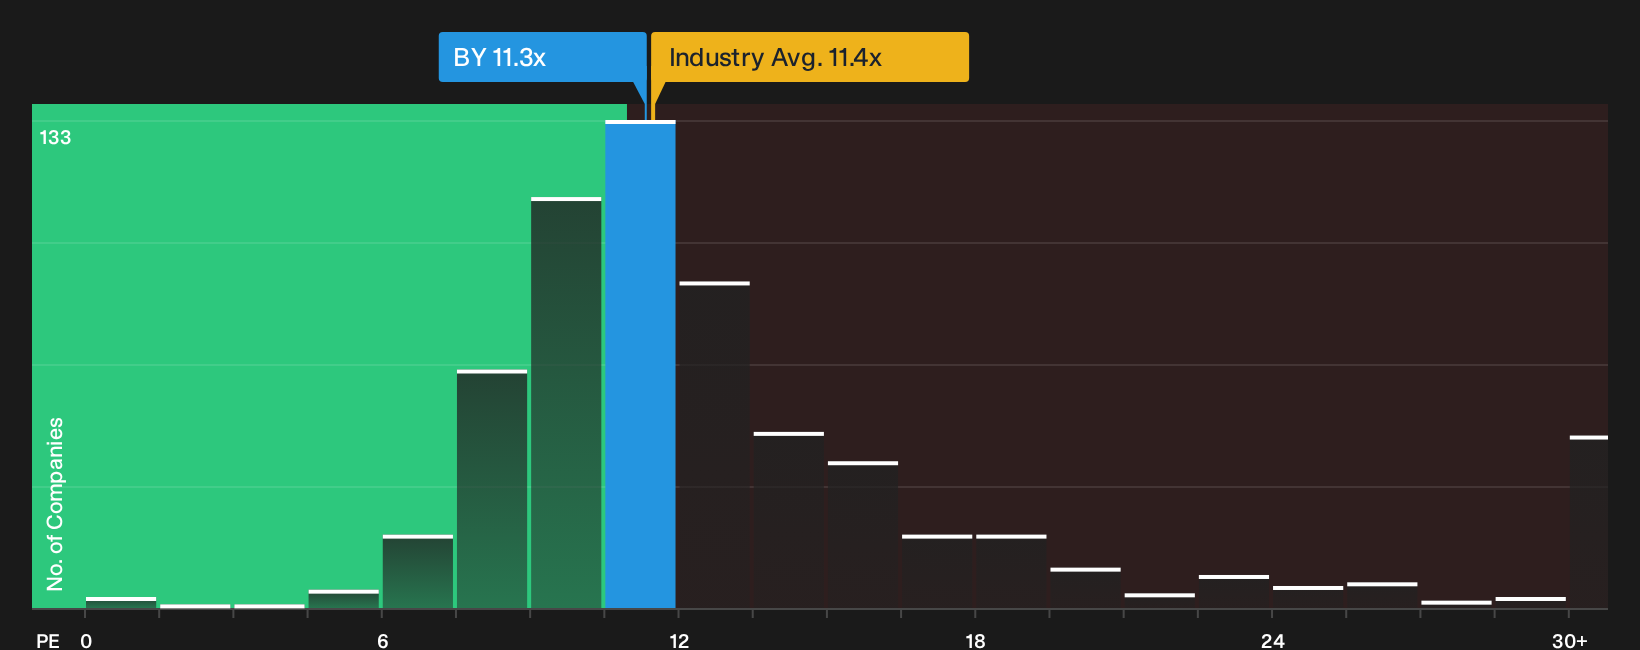
There is a different lens on Byline Bancorp once the focus shifts from fair value models to the simple P/E math. At 11.3x earnings, the stock sits almost in line with the US Banks industry on 11.4x, is much cheaper than peers at 18.9x, yet is still a touch above its own fair ratio of 10.7x. That mix suggests there could be room for the market to move either toward peer pricing or back to the fair ratio, so which way do you think it travels first?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mix of optimism and caution around Byline Bancorp is clear. Review the data promptly and use the 3 key rewards and 1 important warning sign to shape your own view.
Looking for more investment ideas beyond Byline Bancorp?
If you only stop at Byline Bancorp, you risk missing out on other opportunities that match your own risk, income, and quality preferences.
- Target resilient income by reviewing companies in the 7 dividend fortresses that may align with your need for yield and payout consistency.
- Hunt for potential mispriced opportunities through the 18 high quality undiscovered gems that focus on quality fundamentals with less crowd attention.
- Dial back portfolio risk by scanning the 30 resilient stocks with low risk scores that filter for sturdier balance sheets and calmer price moves.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com