
WEC Energy Group (WEC) Lifted Its 2026 Guidance, Is The Upside Already Priced In?
Why WEC Energy Group’s latest guidance move matters
WEC Energy Group (WEC) just paired strong third quarter results with a higher 2026 earnings guidance range and a larger capital plan tied to power hungry data center customers.
That guidance bump landed alongside a sharp move in the share price, with a 1 day share price return of 3.74% and a 1 month share price return of 11.75%. This suggests investors are re-pricing WEC Energy Group as the higher 2026 earnings range, stronger third quarter results and expanded capital plan tied to data center demand feed into expectations. Momentum has picked up recently. However, the 1 year total shareholder return of 5.28% and 5 year total shareholder return of 51.53% show a steadier long haul story rather than a sudden breakout.
Scan how WEC Energy Group's guidance move compares with other regulated utilities being re-rated on infrastructure and data center demand by reviewing the curated 43 power grid technology and infrastructure stocks
After a near $115 share price and fresh guidance in hand, the gap between where analysts, intrinsic value models and the market place WEC Energy Group is now sets up the key issue. Where does fair value really land after this move?
Most Popular Narrative: 4% Undervalued
Against the last close at $114.63, the most followed narrative pegs fair value for WEC Energy Group at about $118.91. This frames the latest guidance upgrade as part of a slowly tightening valuation gap rather than a stretched move.
The planned US$37.5b capital program from 2026 to 2030, focused on regulated gas infrastructure, renewables, storage and transmission, is expected to expand WEC Energy Group’s regulated asset base and drive higher revenue and net income as these assets are placed in service.
The Very Large Customer tariff in Wisconsin, with its defined return on equity of 10.48% to 10.98% and 57% equity layer, creates a framework for future large load projects that can add to regulated earnings and support margin stability as more data center infrastructure is built.
See why 15 investors see WEC Energy Group as 4% undervalued.
Result: Fair Value of $118.91 (UNDERVALUED)
Still, the narrative around WEC Energy Group can shift quickly if regulatory pushback in Wisconsin or execution hiccups on major projects slow approvals or compress allowed returns.
Find out about the key risks to this WEC Energy Group narrative.
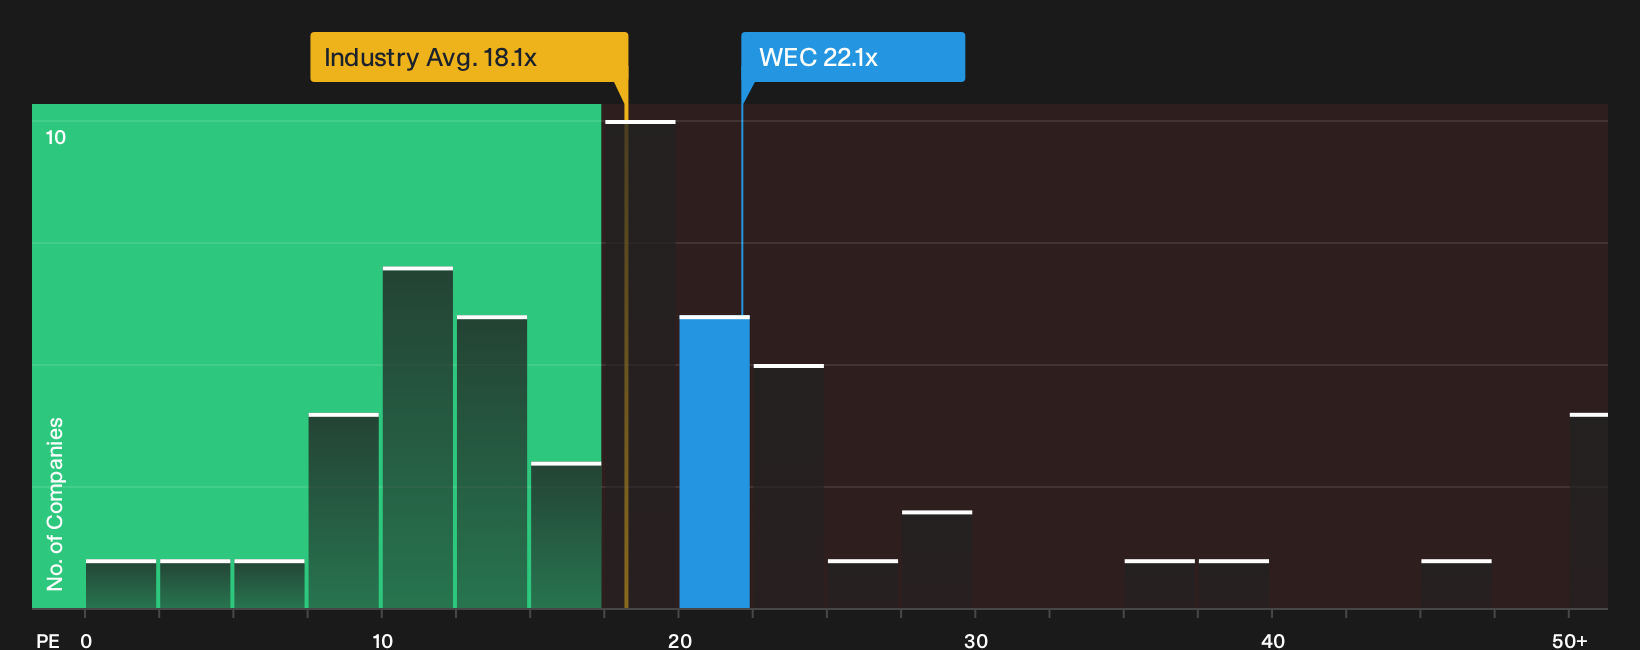
Another View: What WEC Energy Group’s P/E Is Saying
Analyst narratives frame WEC Energy Group as about 4% undervalued at $118.91, yet the current P/E of 22.1x tells a different story. That ratio sits above the global Integrated Utilities industry at 18x, the peer average at 19.6x, and the 20.8x fair ratio.
This premium points to less room for error and more valuation risk if earnings, regulation or data center demand fall short. The share price already reflects a richer multiple than what the market could move toward, so the key question is whether that extra P/E is truly earned.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings on WEC Energy Group after this guidance shift. If you want to move fast and base your stance on the underlying data rather than headlines alone, start by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond WEC Energy Group?
If WEC Energy Group has your attention, do not stop here. Broaden your watchlist, compare different return profiles, and pressure test your convictions across sectors.
- Target fresh upside potential by scanning a focused group of underappreciated businesses through the 30 high quality undervalued stocks.
- Prioritize stability and income by reviewing steady-paying companies in the 7 dividend fortresses.
- Stack your watchlist with financially resilient operators that aim to limit downside risk using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com