
Top 3 Australian Dividend Stocks To Watch In October 2026
Australian income investors are watching rising global interest rates closely as bond yields climb and cash looks more tempting. That shift is putting fresh focus on local companies that pay steady dividends above 3% and have room to keep those payouts going. This article breaks down three high-yield Australian stocks from a quality-focused dividend screen that aims to filter for solid coverage, consistency and dependable income.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher yielding dividend payers with a focus on coverage, growth and stability. However, if you want the strongest names, these 4 dividend aristocrats stocks are at the top of the list.
Medibank Private (ASX:MPL)
Medibank Private is a major Australian health insurer that turns recurring policy premiums into the kind of cash flows income seekers look for. Its Health Insurance arm produces about A$8.6b of the group’s roughly A$9.3b in segment revenue, and the company is valued around A$13.8b.
Medibank Private’s Health Insurance engine, supported by growing health services, anchors its appeal for investors who want dividend income backed by recurring premiums and disciplined cost control.
"The expansion and scaling of Medibank Private’s primary care clinics, virtual health and in home care services, including more than A$500m invested over a decade and increasing volumes of GP consults and acute home visits that reduce hospital bed days, is expected to support revenue growth in Medibank Health and help contain claims costs in the insurance book, which can be positive for net margins."
What happens to dividend strength if a single pressure point in those underlying economics starts to shift against expectations?
If that margin pressure is what worries you most, the full narrative for Medibank Private explains how Medibank Private’s cash engine, regulation and capital choices interact beneath the headline dividend.

BHP Group (ASX:BHP)
BHP Group is a global resources giant built around iron ore, copper and coal, and it earns its place in the Dividend Powerhouses screen through cash-rich iron ore and copper operations that help fund a dividend yield above 3% from A$29.2b copper, A$23.9b iron ore and A$5.6b coal revenue on a A$292.4b market value.
BHP Group brings something different to this dividend list, because its ability to keep paying out relies on long life mining assets that turn commodity demand into steady cash rather than on slow moving utilities or banks.
"A strong pipeline of copper and potash projects positions BHP Group to benefit from a global surge in decarbonization efforts and electrification initiatives, with rising demand for critical minerals expected to influence future revenues."
What matters next for dividend investors is how one unresolved production and project pressure shapes the cash left over for future payouts.
That payout question depends on one thing, and the full narrative for BHP Group shows how BHP Group’s copper and potash pipeline could accelerate or quietly cap the dividend story.

Commonwealth Bank of Australia (ASX:CBA)
Commonwealth Bank of Australia leans on its retail and business banking engine to generate the stable, cash-rich earnings that underpin a 3%+ dividend profile, making it a heavyweight income play in this screen rather than just another large financial stock.
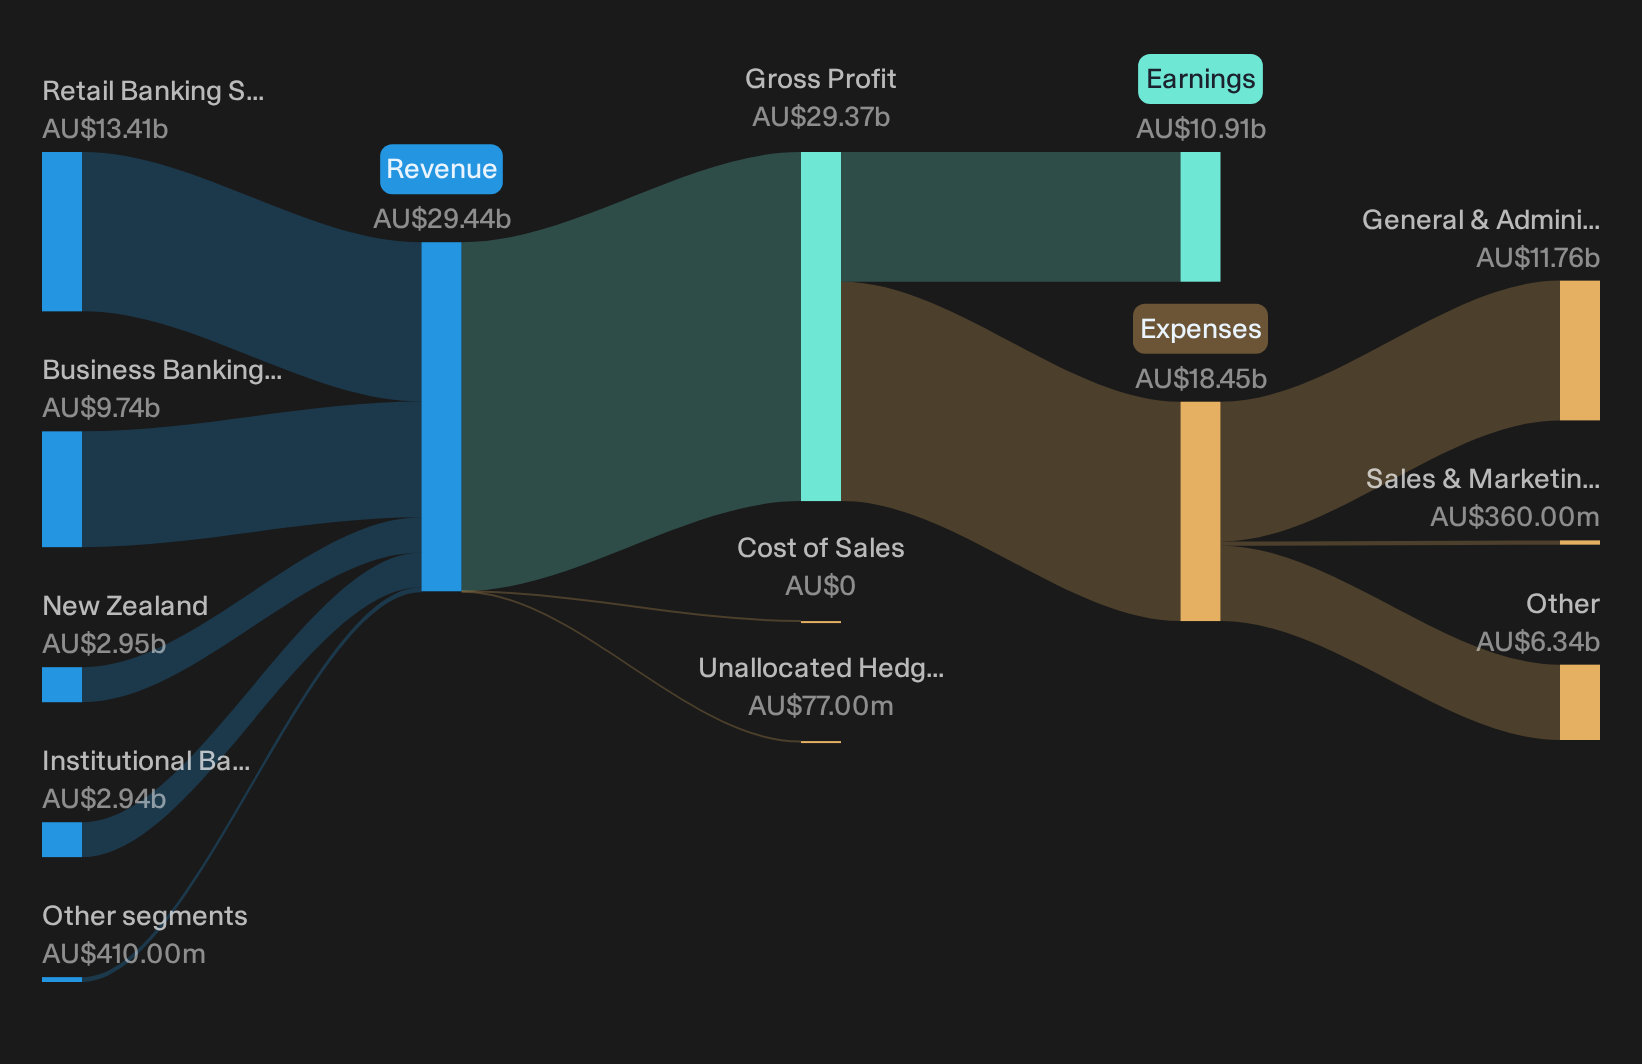
Commonwealth Bank of Australia runs a broad banking and financial services platform, with Retail Banking Services including Bankwest generating about A$13.4b of revenue, Business Banking A$9.7b and New Zealand A$3.0b, supporting a market value of roughly A$278.2b.
For income focused investors, the interest and fee streams from Commonwealth Bank of Australia’s everyday loans and deposits are what make the dividend feel dependable, even as the banking model is reshaped by technology, pricing pressure and rising investment in systems.
"Growing competitive intensity in digital payments and deposit products, as fintechs and digital-first rivals target Commonwealth Bank of Australia’s core profit pools, could pressure net interest margins and fee income if deposit pricing and transaction fees are forced lower."
The strength of those dividend friendly earnings hinges on how one slow burning cost and technology trade off ultimately filters through to margins.
That margin trade off is exactly what the full narrative for Commonwealth Bank of Australia unpacks, revealing how Commonwealth Bank of Australia could turn tech spending into accelerating earnings power.
Seeking Fresh Alternatives Before Others?
Fresh ideas move first, and the strongest opportunities can be caught before momentum is obvious. Scan new themes while they are still under the radar for now and act now.
- Spot early breakouts in critical materials and ride structural demand shifts with curated 17 top copper producer stocks that screen for scale, resilience and meaningful production footprints.
- Target resilient income payers while yields are still elevated by focusing on a hand picked 4 dividend fortresses that balance payout strength with balance sheet support.
- Position ahead of infrastructure upgrades by zeroing in on 43 power grid technology and infrastructure stocks chosen for grid modernisation, electrification exposure and capital discipline.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com