
General Mills (GIS) Stock Trades Close To Its Sales Value
General Mills has seen its share price slide in recent years, which naturally puts the spotlight on what investors are paying for each dollar of its sales. With the stock under pressure, the question is whether the current market value still lines up with the revenue base of this packaged food giant.
- Over the past 3 years the share price has fallen 41.7%, which puts extra weight on whether the current valuation can be supported by its sales profile.
- The business model leans on large-scale branded food franchises, so long term sales resilience and pricing power may support how much investors are willing to pay for each unit of revenue.
- Your read on General Mills is one view; the desks covering it have another. See what analysts think General Mills's shares could be worth.
The stock's next move may depend on whether General Mills' current price is well supported by its sales and the multiple investors are assigning to that revenue stream.
If you are considering whether General Mills' slide is justified by its sales, it can help to ask the same question across 30 high quality undervalued stocks.
Where Does General Mills Sit on Sales?
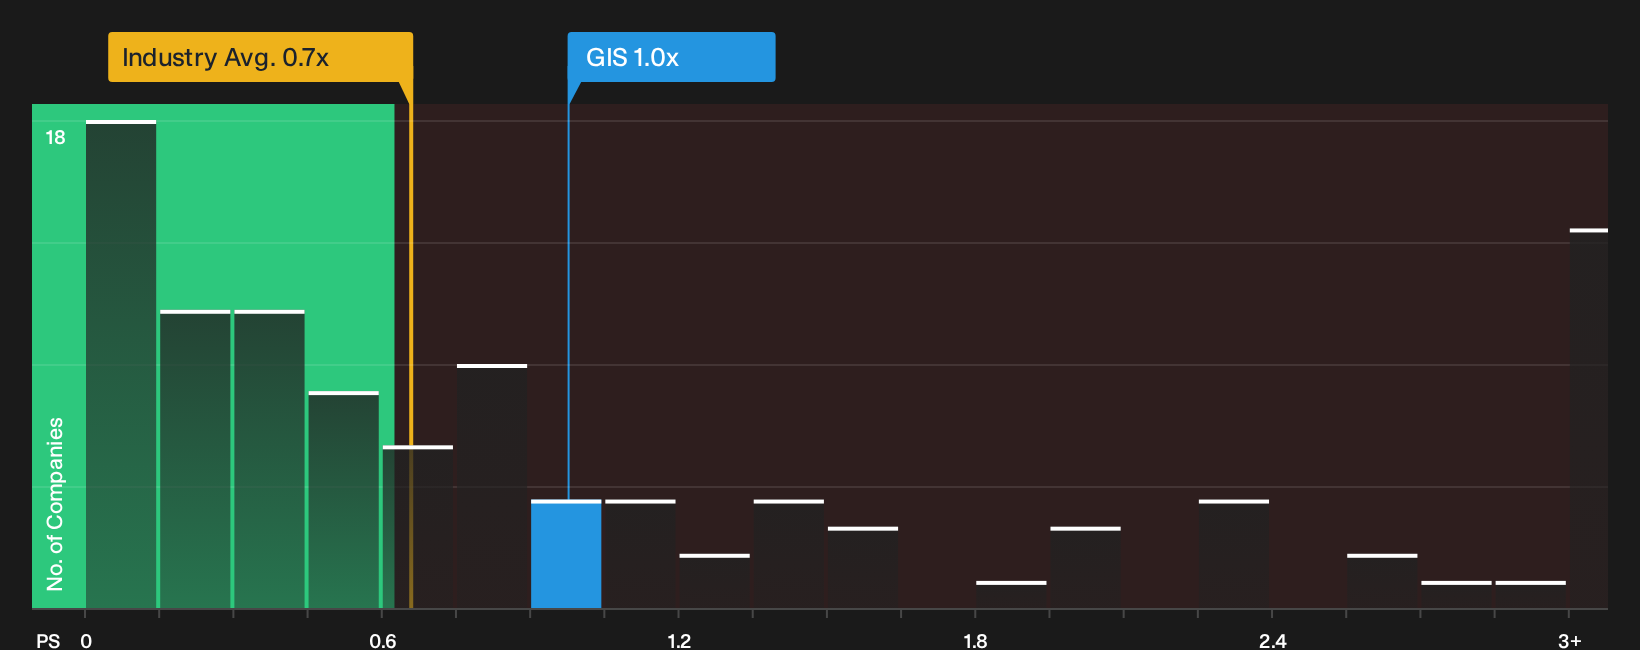
P/S is often a useful yardstick for a packaged food group like General Mills because revenue tends to be relatively steady and easier to compare across peers than earnings that can swing with costs. General Mills currently trades on a P/S ratio of 1.0x, set against an industry average of about 0.7x for Food companies.
Peers focused on similar categories are on roughly 1.2x P/S, while the model based fair P/S multiple for General Mills is slightly above the current figure. That fair yardstick folds in factors like the group’s margins, size and risk profile, so the present 1.0x reading sits modestly below what that tailored benchmark implies. For an investor weighing the recent share price slide against the sales base, the current P/S level suggests the market is not paying a premium for General Mills' revenue but is also not marking it down aggressively relative to comparable packaged food businesses. Explore the numbers behind General Mills's P/S valuation.
The General Mills Narrative: What Would Justify Today's Price?
Narratives for General Mills pick up where the P/S puzzle leaves off by spelling out which paths for future sales, margins and earnings would need to play out for the stock to look meaningfully higher or lower than today’s price. Each scenario is framed as a clear, testable view on General Mills' business that you can track over time, and they live on Simply Wall St's Community page.
Community views on General Mills split between cost savings supporting a steadier story and spending and complexity keeping pressure on the shares.
Bull case: 12% undervalued
"General Mills plans to deliver US$750 million of cost savings in fiscal 2027 as part of a US$3 billion program through fiscal 2030, which could support net margins and earnings..."
Discover why this Narrative puts General Mills at 12% undervalued.
Bear case: 11% overvalued
"The heavy emphasis on remarkability investments, including a double digit increase in media spend and higher SG&A, risks locking General Mills into structurally higher overhead at a time when adjusted operating profit is down 20% in Q2 and 19% in the first half..."
Explore why this Narrative puts General Mills at 11% overvalued.
One more angle on General Mills that is easy to overlook
Price tells you what the market thinks today, but the projections from sector specialists sketch out where they expect this business to be a few years from now, and that comparison can be revealing. Explore where analysts expect General Mills to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com