
Keysight Technologies (KEYS) Could Be 20% Undervalued On AI And Satellite Testing Optimism
Keysight’s satellite testing win and AI exposure draw investor focus
Keysight Technologies (KEYS) is back on investor radars after Korea Testing Laboratory selected its non terrestrial network test platform, while fund commentary has highlighted the company’s role in AI data centers and advanced chips.
Keysight Technologies has seen mixed recent momentum, with the share price down 8.54% over the past month but up 5.88% over the last week and showing a 59.66% year to date share price return at a last close of US$329.84. Long term total shareholder returns of 88.08% over one year and 167.73% over three years hint that investors are rewarding its role in AI infrastructure and satellite testing as perceptions of future growth potential improve.
Spot 54 AI infrastructure stocks that, like Keysight Technologies, are tied into AI data centers and next generation connectivity build outs.After a near 60% year to date climb and a recent pullback, Keysight Technologies forces a choice. Is this a reasonable entry after the run, or is patience on price the better bet as the valuation picture comes into focus?
Most Popular Narrative: 20% Undervalued
On the most followed view of Keysight Technologies, a fair value of $415.08 versus a last close of $329.84 suggests investors are not fully paying for the business yet, even after a strong run. That gap is built on expectations that AI data center demand, advanced wireless testing and software mix all keep pulling more weight in the income statement.
Expansion of software, simulation and recurring service offerings is advancing, with software and services reaching roughly 33% of Q3 2026 revenue, annual recurring revenue at 24% of mix and the simulation business expected to exceed US$0.5b in 2026. This supports high gross margins near the upper 60s percentage range and contributes to operating margin strength.
See why 20 investors see Keysight Technologies as 21% undervalued.
Result: Fair Value of $415.08 (UNDERVALUED)
Still, the bullish Keysight Technologies story can crack if supply constraints persist or if the Spirent integration delivers fewer cost synergies than analysts anticipate.
Find out about the key risks to this Keysight Technologies narrative.
Another View: What Keysight’s P/E Is Telling You
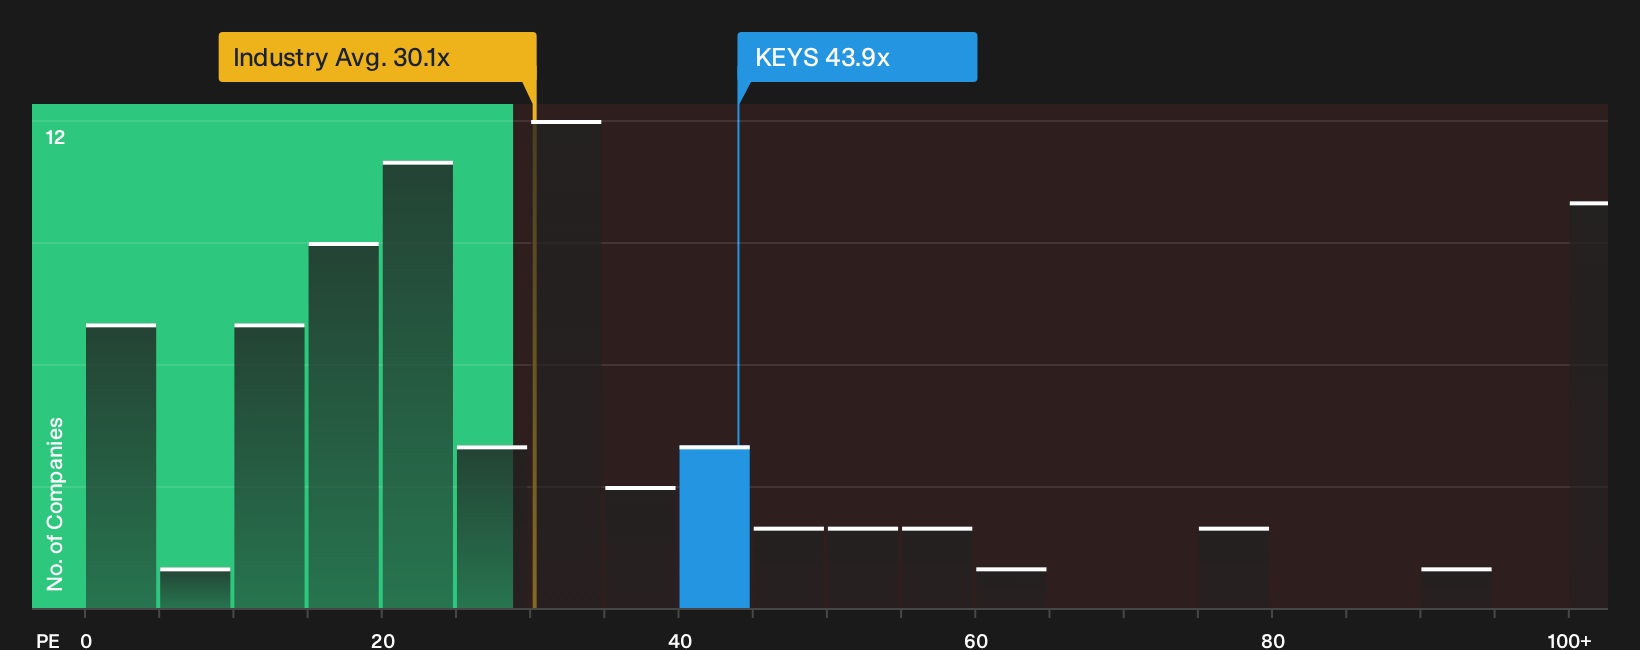
The earlier fair value work suggests Keysight Technologies trades about 11.9% below an intrinsic estimate, which supports the undervalued label. Yet the market is pricing the stock on a P/E of 43.9x versus a fair ratio of 35.3x and a US Electronic industry average of 30.1x, which points to a rich entry multiple and higher valuation risk if expectations ease.
If you lean on this P/E comparison, the question becomes simple. Is Keysight’s AI and testing exposure strong enough in your view to justify paying well above both peers and that fair ratio, or is it better treated as a sign to be more price sensitive on any next move?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on valuation and expectations can pull opinions in both directions, so consider acting promptly, review the data for yourself and weigh up the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Keysight Technologies?
If Keysight Technologies has sharpened your interest, do not stop here. Broader idea hunting with a structured screener often surfaces opportunities you would otherwise miss.
- Target potential mispricings by scanning a curated 30 high quality undervalued stocks that already combine quality fundamentals with room for the market to catch up.
- Zero in on resilience by reviewing a list of solid balance sheet and fundamentals (23 results) that can better handle shocks and still support long term compounding.
- Get ahead of the herd by tracking 18 high quality undiscovered gems that have strong numbers yet attract far less attention from the crowd.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com