
Keyence (TSE:6861) Stock Cools After Q2 Earnings Strength Fuels Valuation Debate
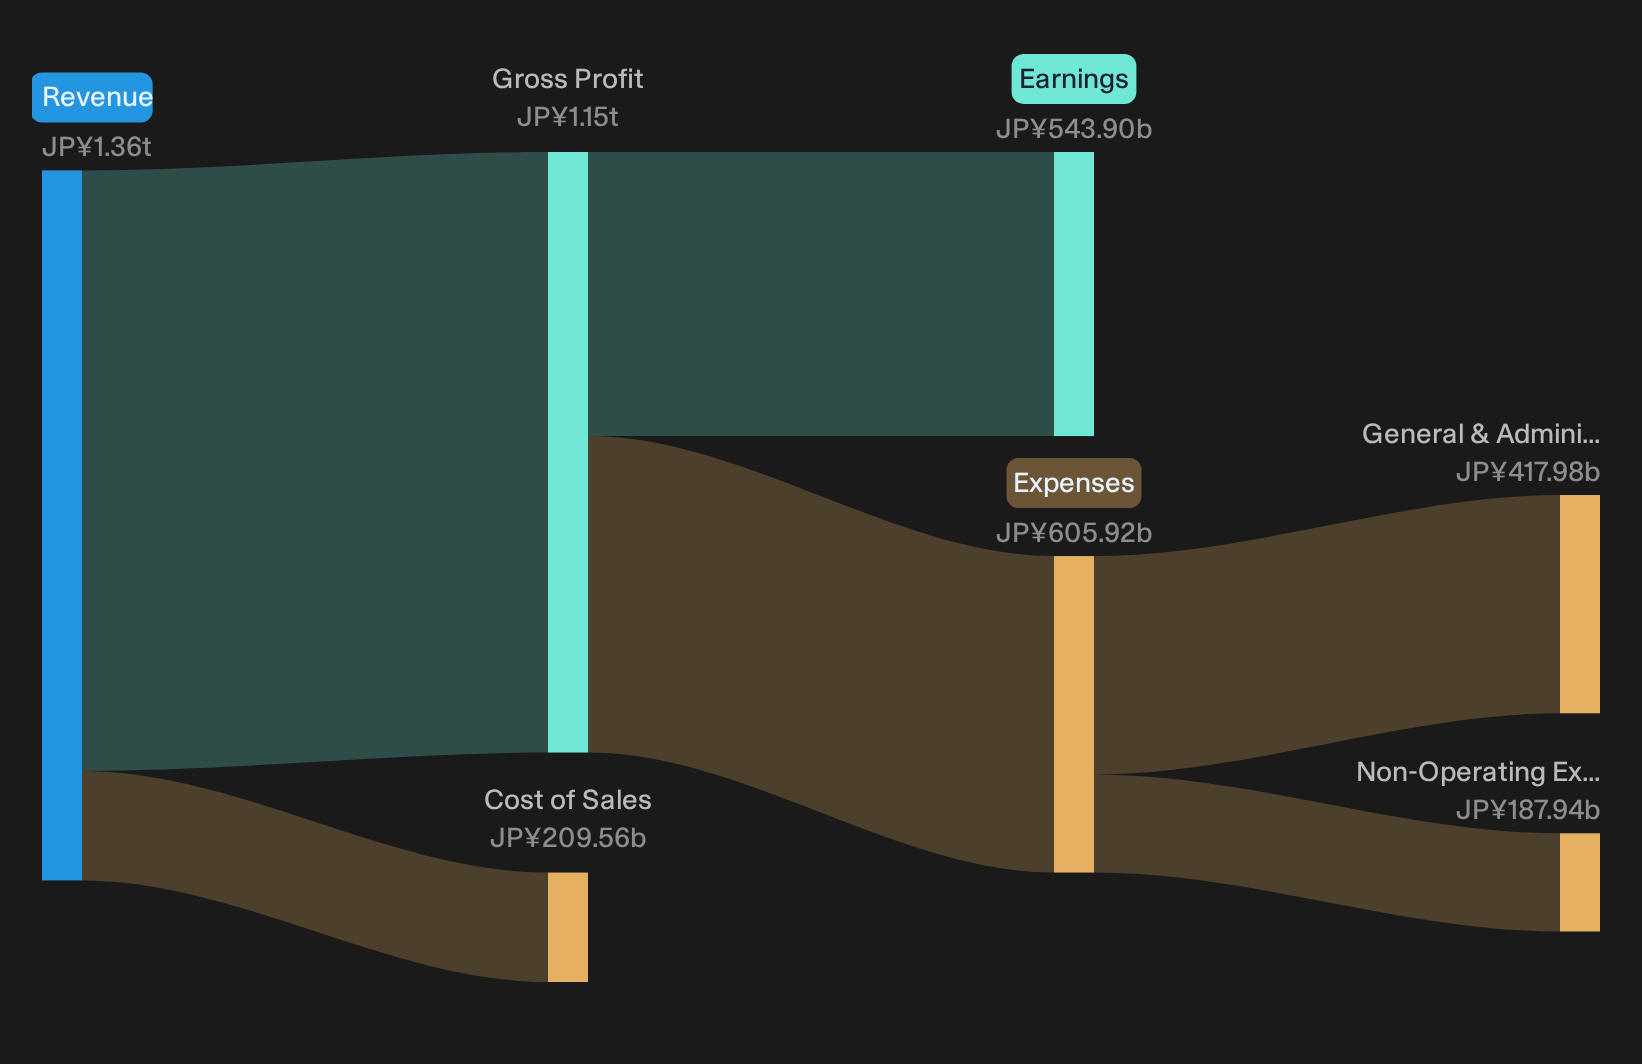
Keyence stock closed at ¥78,000 today, capping a month where the share price slipped about 3% even as fresh Q2 2027 earnings painted a very different picture. The automation specialist just posted quarterly revenue of ¥388,778m and basic earnings per share of ¥657.84, with trailing net profit margin near 40%. In the short term, the market is cool on a premium multiple near 34.8x P/E. For investors with a longer horizon, forecasts that point to mid to high single digit annual earnings and revenue growth keep the valuation question front and center for anyone thinking beyond this quarter.
Love Keyence’s near 40% net margin but uneasy about paying roughly 35x earnings for it? Screen for automation and industrial stocks that pair strong profitability with more modest valuations in the 15 high quality undervalued stocks.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥388,778m vs. ¥284,224m (up 36.8%)
- Net Income (Q2 2027 vs Q2 2026): ¥159,542m vs. ¥107,843m (up 47.9%)
- Basic EPS (Q2 2027 vs Q2 2026): ¥657.84 per share vs. ¥444.67 per share (up 47.9%)
- Net Profit Margin (TTM vs prior year): 40.0% vs. 37.6% (improved by 2.4 percentage points)
Earnings are up, but Keyence trades far above peers. Ask Charlie what makes Keyence worth such a rich multiple.
Keyence earnings lean toward the bullish script
For anyone leaning positive on Keyence, these numbers help your case. Revenue of ¥388,778m and net income of ¥159,542m are both well ahead of the prior year period, and net margin near 40% suggests the business still turns a large slice of each sales yen into profit. Basic EPS growing faster than sales points to operating leverage that fits the automation backbone story. The TraceParts acquisition also fits a broader ecosystem approach, adding design content that can plug into factory projects where Keyence products already live.
Where Keyence bears still find ammunition
Even with strong headline figures, there is material for cautious investors. Net margin at 40% is high, which can trigger questions about how much further efficiency can realistically go without heavier investment. The share price has slipped roughly 3% over 30 days and nearly 4% over 90 days, so upbeat earnings have not translated into recent stock gains. That disconnect keeps execution risk and cycle worries alive, especially for readers who are concerned that strong profitability today might be tied to customer capex that can swing harder than expected.
With earnings running ahead of peers and the P/E multiple stretched, the key question is whether Keyence has the balance sheet strength and cash generation to support this premium. Check the financial health analysis of Keyence stock before you assume the risk is low.Hunt Quiet Mispricings Now
Keyence reports strong results while its share price reacts more cautiously. The real opportunity sits in finding stocks that could be undervalued before the market adjusts.
- Company 1 - 45% below our estimate - serves smaller business borrowers through deposit funding and adds securities, leasing and venture services.
- Company 2 - 26% below our estimate - sells grinding and ceramic components that integrate into production lines to reduce scrap and defects.
- Company 3 - 37% below our estimate - installs air and water systems that plant operators use as clean rooms and data centers tighten tolerances.
Those are three of them. See the full list of 15 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com