
Nine Month Earnings Just Shifted Sinotrans (SEHK:598) Investment Narrative?
- Sinotrans reported results for the nine months to September 30, 2026, with sales of CNY 71,986.84 million and net income of CNY 2,676.08 million, as basic and diluted EPS from continuing operations came in at CNY 0.373.
- The slight shift between lower sales and steady earnings suggests Sinotrans managed costs and mix tightly, which is particularly important for a logistics group investing heavily in technology and overseas expansion.
- We will now look at how Sinotrans's steady net income on softer sales affects the investment narrative that had been built before these earnings.
Scan how Sinotrans stacks up against peers and spot other logistics and infrastructure plays with resilient earnings trends using our hand picked 220 resilient stocks with low risk scores as a starting point.
Sinotrans Investment Narrative Recap
For a shareholder in Sinotrans, an important belief is that a tightly run logistics platform can hold earnings steady even when freight volumes or pricing soften. The latest nine month update fits that picture. Sales eased to CNY 71,986.84 million, while net income stayed around CNY 2,676.08 million and EPS inched up. This supports the view that cost discipline and mix management matter.
In the short term, the main swing factor is how quickly Sinotrans can translate its technology spending and overseas build out into more resilient, higher margin business. The biggest risk remains pressure on freight forwarding yields and domestic contract logistics rates. This earnings set does not radically change either the catalysts or the risks, but it gives you fresh data to test whether margins are holding at the levels you require.
The most relevant update here is the nine month 2026 earnings release itself, which arrives right before the Q3 2026 earnings call scheduled for October 28, 2026. Sales were CNY 71,986.84 million compared with CNY 75,037.59 million a year earlier, with essentially flat net profit. This outlines a picture of a logistics group trading some volume for margin stability.
For you, that matters when weighed against existing catalysts such as e commerce growth, overseas expansion and ongoing digital projects. The flat profit line, combined with small EPS gains despite a weaker top line, feeds into questions on the sustainability of margins, the forecast decline in earnings, and whether Sinotrans can offset risks like softer domestic logistics demand or intense price competition without losing financial flexibility.
Sinotrans is currently framed by analyst models that point to CN¥101.8b revenue and CN¥3.6b earnings by 2029, based on an assumed 2.8% yearly revenue growth rate and a projected earnings decrease of about CN¥0.4b from CN¥4.0b today.
Uncover why Sinotrans' fair value indicates a 15% potential upside to its current price that could narrow quickly.
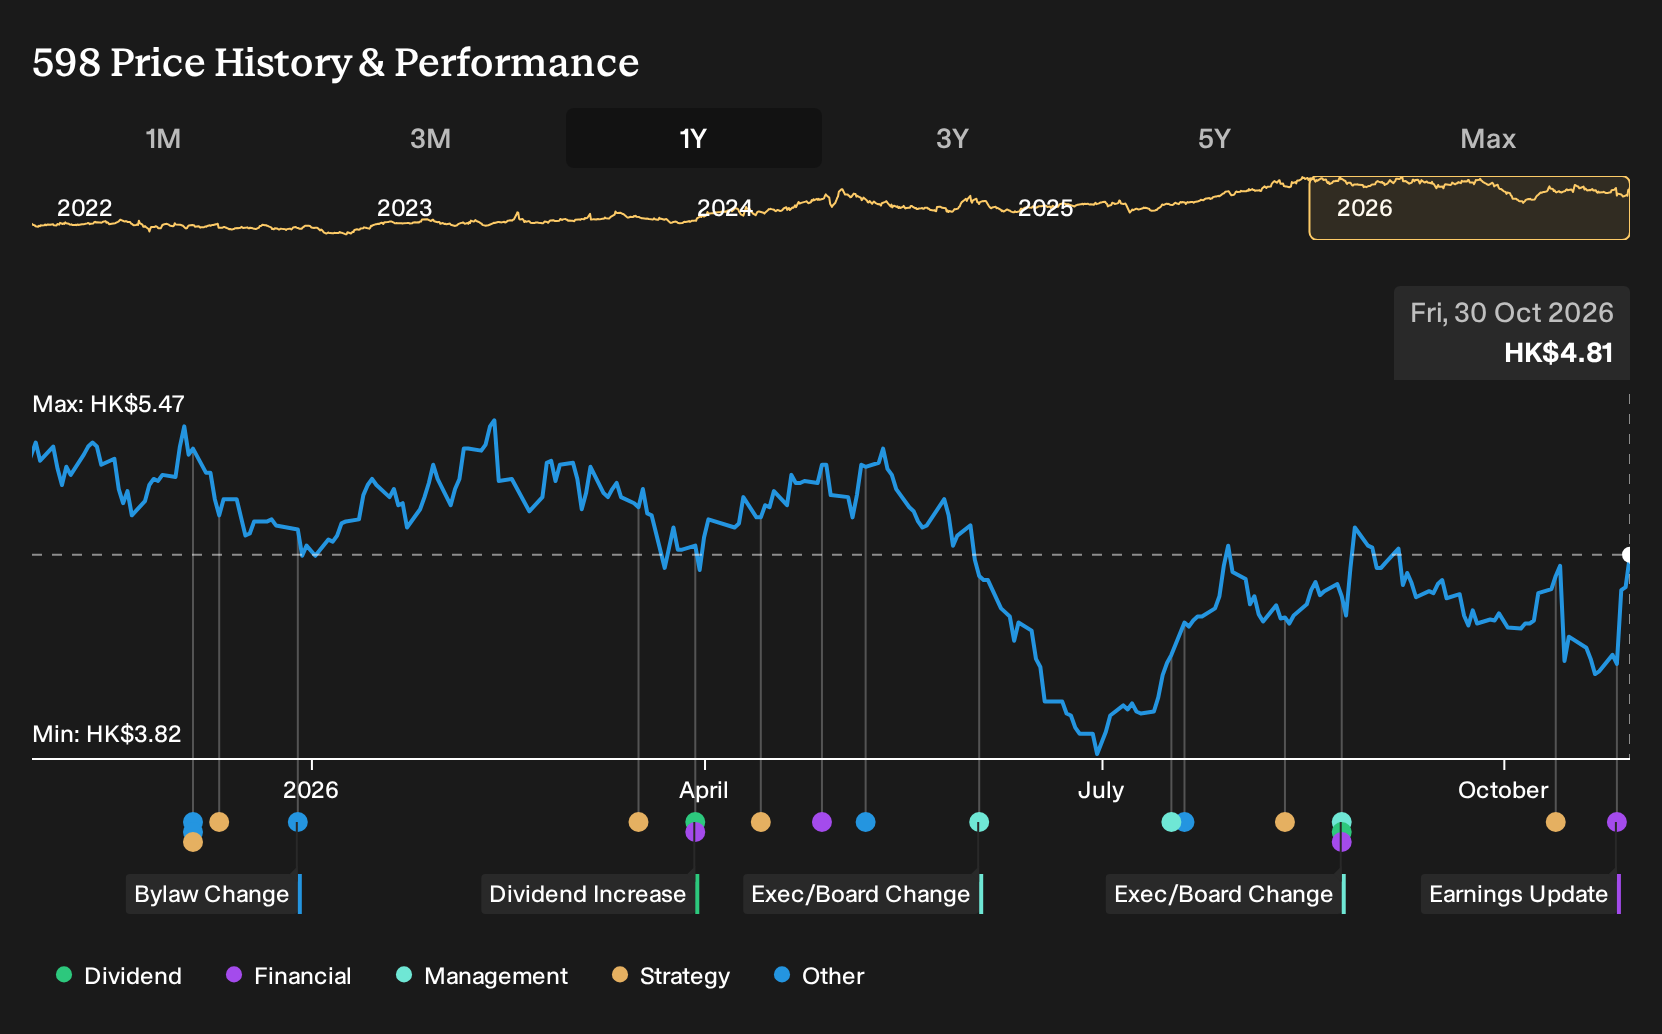
Exploring Other Perspectives
A different angle focuses on geopolitical risk. The most bearish Sinotrans analysts were pencilling in only CNY 91.7b of revenue and CNY 3.6b of earnings by 2029, and a P/E near 6.7x. That is a far more cautious story than consensus. Investors can use this earnings update to compare the different narratives.
Explore 3 other Sinotrans fair value estimates, including one that suggests it could be worth just HK$4.88.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sinotrans research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sinotrans. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sinotrans' overall financial health at a glance.
Looking for more investment ideas beyond Sinotrans?
Once you have a view on Sinotrans, it can help to widen the lens and compare it with other companies that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who want income that does more of the heavy lifting, check out 223 dividend fortresses with the potential to support a yield focused approach.
- If capital preservation and steadier balance sheets sit higher on your checklist, start with a list of solid balance sheet and fundamentals (202 results) that can handle tougher conditions.
- When you are hunting for opportunities that the wider market might be overlooking, scan through 607 high quality undiscovered gems that pair quality fundamentals with lower visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com