
Daito Trust ConstructionLtd (TSE:1878) Lifted Guidance, Is The Stock Fully Priced?
Daito Trust Construction Ltd (TSE:1878) drew fresh attention after revising its consolidated forecast for the year to March 2027, lifting projected net sales, operating profit and profit attributable to owners of the parent.
The renewed guidance has landed in a market that already pushed Daito Trust Construction Ltd’s share price up 9.17% year to date, while the 1-year total shareholder return of 17.57% sits against a 5-year total shareholder return of 43.88%. This suggests momentum has softened in the short term but has been constructive over a longer horizon as investors react to changing expectations for earnings and risk.
Compare Daito Trust ConstructionLtd with a hand picked list of solid balance sheet and fundamentals (22 results) that also balances earnings guidance with financial resilience.
The guidance upgrade has already nudged Daito Trust ConstructionLtd’s share price higher. The question now is whether the current valuation still compensates you for the construction and leasing risks on the table.
Preferred P/E of 10.7x: Is it justified?
Daito Trust ConstructionLtd now trades on a P/E of 10.7x, which is higher than both peers and the wider JP Real Estate industry even after the guidance upgrade.
The P/E ratio compares the current share price to earnings per share and provides a quick view of how much investors are paying for each unit of profit. For a business that earns a 19.9% return on equity and has grown earnings by 9.7% per year over the past 5 years, a richer tag can indicate that the market is willing to pay up for consistency, even if the most recent 5.3% earnings growth trails both its own history and the sector’s 13.7% result.
What really stands out is how that 10.7x P/E compares to two separate anchors. Compared to the peer average of 9.7x and the JP Real Estate industry average of 9.6x, Daito Trust ConstructionLtd is firmly on the expensive side. Yet when set against an estimated fair P/E of 15.2x, the current multiple looks materially lower, which suggests the market could still be applying a discount relative to where that fair ratio level sits.
Explore the SWS fair ratio for Daito Trust ConstructionLtd.
Result: Price-to-earnings of 10.7x (ABOUT RIGHT)
Still, Daito Trust Construction Ltd faces two clear swing factors: weaker construction demand in Japan, and any squeeze on real estate leasing profitability from vacancy or pricing pressure.
Find out about the key risks to this Daito Trust ConstructionLtd narrative.
Another view on Daito Trust ConstructionLtd’s value
The P/E story paints Daito Trust ConstructionLtd as slightly expensive, yet the SWS DCF model points in the opposite direction. With the share price at ¥3,225 against an estimated future cash flow value of ¥4,376.8, the stock screens as undervalued on this second lens. Which signal do you trust more?
Look into how the SWS DCF model arrives at its fair value.
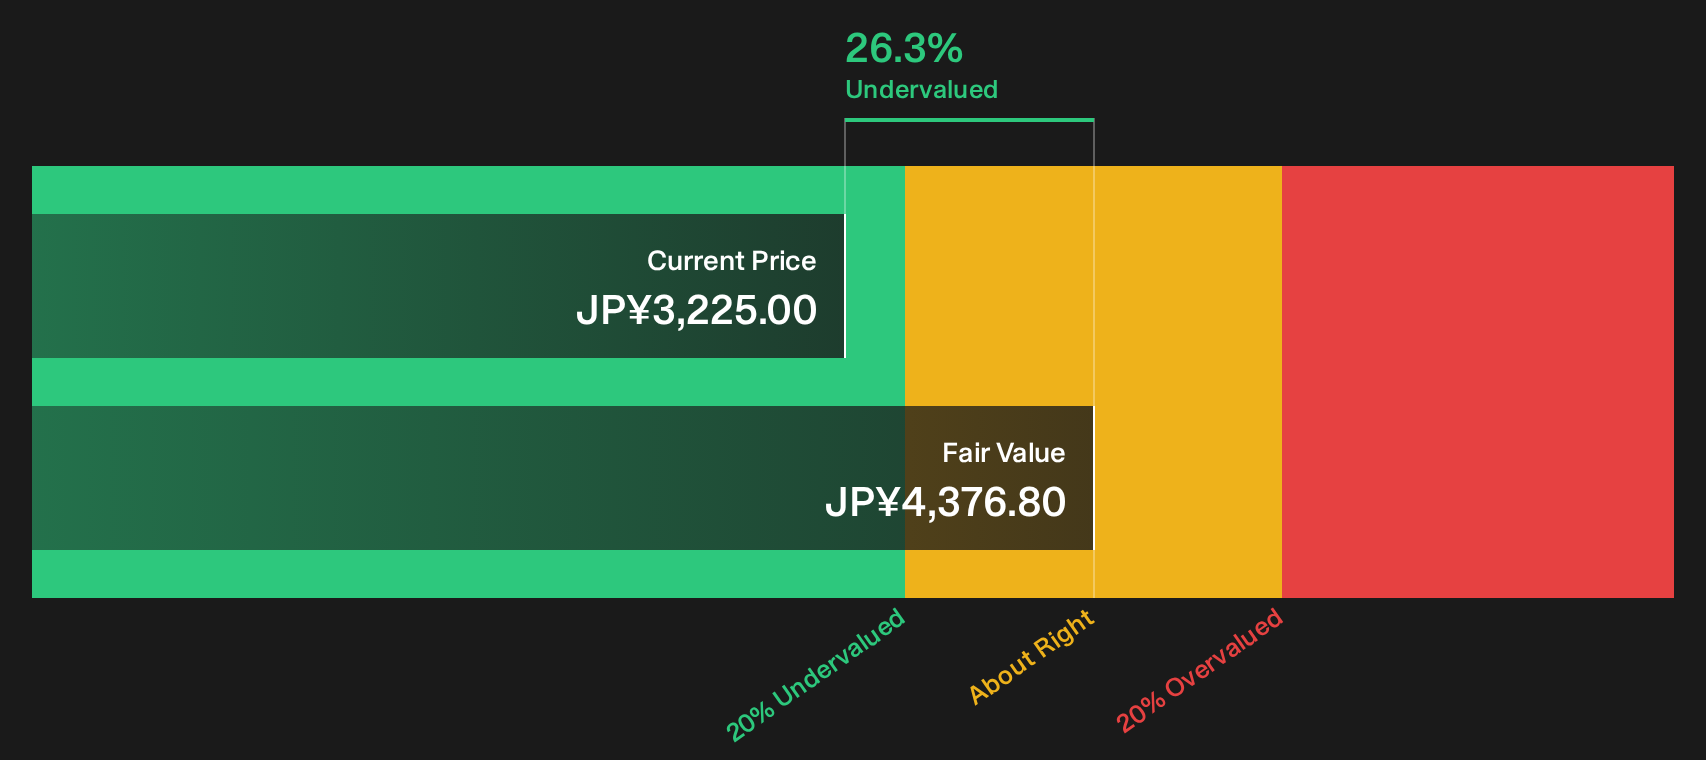
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Daito Trust ConstructionLtd for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Daito Trust ConstructionLtd’s value and risk profile can feel messy. Act while the information is fresh, weigh the competing metrics, and ground your own thesis using the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond Daito Trust Construction Ltd?
If Daito Trust Construction Ltd has sharpened your focus on valuation, do not stop here. Broaden your opportunity set with a few targeted idea lists that can surface quality prospects before they hit everyone’s radar.
- Target resilient balance sheets and focus your research on companies highlighted in the list of solid balance sheet and fundamentals (22 results).
- Hunt for potential mispricing by reviewing the 15 high quality undervalued stocks that may warrant a closer look on your watchlist.
- Prioritise quality with upside potential by scanning through the 71 high quality undiscovered gems that many investors might be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com