
Buenaventura (BVN) Stock May Be Undervalued Despite Fresh Dividend News
Compañía de Minas BuenaventuraA has rewarded long term shareholders with a very strong run over the past few years, yet recent price weakness raises a sharper question about what the current share price really reflects about its earnings power. After that kind of journey, you need to know whether you are looking at a miner whose valuation is closely aligned with its profit stream, or one whose price has moved ahead of what the income statement can support.
- Over the past 5 years the stock has gained about 285.9%, which puts real pressure on the current earnings multiple to justify that kind of compounding in hindsight.
- The latest company update highlighted higher copper production, solid EBITDA and a newly approved dividend, developments that can shape how investors think about the durability and timing of Buenaventura's future profit and cash generation.
- Your read on Compañía de Minas BuenaventuraA is one view; the desks covering it have another. See what analysts think Compañía de Minas BuenaventuraA's shares could be worth.
The stock's next move may depend on whether Buenaventura's current earnings are strong and reliable enough to support the price investors are paying today.
To see whether Compañía de Minas BuenaventuraA's earnings-based valuation puzzle shows up elsewhere in the sector, line it up against 35 elite gold producer stocks
Is Compañía de Minas BuenaventuraA a Bargain on Earnings?
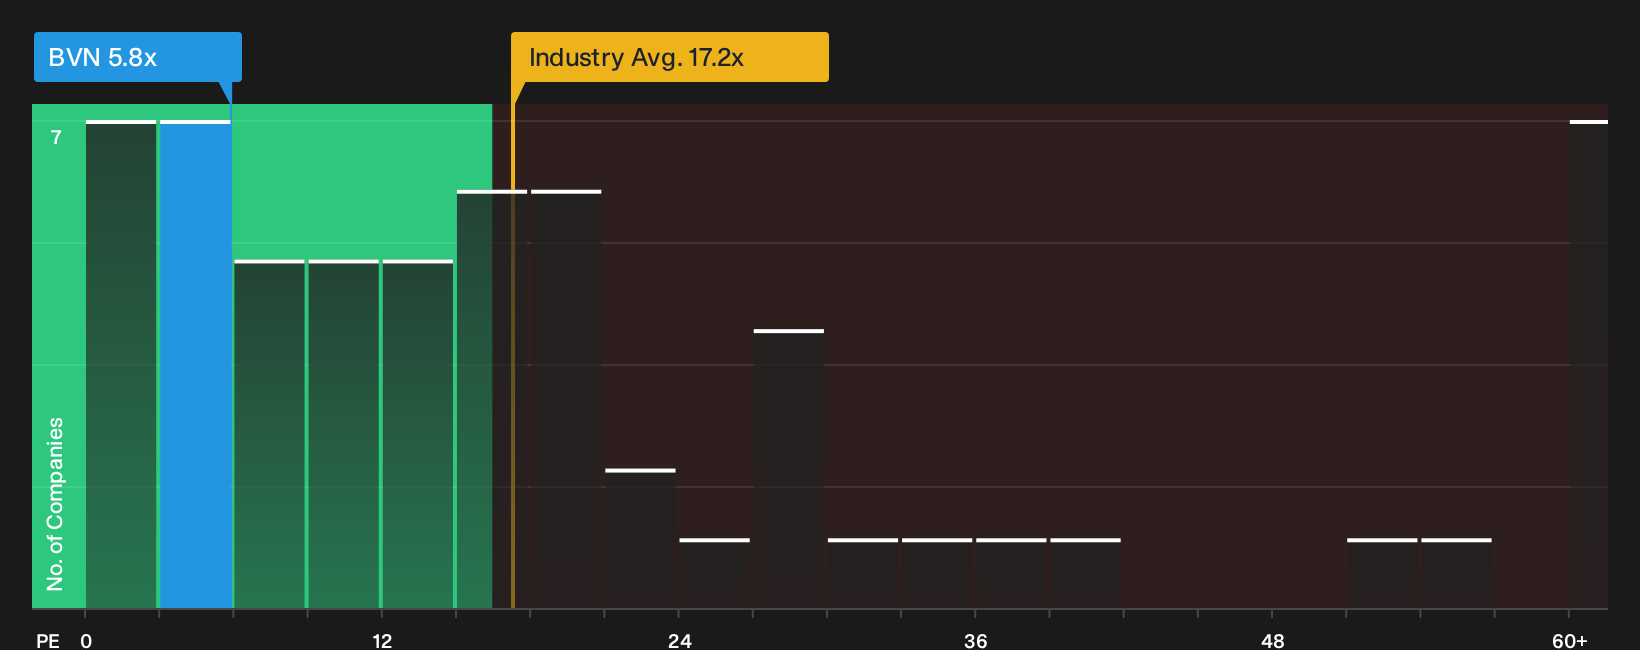
The P/E ratio fits Compañía de Minas BuenaventuraA because earnings remain a key yardstick for a mature metals producer. On this measure, the stock trades on about 5.8x earnings, which is far below the Metals and Mining sector average of roughly 17.2x and also well under the wider peer group closer to 35.9x. For a reader comparing options within the industry, that is a stark gap in what the market is currently willing to pay for each dollar of profit.
The fair multiple implied by the valuation model, which blends the firm’s growth profile, margins, scale and risk factors into a single benchmark, comes out higher than the current P/E. That places Buenaventura in undervalued territory on this framework, since the share price reflects a lower earnings multiple than the model would expect for this type of business. Because management has recently reported higher copper production and solid EBITDA, the low P/E suggests the market is pricing those updates cautiously rather than paying up aggressively for them. Explore the numbers behind Compañía de Minas BuenaventuraA's P/E valuation.
The Compañía de Minas BuenaventuraA Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Compañía de Minas BuenaventuraA leaves off by spelling out which assumptions on growth, margins and earnings would need to be true for the shares to be worth clearly more or clearly less than today’s price. Each one treats fair value as a thesis you can track over time rather than a single frozen snapshot, all housed on the company’s Community page.
One of the top community narratives on Compañía de Minas BuenaventuraA: 30% undervalued
"The main thing that has to go right is execution on San Gabriel’s ramp-up and metallurgical improvements, along with managing higher capex…"
Discover why this Narrative puts Compañía de Minas BuenaventuraA at 30% undervalued.
For Compañía de Minas BuenaventuraA, the share price is just the starting point
Before you treat Compañía de Minas BuenaventuraA as purely a valuation story, weigh what the broader checks are flagging about its risks and pressure points. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com