
PetroChina (SEHK:857) Rides Record Profit Growth As Valuation Questions Linger
PetroChina (SEHK:857) just reported third quarter 2026 earnings that showed a 21.6% rise in net income, record operating profit levels, and support from higher realized crude prices and stronger refining and chemicals performance.
The latest report landed alongside a sharp move in PetroChina's share price, which closed at HK$10.82 after a 1-day share price return of 5.66% and a 7-day share price return of 12.65% as investors reacted to the stronger earnings profile. That short-term momentum builds on a 27.00% year to date share price return and a 43.14% 1-year total shareholder return. The very large 5-year total shareholder return of 360.31% shows how the story has compounded for longer term holders.
Scan beyond PetroChina and see how it stacks up against 200 high quality undervalued stocks, which have resilient cash flows and balance sheets benefiting from similar earnings momentum.
After PetroChina’s sharp move and fresh record earnings, the share price now sits only modestly below analyst targets, yet far under some intrinsic value estimates. Where does fair value really line up in that spread?
Price-to-Earnings of 9.1x: Is it justified?
On pure valuation terms, PetroChina trades on a P/E of 9.1x, which lines up below both peers and fair value estimates and suggests the stock is being priced cautiously despite the strong share price run.
The P/E ratio compares what investors are paying today for each dollar of current earnings, which matters a lot for an integrated oil and gas group where profits can swing with commodity cycles and refining spreads. For PetroChina, this metric helps show whether the recent earnings strength is being given full credit in the share price or treated as something that may prove temporary.
At 9.1x earnings, the market is valuing PetroChina at a discount to the Asian Oil and Gas industry average of 10.9x and below the estimated fair P/E of 11.6x. That gap is meaningful, and if sentiment shifts closer to the fair ratio, valuation could move materially higher rather than staying pinned near current levels.
Explore the SWS fair ratio for PetroChina.
Result: Price-to-Earnings of 9.1x (UNDERVALUED)
Still, PetroChina’s case can be knocked off course by weaker commodity pricing or policy shifts that pressure cash generation and reduce investor appetite for the sector.
Find out about the key risks to this PetroChina narrative.
Another View On PetroChina’s Valuation
The P/E story suggests PetroChina is on the cheap side. Our DCF model presents a different perspective, with the stock at HK$10.82 compared with an estimated future cash flow value of HK$27.51. If cash flows matter most to you, is the gap a warning or an opportunity?
Look into how the SWS DCF model arrives at its fair value.
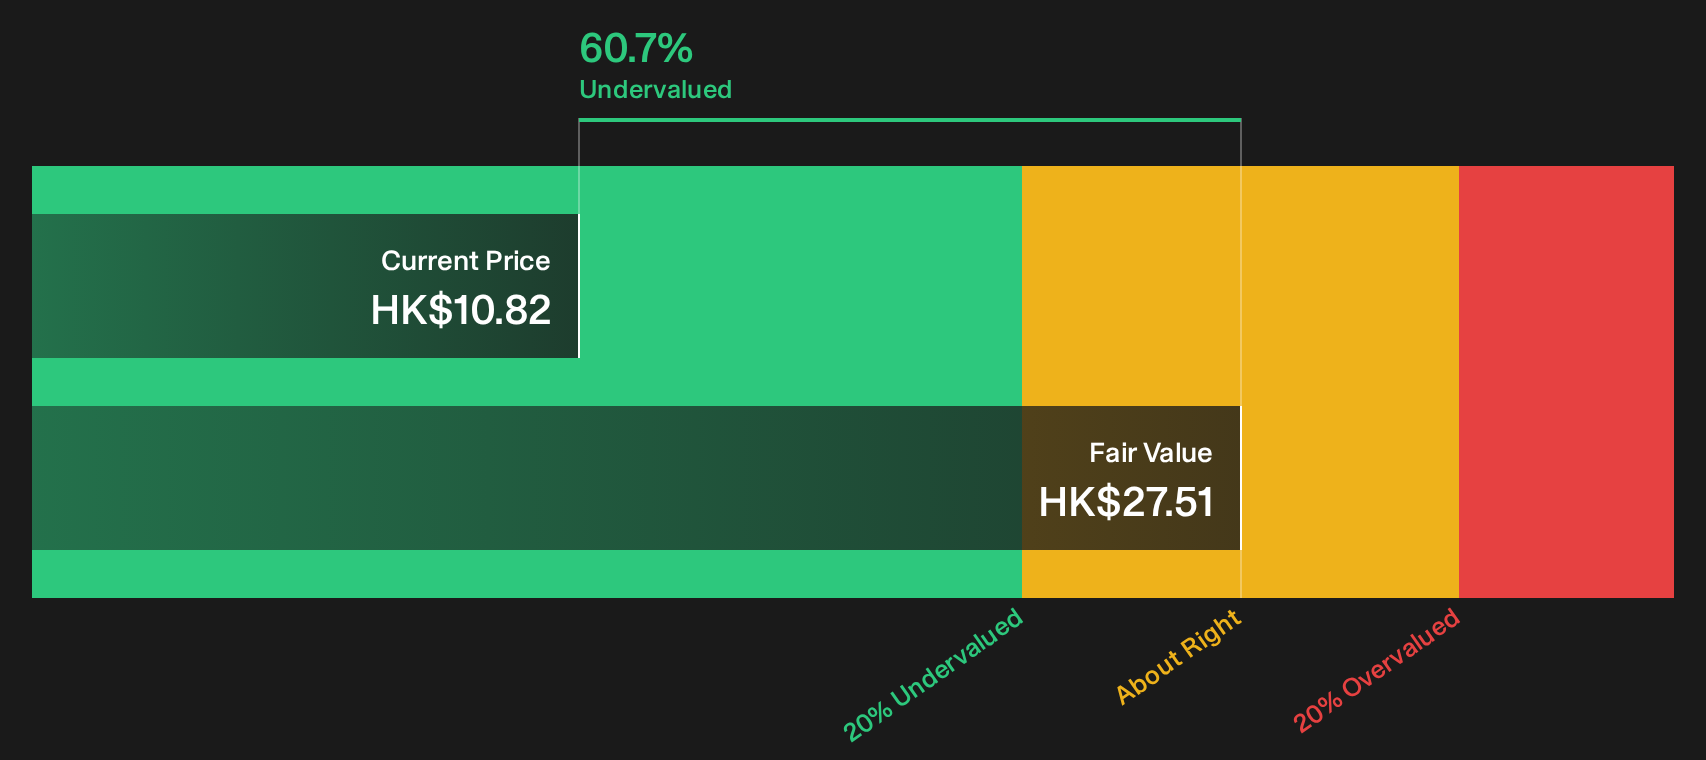
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out PetroChina for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 200 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Strong earnings, a busy share price chart and a valuation gap can feel exciting and uncomfortable at the same time, so move quickly and test the numbers against your own expectations, then weigh them against the 3 key rewards and 2 important warning signs.
Looking for more PetroChina investment ideas?
If PetroChina has sharpened your focus on value, broaden your watchlist with a few targeted idea lists that could point you to your next move.
- Scan for steady compounding potential by reviewing the 200 high quality undervalued stocks that pair robust fundamentals with share prices still trailing underlying business strength.
- Target resilience first and growth second by checking the 218 resilient stocks with low risk scores that score well on balance sheet strength and more stable risk profiles.
- Get ahead of the crowd by tracking the 604 high quality undiscovered gems where solid financials have yet to be fully reflected in market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com