
How Investors Are Reacting To BioMarin Pharmaceutical (BMRN) Fabry Disease Licensing Deal
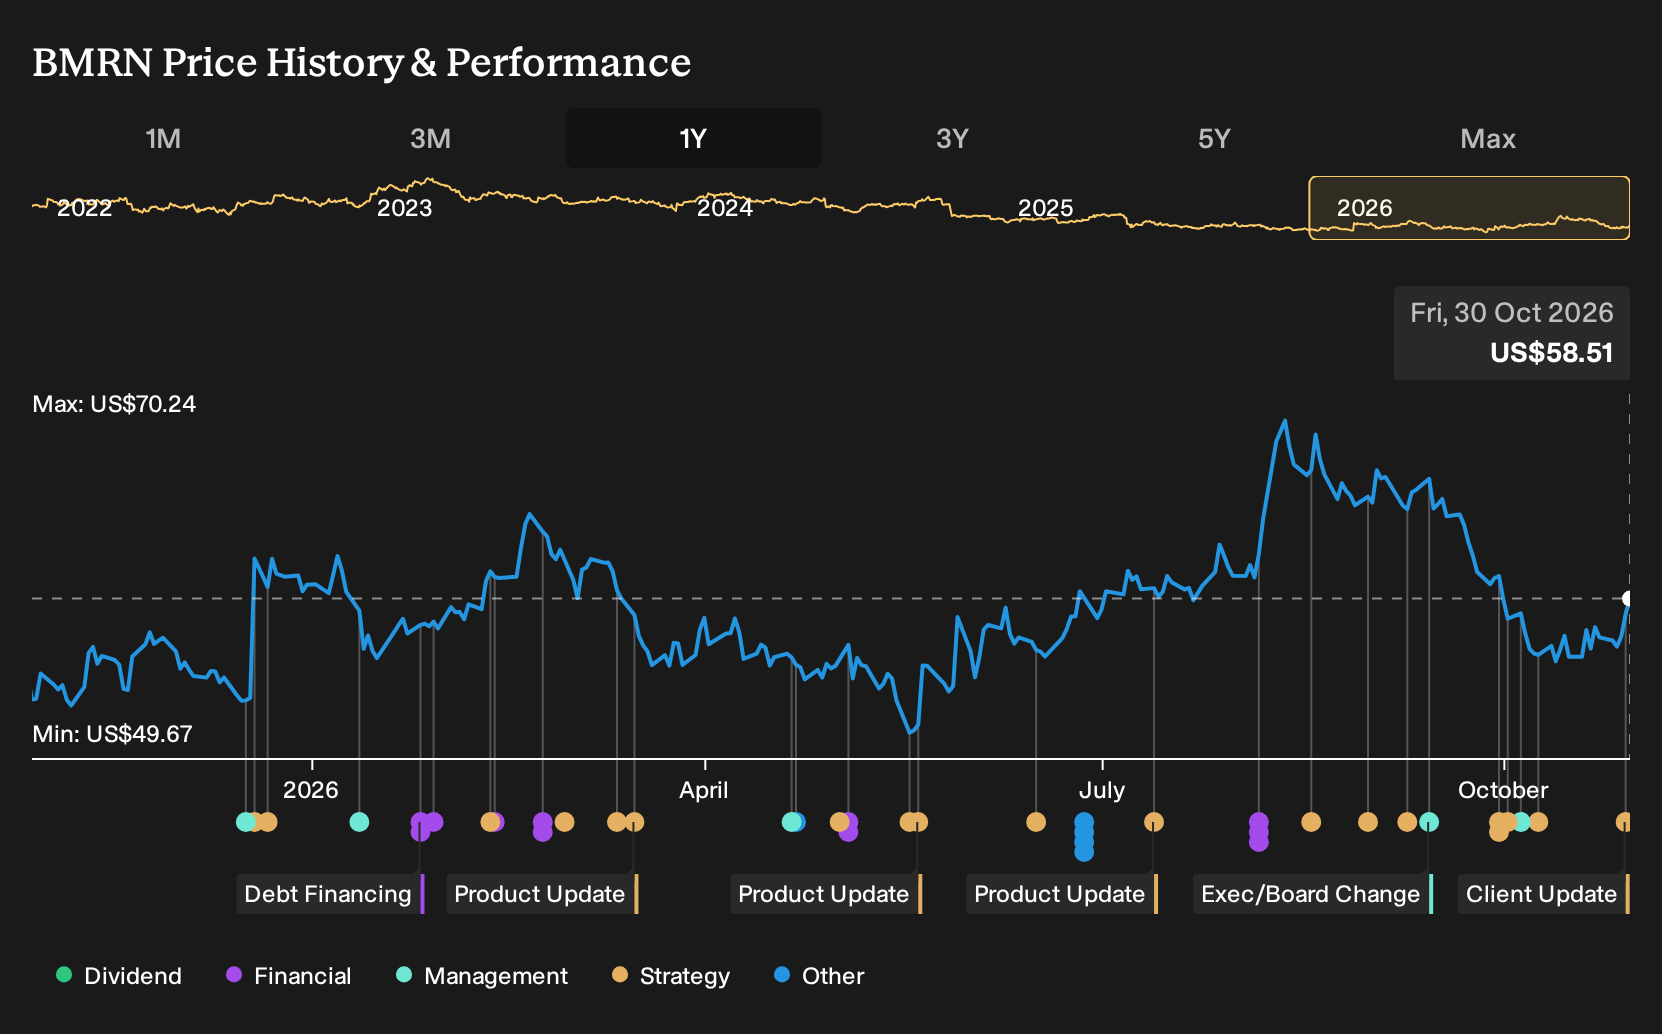
- On 29 October 2026, GC Biopharma and Hanmi Pharm announced an exclusive worldwide license agreement granting BioMarin Pharmaceutical rights outside Korea to HM15421/GC1134A, a long acting subcutaneous enzyme replacement therapy for Fabry disease, in return for a US$70 million upfront payment plus up to US$405 million in milestones and tiered royalties.
- The deal adds an investigational Fabry disease program to BioMarin Pharmaceutical’s rare disease portfolio, and also transfers future global development, manufacturing and commercialization costs and execution risk for HM15421/GC1134A to BioMarin after the current Phase 1/2 study.
- We will examine how BioMarin Pharmaceutical’s investment narrative is shaped by absorbing worldwide development responsibilities for this long acting Fabry therapy.
Scan how BioMarin Pharmaceutical’s Fabry bet compares with other rare-disease players by reviewing hand picked 18 high quality undiscovered gems that target under-the-radar businesses with strong fundamentals.
BioMarin Pharmaceutical Investment Narrative Recap
To own BioMarin Pharmaceutical, you need to believe management can turn a broad rare disease portfolio into much stronger margins and more efficient use of capital. The core near term focus stays on integrating prior deals, delivering on cost discipline and proving that earnings can catch up to a still rich 44.2x P/E.
The Fabry license fits that story but does not change the main short term swing factor, which is whether profits recover from a weak 2.1% net margin after a large one off loss. The biggest risk remains that high debt, acquisition spend and execution complexity keep returns on capital and earnings below expectations.
The new Fabry agreement lines up with earlier business development commentary that BioMarin Pharmaceutical wants to use roughly US$1b of annual free cash flow and future US$4b to US$6b of deal capacity to expand its pipeline. This latest licensing move adds another rare disease asset that will eventually need to earn its keep against that capital outlay.
That context matters because previous deals such as Amicus and Alesta already carry expectations for cost synergies and higher operating margins. If these acquired or in licensed therapies, including the Fabry program, do not contribute as planned, the stock could still screen as good value on P/S while struggling to deliver the margin and earnings catalysts investors are watching.
BioMarin Pharmaceutical's analyst narrative points to US$5.1b in revenue and US$1.2b in earnings by 2029. That forecast assumes 14.0% yearly revenue growth and an earnings increase of about US$1.1b from US$73.0m today.
Uncover how BioMarin Pharmaceutical's fair value indicates a 57% potential upside to its current price that equity markets may not leave on the table for long.
Exploring Other Perspectives
For a different angle on BioMarin Pharmaceutical, zoom in on the risk bearish analysts stress most. They worry earnings remain choppy if VOXZOGO growth underwhelms and Amicus synergies slip, which is why their pre news forecasts sat closer to US$4.8b in 2029 revenue and about US$527.2m in earnings. That is far below the consensus path. It shows how sharply views can diverge and why it helps to compare several narratives before deciding how this Fabry deal might reshape your own view.
Explore 5 other BioMarin Pharmaceutical fair value estimates, including one that suggests it could be worth just $60.00.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your BioMarin Pharmaceutical research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for BioMarin Pharmaceutical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BioMarin Pharmaceutical's overall financial health at a glance.
Looking for more investment ideas beyond BioMarin Pharmaceutical?
Once you have a handle on BioMarin Pharmaceutical, it can help to widen your watchlist with other businesses that share attractive qualities, whether that is valuation support, resilient balance sheets or a smoother risk profile.
- If you want potential value on your side, review a hand picked set of companies trading at appealing valuations and backed by solid fundamentals via the Simply Wall St screener for 29 high quality undervalued stocks.
- For investors who care most about financial resilience, scan a list of solid balance sheet and fundamentals (25 results) and see which businesses pair prudent leverage with robust fundamentals.
- If keeping downside risk contained is a priority, broaden your opportunity set by assessing a 30 resilient stocks with low risk scores that filters for resilience before anything else.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com