
Illumina (ILMN) Stock Price Drops Despite Strong Q3 Earnings
Illumina has long been treated as the genomic sequencing bellwether that can justify a premium multiple. Q3 2026 earnings told a different story than the share price did. The stock dropped about 19% to roughly US$236 in the first session after the release, even as management lifted full year revenue, margin and earnings guidance.
The real hinge of this quarter was profitability. Non GAAP operating margin reached 25% and free cash flow hit US$378 million, which is a powerful contrast to a market that suddenly priced the stock as if the thesis had cracked.
Love Illumina's 25% non GAAP operating margin and US$378 million in free cash flow but uneasy about paying up after a sharp price move? You can compare it with a curated list of companies that pair strong profitability with solid finances in our list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$1,129 million vs. US$1,084 million (up 4.2%)
- Net Income (Q3 2026 vs. Q3 2025): US$220 million vs. US$150 million (up 46.7%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.46 vs. US$0.98 (up 49.4%)
- Non GAAP Operating Margin (Q3 2026): 25%, compared with company guidance commentary that implied a lower margin level earlier in the year (margin ahead of prior internal expectations)
Prefer clean charts instead of another wall of Illumina earnings tables and footnotes? Get a full visual picture of the business, with its valuation front and center, in the interactive company report for Illumina.
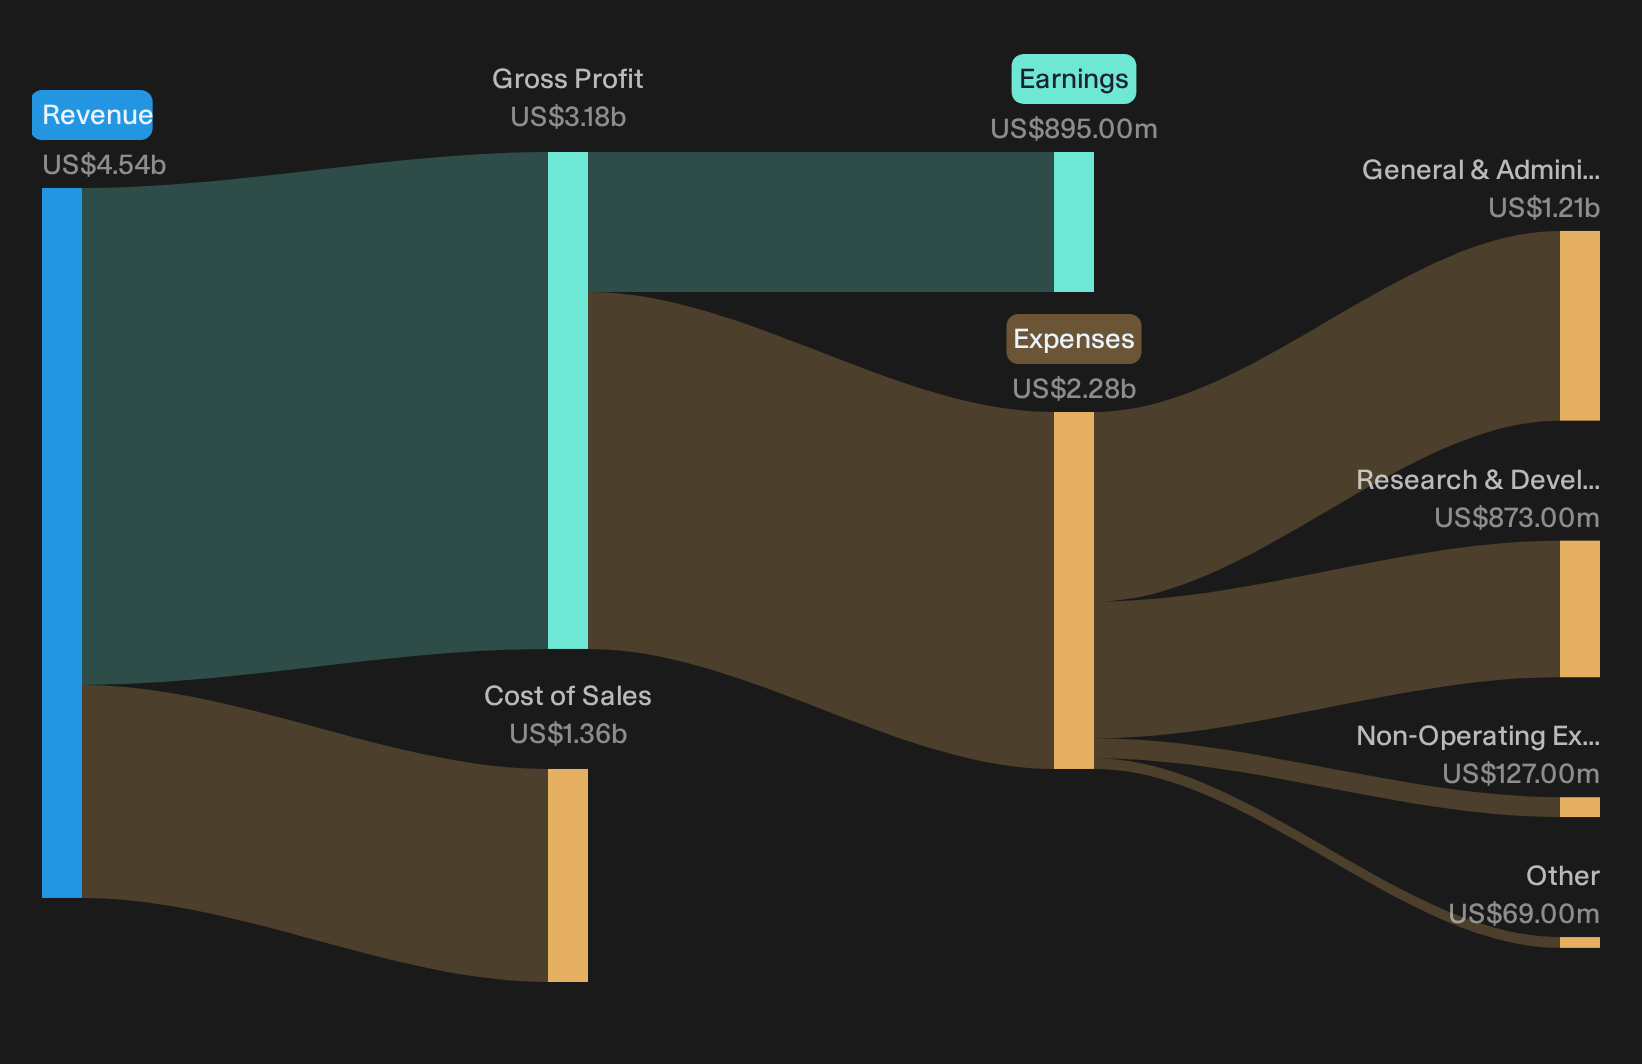
Evaluating Illumina’s Clinical and Data Upside
Some optimistic views argue that Illumina may be able to turn its clinical shift and data efforts into a long-run earnings compounder.
"The main factor that would need to go right is that Illumina continues to convert clinical demand, multiomics products and BioInsight into higher margin consumables and data revenue while managing research softness, China constraints and legal or competitive pressures."
Q3 results provide partial support for that vision. Sequencing consumables grew, with clinical consumables in Rest of World up 14%, while research and applied consumables in those regions declined 6%. Services and other revenue, which includes Billion Cell Atlas and BioInsight, rose 8% in Rest of World terms and contributed to Illumina reaching a 25% operating margin, above prior guidance commentary.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Illumina Bear Case: Margin Fears Meet Mixed Evidence
Bearish investors argue Illumina’s cost structure will blunt the payoff from NovaSeq X and the growing clinical mix.
"Although Illumina has expanded non GAAP operating margin and reaffirmed its margin outlook, the need to secure additional memory inventory ahead of rising prices and absorb higher freight expenses indicates that elevated component and logistics costs could persist and limit further gross margin improvement and future net margin expansion."
Q3’s 25% non GAAP operating margin, which was 100 bps above guidance, directly challenges the idea that component and freight inflation already cap profitability. Illumina also generated US$378m in free cash flow and lifted full year margin guidance. The miss against the bear script is not cost pressure itself, which exists, but that it failed to derail near term margin gains in this print.
Hunt For Mispriced Earnings Power
Illumina shows how quickly sentiment can change when profitability shifts against expectations. The real opportunity is identifying stocks that could be undervalued before stronger fundamentals appear in the valuation.
- Company 1 - 37% below our estimate - uses AI tools and tighter carrier vetting to raise heavy haul and platform freight productivity while reducing insurance and claims costs.
- Company 2 - 30% below our estimate - ties AI centric networking gear and data center hardware to subscription style services while integrating a major acquisition aimed at higher margin recurring revenue.
- Company 3 - 38% below our estimate - expands high horsepower engine capacity for power systems aligned to long term data center demand while directing more capital toward combustion and power projects over loss making ventures.
Those are three of them. See all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com