
Kingfisher (LSE:KGF) Could Be 13% Below Fair Value On Earnings Upgrades
Recent upgrades to earnings expectations and a strong momentum score have pushed Kingfisher (LSE:KGF) into the spotlight, as the retailer’s share price performance continues to outpace both its sector and the wider market.
Over the past year, momentum has been building, with Kingfisher’s 90-day share price return of 14.0% and 30-day share price return of 5.23% contributing to a 1-year total shareholder return of 18.69% and a 3-year total shareholder return of 79.44%.
Scan for other Kingfisher style movers by reviewing the hand picked 12 high quality undervalued stocks, which combine quality fundamentals with strong price momentum.
Kingfisher’s shares have surged while the intrinsic estimate still sits above the current price and the broker target sits below it. Is the market applying healthy caution or mispricing the recent momentum?
Most Popular Narrative: 4% Overvalued
Kingfisher’s most followed valuation narrative puts fair value at £3.37, slightly below the last close at £3.52. This helps explain why recent share price strength is meeting a more cautious long term view that leans on gradual progress rather than rapid expansion.
The main thing that has to go right is that Kingfisher continues to grow higher value trade and digital sales while holding on to the structural cost and working capital efficiencies already visible in recent results.
The current valuation implies a fair price for Kingfisher shares that already reflects the company’s progress on trade growth, digital scaling and margin improvement, with limited room for missteps.
See why 18 investors see Kingfisher as 4% overvalued.
Result: Fair Value of £3.37 (OVERVALUED)
Still, pressure on consumer demand in France and Poland, along with the heavy spend behind Screwfix France, could both challenge the current Kingfisher narrative.
Find out about the key risks to this Kingfisher narrative.
Another View: Kingfisher Through The Cash Flow Lens
The share price might look a little rich next to the £3.37 analyst fair value, yet our DCF model paints a different picture. On that cash flow view, Kingfisher at £3.52 screens at roughly 12.6% below an intrinsic estimate of £4.02. That raises a simple question: is sentiment still catching up with the cash flow story?
For readers who want to see exactly how that cash flow based estimate is built step by step, it is worth going straight to the SWS DCF model and stress testing the inputs used for Kingfisher. Look into how the SWS DCF model arrives at its fair value.
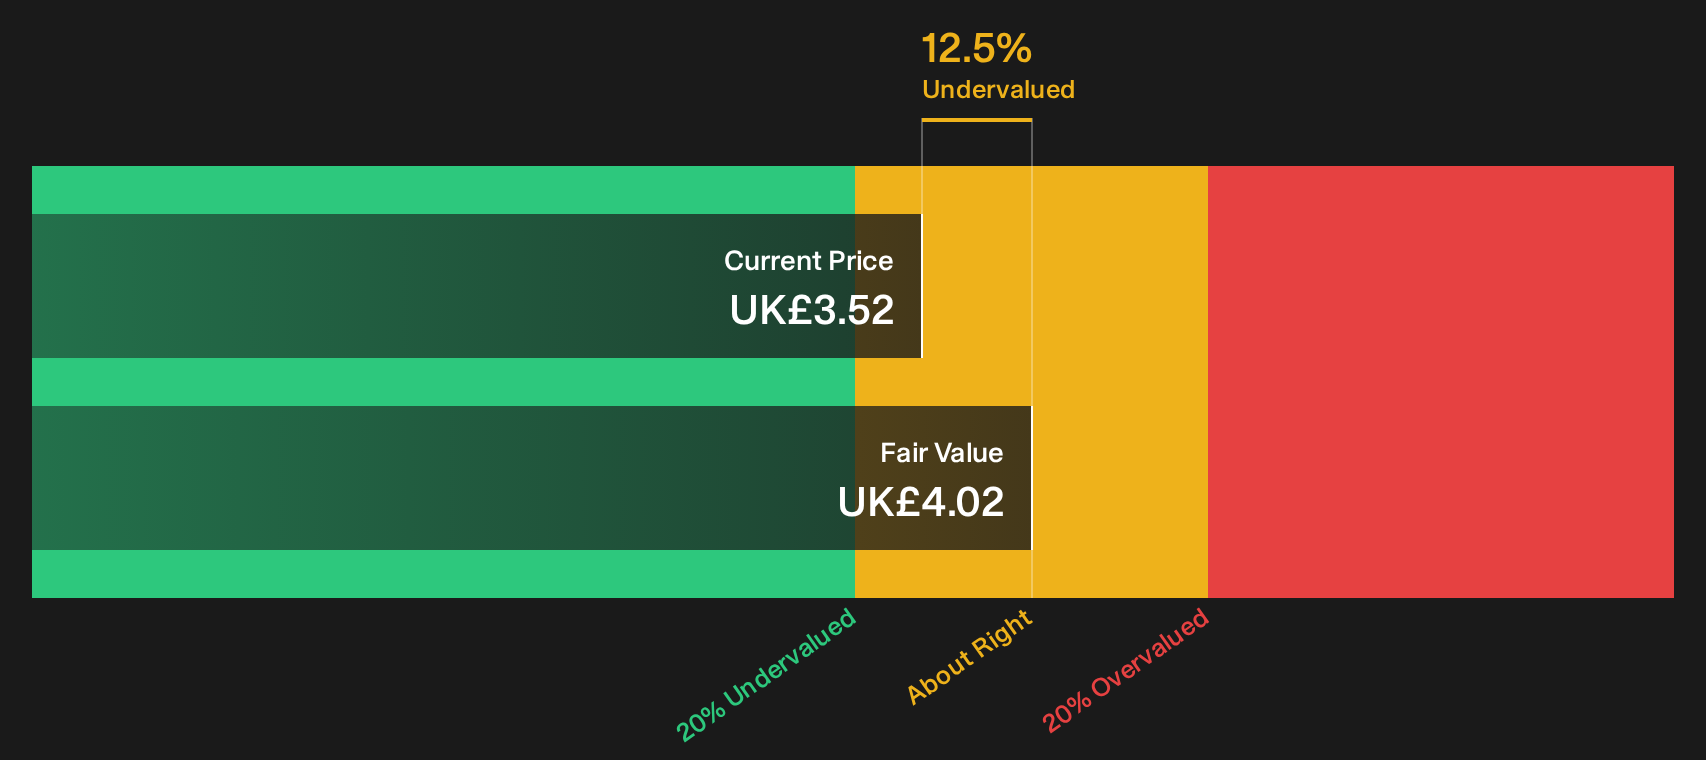
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kingfisher for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Momentum is clearly the headline here, yet the mix of concerns and positives around Kingfisher is more balanced than it first appears, so move fast and scrutinise the underlying numbers yourself before settling on a stance. To pressure test both sides of the argument in one place, start with the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Kingfisher?
If you stop at Kingfisher, you miss a wider set of opportunities. Let the screener surface ideas while you focus on judging which ones truly fit.
- Hunt for underappreciated quality by checking companies that combine strong fundamentals with attractive pricing through the 12 high quality undervalued stocks.
- Prioritise resilience and sleep-at-night potential by scanning the 5 resilient stocks with low risk scores for businesses with lower risk scores and sturdier profiles.
- Review the 5 high quality undiscovered gems to explore companies that pair solid fundamentals with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com