
Sansan And 2 Other Japanese Growth Stocks
Japan is shifting into a new chapter after the Bank of Japan confirmed inflation is broadly around its 2% goal and kept rates steady near 1.25%. That signals a more stable backdrop for homegrown growth stories, especially businesses where analysts see earnings moving higher over the next few years. This article highlights three financially solid Japanese stocks from a high growth potential screen that could deserve a closer look.
The three stocks highlighted here offer a compelling starting point if you want exposure to financially solid businesses where analysts see strong earnings growth potential over the next few years. However, if you want the absolute best, these 17 best high growth potential stocks are the cream of the crop.
Sansan (TSE:4443)
Sansan is a Tokyo based SaaS provider whose core Sansan cloud platform helps corporate sales and marketing teams manage business contacts and meetings, aligning cleanly with the Healthy high growth potential theme. The Sansan/Bill One segment generates about ¥48.9b of revenue, far ahead of Eight on ¥7.1b, and the group is valued around ¥273.8b.
Sansan plugs into this screener because earnings growth has already inflected, with very large profit expansion last year and forecasts indicating about 23.3% annual earnings growth over the next three years. That trajectory rests on a scalable contact data engine that could look very different if a single pressure on margins shifts direction.
If that margin pressure really flips, the 3 key rewards and 1 important warning sign shows how Sansan’s upside case and pressure points currently stack up.

Micronics Japan (TSE:6871)
Micronics Japan is a Musashino based maker of semiconductor test gear such as probe cards, wafer probers and test sockets, which is described as a core enabler of the Healthy high growth potential theme. The probe card business produced about ¥84.9b of revenue versus ¥1.4b from TE, and the company is valued around ¥439.5b.
Analysts link Micronics Japan to the Healthy high growth potential screen because earnings are forecast to expand, supported by demand for its chip testing tools. Recent guidance points to profit and cash generation, so the main swing factor is how the supply demand balance in advanced memory testing develops.
That supply demand question is exactly what the analysis report for Micronics Japan could be masking for Micronics Japan, with test capacity, pricing power and earnings sensitivity all in play.

Kasumigaseki CapitalLtd (TSE:3498)
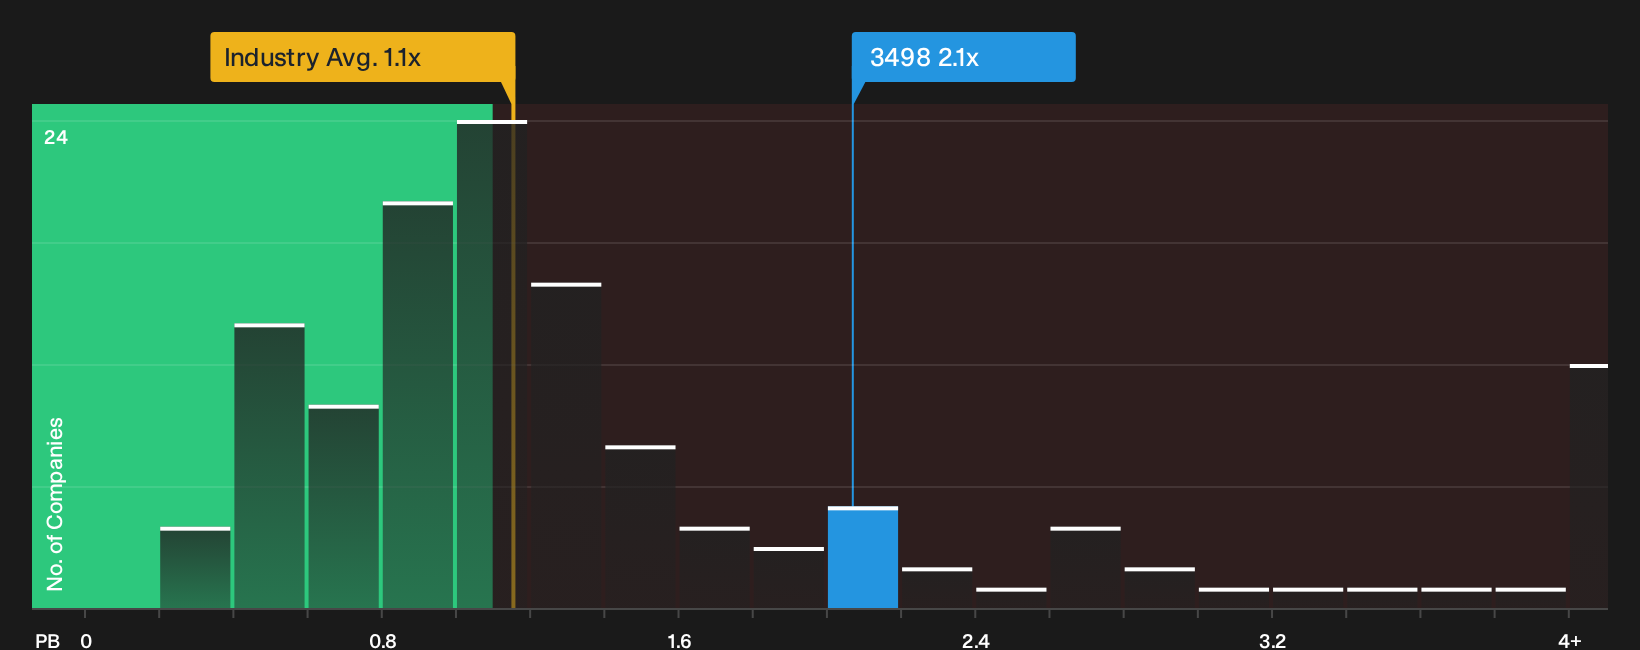
Kasumigaseki Capital runs a real estate consulting business that includes solar power generation projects alongside warehouses, apartment hotels and healthcare facilities. It generated about ¥163.8b of consulting revenue in Japan and is valued at roughly ¥180.1b, tying its story closely to domestic asset development.
Kasumigaseki Capital combines theme friendly solar power projects with a P/E around 10.8x, supported by ROE near 19% and company guidance that signals a focus on profitability. Investors get a mix of growth and income, but the appeal depends heavily on how pressure on cash flows and leverage is managed.
That cash flow and leverage balance is exactly what the 3 key rewards and 5 important warning signs (2 are major!) could be reframing for Kasumigaseki Capital, before growth and income expectations start to decouple.
Seeking Fresh Alternatives Before The Crowd
Fresh ideas move first. Breakout stories gain momentum while they are still under the radar for now, and laggards keep dropping. Scan these filtered lists and consider them at an early stage.
- Explore steady compounding potential with a curated 27 dividend fortresses that focuses on balancing income strength with balance sheet resilience before yields change.
- Track where real-world infrastructure demand meets future-facing tech by reviewing 39 power grid technology and infrastructure stocks that is connected to ongoing grid upgrade activity.
- Look for early leaders in a specialist materials niche through 33 best rare earth metal stocks while many investors are still focused elsewhere.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com