
Carlsberg (CPSE:CARL B) Climbed, But What Is Behind The Attention Now?
Carlsberg (CPSE:CARL B) just reported a quarterly update in which strong soft drinks and alcohol-free sales helped offset weaker beer volumes, while management kept its 2026 profit outlook and highlighted currency tailwinds.
The latest quarterly update appears to have backed a strong recent run in Carlsberg, with the share price up 13.99% over 30 days and 17.58% year to date, while the 1 year total shareholder return of 31.80% points to momentum building rather than fading.
Capitalize on the momentum around Carlsberg by scanning a hand picked 603 high quality undiscovered gems that share strong fundamentals but are still flying under most investors' radar.Bulls see Carlsberg’s soft drinks mix, India plans and currency tailwinds as justifying the rerating. Bears argue the rally already prices this in. Which side does the current valuation actually support?
Most Popular Narrative: 8% Undervalued
Carlsberg last closed at DKK971, while the most followed narrative pegs fair value around DKK1,050, which implies some upside already baked into the story but not fully reflected in the price.
Carlsberg will gradually evolve from a traditional beer company into a broader premium beverage group, with beer, soft drinks and alcohol-free beverages all contributing to growth. The acquisition of Britvic strengthens Carlsberg’s exposure to soft drinks and gives the group a more balanced portfolio at a time when beer volumes are under pressure in some markets. Premium beer, alcohol-free beer and soft drinks should support modest organic revenue growth, while cost discipline, integration synergies and operating leverage should allow operating profit to grow slightly faster than revenue. I expect Carlsberg to remain a defensive, cash-generative consumer staples company rather than a high-growth stock. My base case is that adjusted EPS grows from about DKK 61 in 2025 to the mid-to-high DKK 60s over the next few years, supported by Britvic synergies, premiumisation, Asia growth and continued dividend discipline. Using a fair multiple of around 16 to 17 times normalised earnings. This assumes moderate earnings growth, no major deterioration in consumer demand, gradual deleveraging and continued dividend growth.
See why 5 investors see Carlsberg as 8% undervalued.
Result: Fair Value of DKK1,050 (UNDERVALUED)
Still, the Britvic deal could disappoint on integration or cost savings, and any setback in Asia or India execution would quickly test this Carlsberg rerating story.
Find out about the key risks to this Carlsberg narrative.
Another View: What Carlsberg’s P/E Is Telling You
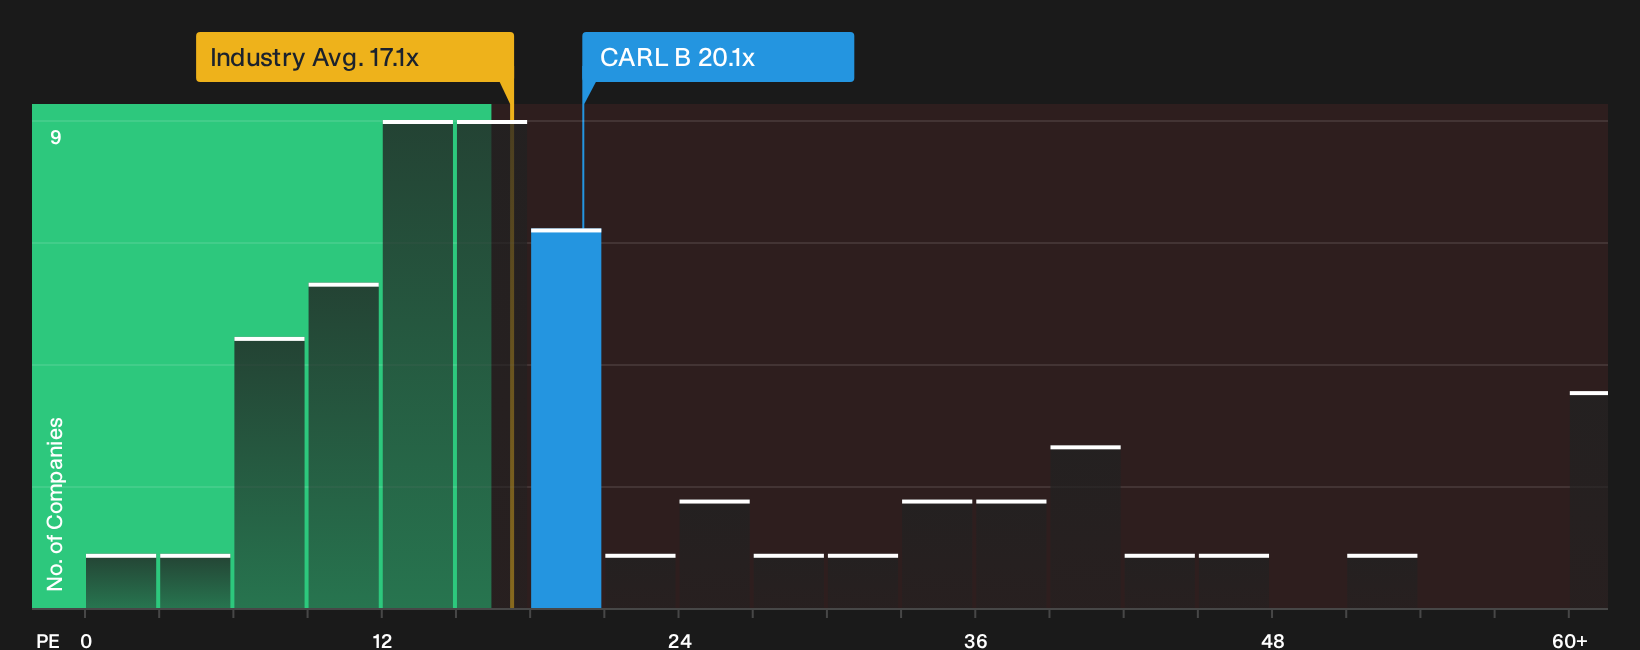
The SWS DCF model points to upside, yet the current 20.1x P/E looks punchy next to the fair ratio of 17.5x, the European Beverage average of 17.2x and peers at 18.3x. That kind of premium can signal quality, or it can narrow fast if expectations slip. Which story do you think the market is really paying for?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
So with Carlsberg attracting both enthusiasm and caution, you should pressure test the story yourself by using the full breakdown of 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Carlsberg?
If Carlsberg has sharpened your focus, now is the moment to widen your opportunity set before the next move passes you by.
- Target resilient quality and see which businesses combine strong earnings power with attractive pricing through a curated set of 199 high quality undervalued stocks.
- Prioritize staying power and review a carefully filtered list of solid balance sheet and fundamentals (203 results) that can help anchor your portfolio when conditions get tougher.
- Build a smoother ride and hunt for dependable income opportunities by scanning a focused pool of 218 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com