
Did Earnings Beat Just Shift Omnicell Stock's Investment Narrative?
- Omnicell reported Q3 2026 revenue of US$307.85 million and net income of US$11.04 million, then lifted full year earnings guidance after stronger profitability and non GAAP EBITDA on roughly US$308 million of sales.
- Management pointed to margin gains tied to Titan XT hardware and OmniSphere software rich contracts, indicating that new product rollouts are already influencing the earnings mix even as near term revenue guidance for Q4 remains cautious.
- We will now examine how Omnicell's raised full year earnings outlook could influence the broader investment narrative investors follow.
Review how Omnicell's earnings respond to changes in product mix and margins, then evaluate other healthcare tech stocks with strong balance sheets and fundamentals using our curated list of solid balance sheet and fundamentals (25 results)
Omnicell Investment Narrative Recap
To own Omnicell, you need to believe the shift toward higher margin, software rich medication management can offset flat or choppy hardware demand. Q3 results and the full year earnings guidance raise both hinge on that story. Profitability looked healthier, yet management stayed cautious on Q4 sales, so the near term revenue picture has not really changed.
The key short term catalyst is execution on Titan XT and OmniSphere as an integrated offer while keeping tariff and component costs in check. The biggest risk is that longer hospital decision cycles or macro pressure slow new automation projects, which could leave Omnicell relying more heavily on efficiency gains than fresh volume.
The most relevant new piece for that thesis is Omnicell’s tighter 2026 revenue outlook of US$1.225b to US$1.231b paired with a higher earnings guide. That combination indicates management is finding savings and a richer mix even without chasing a bigger top line, which matters if hospitals remain careful with capital budgets.
Q4 revenue guidance of US$295 million to US$301 million keeps expectations measured and puts the spotlight on margin delivery, non GAAP EBITDA and early traction from Titan XT shipments. For you as an investor, the execution test is simple: watch whether OmniSphere adoption and service contracts progress fast enough to offset tariff, competition and pricing pressure as the model tilts further toward software.
Omnicell's narrative projects US$1.4b revenue and US$71.2 million earnings by 2029. This assumes 4.4% yearly revenue growth and an earnings increase of about US$50.8 million from US$20.4 million today.
Uncover why Omnicell's fair value indicates a 67% potential upside to its current price, which could narrow quickly.
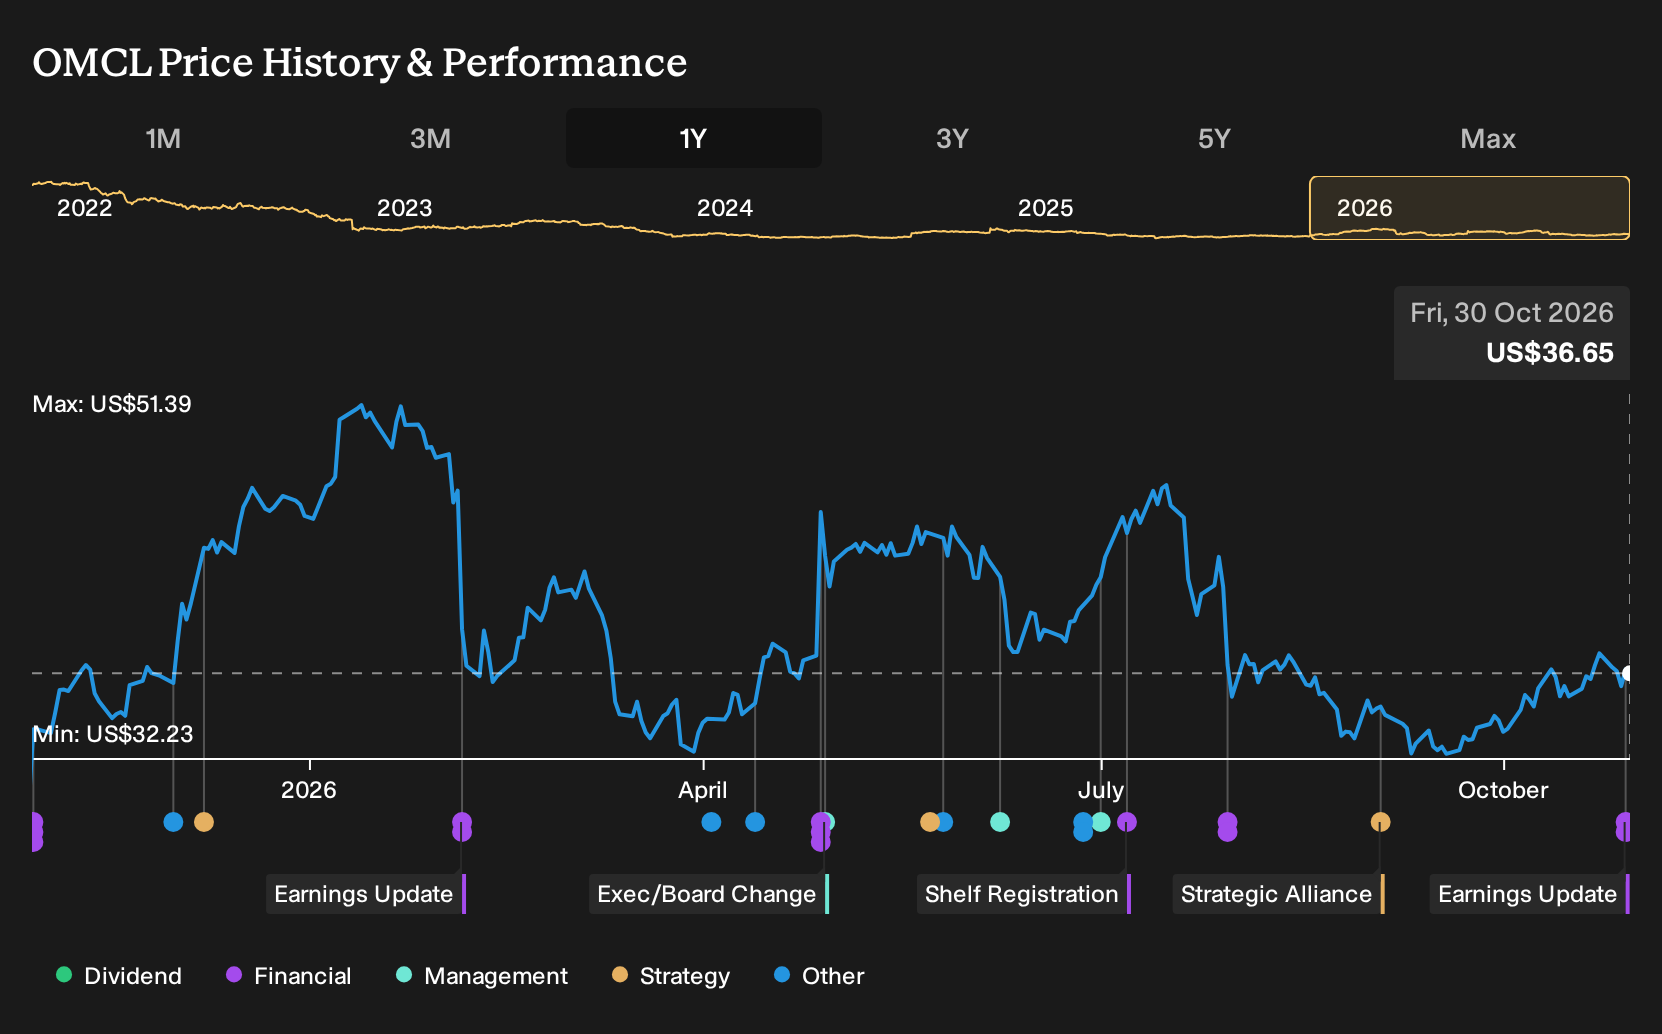
Exploring Other Perspectives
One alternate view puts bookings risk front and center. The most pessimistic analysts were modeling roughly US$1.3b of revenue and US$77.5 million of earnings by 2029, before this Q3 Omnicell report. That outlook leans on slower deal conversion and softer pricing power, so you should expect those narratives to evolve as fresh data arrives.
Explore 3 other Omnicell fair value estimates, including one that suggests it could be worth just $57.86!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Omnicell research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Omnicell. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Omnicell's overall financial health at a glance.
Looking For More Investment Ideas Beyond Omnicell?
If this Omnicell update sharpened how you think about margins, forecasts and risk, you can use that same lens to size up other opportunities with the Simply Wall St Screener. You can filter by balance sheet strength, income reliability or potential mispricing so your watchlist reflects the kind of portfolio you want to build.
- For investors who prioritize financial resilience, start by scanning a list of solid balance sheet and fundamentals (25 results) that combine healthy fundamentals with robust liquidity and low leverage.
- If value is your focus, look for mispriced quality in a curated 29 high quality undervalued stocks that may trade below what their cash flows and balance sheets imply.
- For income oriented portfolios, concentrate on cash return potential through a set of 5 dividend fortresses that pair higher yields with balance sheet support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com