
How Investors May Respond To Norfolk Southern (NSC) Intermodal Partnership Expansion
- Norfolk Southern and Schneider National recently agreed to combine Schneider's 35 years of intermodal expertise and large container and chassis fleet with Norfolk Southern's eastern U.S. rail network and infrastructure projects to expand rail based freight solutions.
- The collaboration links Schneider's more than 60 intermodal hubs and company dray fleet with Norfolk Southern terminals that are being upgraded for better reliability and driver turn times. This development could influence how shippers weigh truckload versus rail for domestic freight.
- This article examines how Norfolk Southern's investment narrative relates to this Schneider intermodal partnership, which is built around assets and network capacity.
Norfolk Southern Investment Narrative Recap
To own Norfolk Southern, you need to believe the rail operator can turn its PSR 2.0 playbook, cost programs and industrial development pipeline into steadier earnings, even with fuel and inflation pushing expenses higher. The Schneider partnership leans into that idea. It adds more containers, chassis and dray capacity to an intermodal franchise that management is already investing behind.
Near term, the key swing factor is whether service reliability and terminal upgrades translate into durable truck to rail conversion and better asset use, especially with intermodal volumes up 3% in the third quarter of 2026. The biggest risk is that higher fuel costs and legal or remediation expenses offset these efficiency gains, leaving the operating ratio under pressure and limiting margin recovery.
The third quarter 2026 earnings print sits closest to this story. Norfolk Southern reported net income of US$759 million, with basic EPS from continuing operations at US$3.38. Over the first nine months of 2026, net income reached US$2.04b, while basic EPS from continuing operations was US$9.07. Those figures give you a concrete base to judge how much the Schneider intermodal agreement can move the needle.
If you care about catalysts, this earnings update links directly to the operational thesis. Intermodal volumes grew 3% in the quarter, and the Schneider deal targets that same lane of truck like reliability paired with rail efficiency. The question is execution: Can Norfolk Southern sustain service gains, absorb higher fuel and any legal costs, and still convert its 22 state network and new terminals into cleaner earnings power per share over the next few years?
Norfolk Southern's analyst story projects revenue of US$14.6b and earnings of US$3.6b by 2029, based on forecast top line growth of 5.1% a year and an earnings increase of about US$1.0b from US$2.6b today.
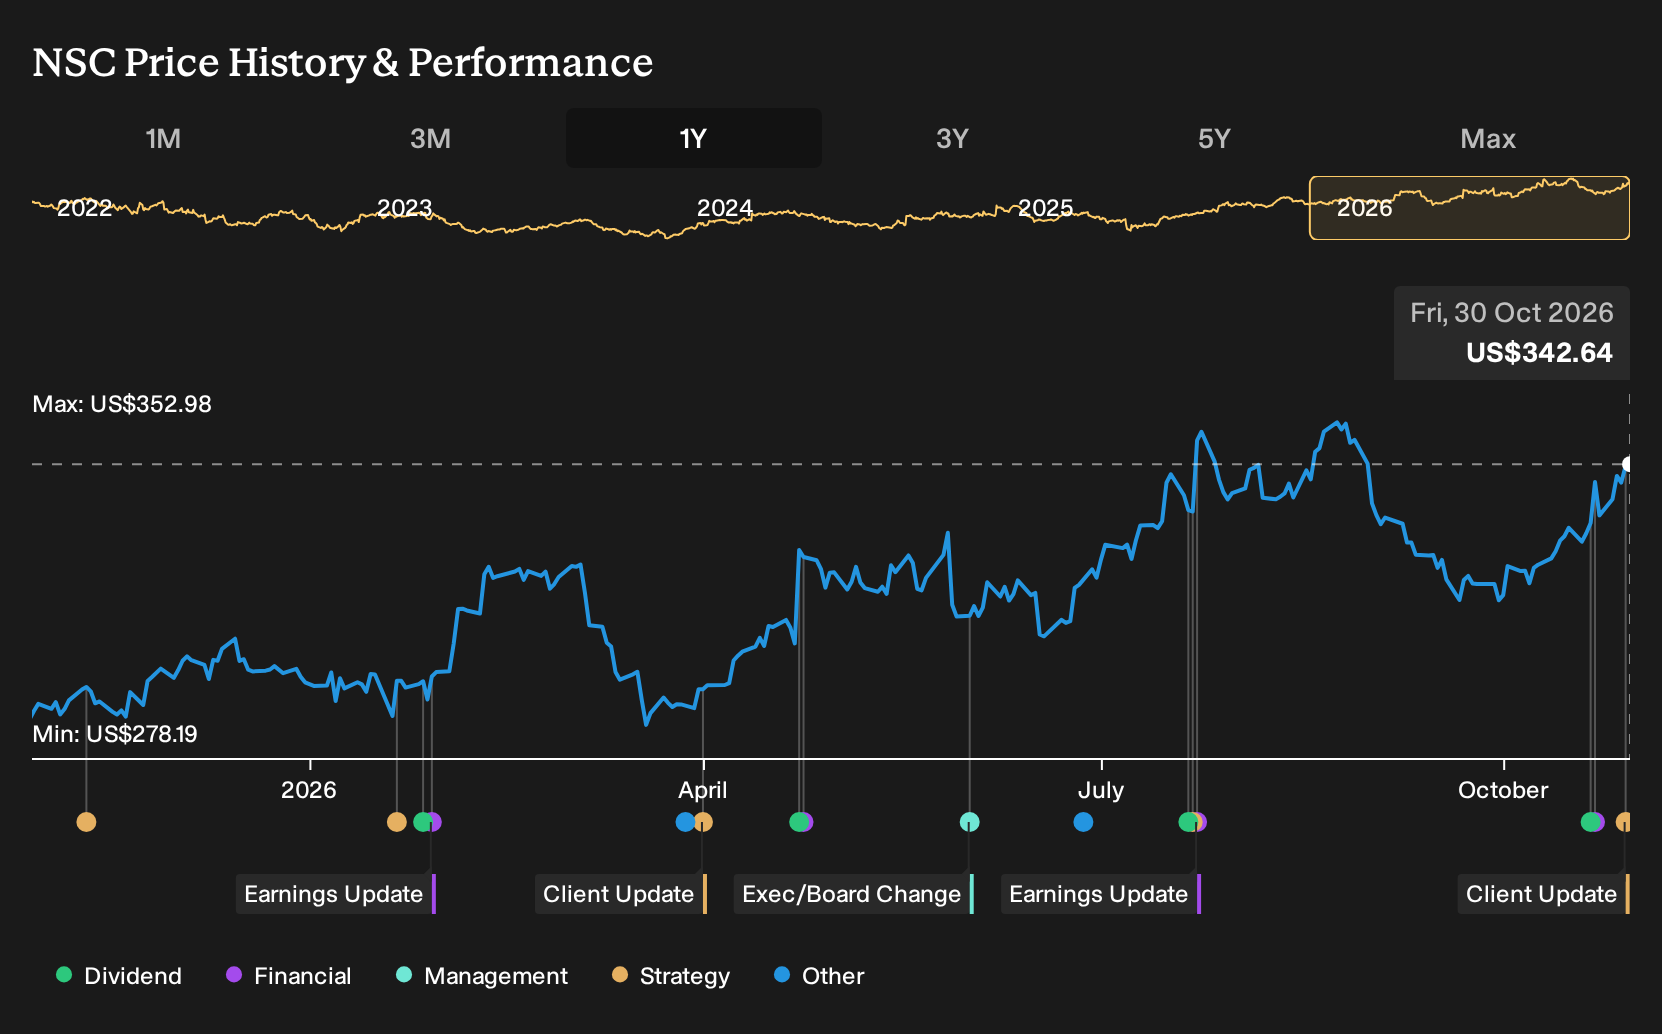
Uncover why Norfolk Southern's fair value indicates a 4% potential upside to its current price before that discount closes.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community sit far apart, from about US$232 to roughly US$356, which already shows how widely opinions on Norfolk Southern can spread. Add higher fuel costs, toxic exposure claims and merger uncertainty, and you have plenty of reasons to compare several competing viewpoints before deciding how this freight story fits your portfolio.
Explore another Norfolk Southern fair value estimate, including one that suggests it could be worth as much as $356.11.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgment.
- A great starting point for your Norfolk Southern research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Norfolk Southern. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Norfolk Southern's overall financial health at a glance.
Looking for more investment ideas beyond Norfolk Southern?
If the Norfolk Southern story has you thinking about portfolio balance, it can help to line it up against other opportunities that share some of the same freight, infrastructure or quality themes. The Simply Wall St Screener lets you filter for specific traits so you can build a watchlist that fits your risk tolerance and income needs.
- For investors who want potential mispricing on their side, review a curated set of companies trading below assessed value with strong fundamentals by scanning 29 high quality undervalued stocks.
- If capital preservation matters just as much as return potential, narrow the field to businesses with more resilient profiles by checking out the 30 resilient stocks with low risk scores.
- Those who care about balance sheets as much as income statements can focus on financially robust operators by running the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com