
Renasant (RNST) Stock Trades At a Discount After Its 59% Run
Renasant has delivered a strong 58.9% share price gain over the past three years, which naturally puts the spotlight on whether the current valuation is supported by the returns the bank earns on its capital. With investors also weighing the impact of a recently announced acquisition, the central question is how much of that performance is backed by the underlying economics of Renasant's lending and deposit franchise.
- The 58.9% move over three years puts real pressure on the numbers to show that Renasant is earning returns on capital that can justify a higher share price than in the recent past.
- The planned purchase of Commercial Holding Company may support future returns on capital if the enlarged Tennessee presence and added scale allow Renasant to deploy capital into loans and services at attractive spreads relative to its funding costs.
- Prefer to judge Renasant on earnings? See why Renasant's 10.8x P/E tells a different valuation story.
The stock's next move may depend on whether the returns Renasant earns on its capital are strong enough to defend the current price tag.
To put Renasant's recent 58.9% three year gain and acquisition plans in context, it can help to compare it with other banks screened for solid balance sheet and fundamentals stocks screener (25 results).
Is Renasant a Bargain on Excess Returns?
The Excess Returns model looks at how much profit Renasant can earn above the return that investors require on its equity. On the latest inputs, Renasant is modeled with Book Value of $42.41 per share and Stable EPS of $4.04 per share, which are both grounded in analyst expectations rather than a simple extrapolation of recent results. With a Cost of Equity of $3.33 per share, the framework points to an Excess Return of $0.71 per share and an Average Return on Equity of 8.77%, implying the bank is expected to earn more on its capital than investors are assumed to demand.
The model also assumes Stable Book Value of $45.99 per share, which reflects estimates from six analysts and suggests ongoing capital formation rather than a shrinking equity base. Because the Excess Returns projections put Renasant's estimated intrinsic value substantially above the current share price of $39.93, the stock screens as priced below what these return assumptions support. The planned acquisition of Commercial Holding Company helps explain why the market might be weighing execution risk even as the model points to value supported by expected returns on capital. Find out what Renasant could be worth using our Excess Returns estimate.
The Renasant Narrative: What Would Justify Today's Price?
Narratives pick up where Renasant's valuation puzzle leaves off, explaining which future paths for growth, profitability and earnings would need to occur for the share price to end up meaningfully higher or lower than it is today. All of this is housed on Simply Wall St's Community page. Rather than stopping at a single model output, the narratives unpack the specific future that figure relies on so you can watch in real time whether those expectations are actually taking shape.
One of the top community narratives on Renasant: 16% undervalued
"The current numbers and capital position, including high institutional ownership and active buybacks, indicate that Renasant’s share price reflects a discount..."
Discover why this Narrative puts Renasant at 16% undervalued.
One more Renasant signal to check before acting
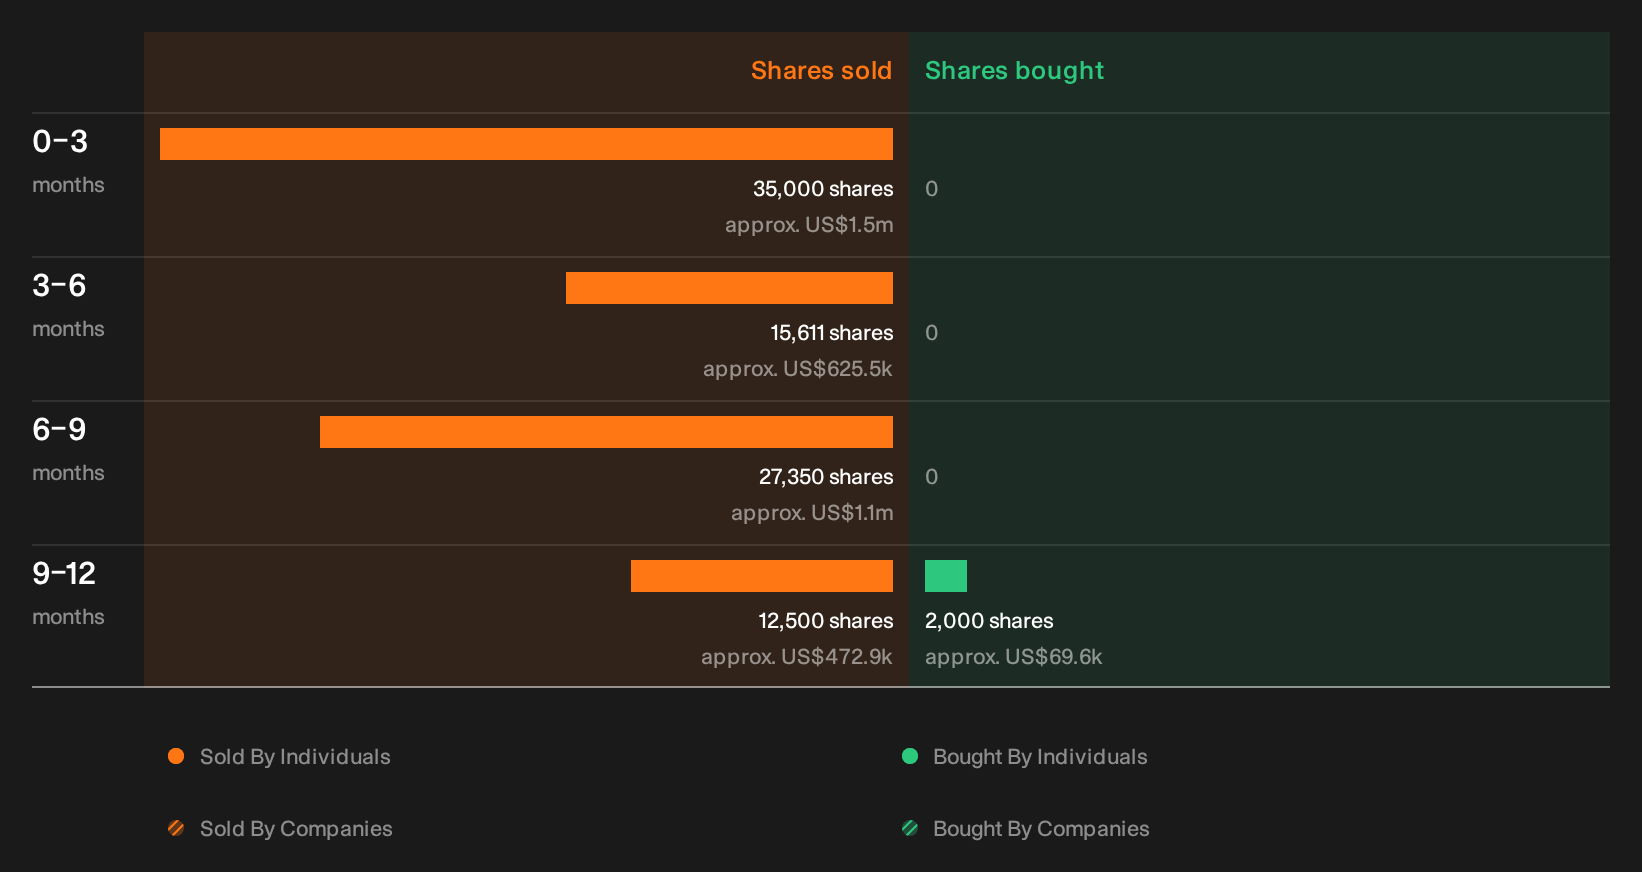
Before you lean too hard on any valuation clue for Renasant, it is worth pausing on the recent share dealing by people inside the business, who sold, how much, and what that pattern might suggest for you to think about. See the recent insider selling flagged for Renasant.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com