
ONE Gas (OGS) Could Be 8% Undervalued Following Its Rate Base Growth Narrative
ONE Gas (OGS) has come back into focus after fresh commentary highlighted its dividend yield, which currently sits above the industry average and is backed by a record of consistent payouts.
Recent trading has been quietly positive for ONE Gas, with a 1 month share price return of 9.28% and a more modest 90 day share price return of 1.15% off the latest close at US$78.54. That short burst of momentum sits alongside a 1 year total shareholder return of 1.22% and a 3 year total shareholder return of 41.03%, which provides a clearer sense of how the dividend and price performance have combined over time.
Scan beyond ONE Gas and line up other regulated utilities with strong balance sheets and dependable cash flows using our curated list of solid balance sheet and fundamentals (25 results) as a starting list.
ONE Gas has the regulated footprint, dividend track record and recent share price bump that income investors often like. The open question is whether that solid profile is already fully reflected in the current US$78.54 price.
Most Popular Narrative: 8% Undervalued
The most followed valuation narrative for ONE Gas pegs fair value at about $85.17, which sits modestly above the recent $78.54 close and frames the current dividend yield against a stock that is seen as slightly mispriced rather than obviously cheap.
The capital intensive system integrity and expansion plan, including roughly US$800 million of 2026 investments and about US$4.3b over five years with projects such as the 43 mile Western Farmers pipeline, is described as increasing the regulated rate base and supporting future net income and EPS as these assets enter service.
See why 0 investors see ONE Gas as 8% undervalued.
Result: Fair Value of $85.17 (UNDERVALUED)
Still, the narrative around ONE Gas could shift if heavy capital spending that relies on external funding reduces free cash flow, or if operating costs remain persistently elevated.
Find out about the key risks to this ONE Gas narrative.
Another View: ONE Gas Through The P/E Lens
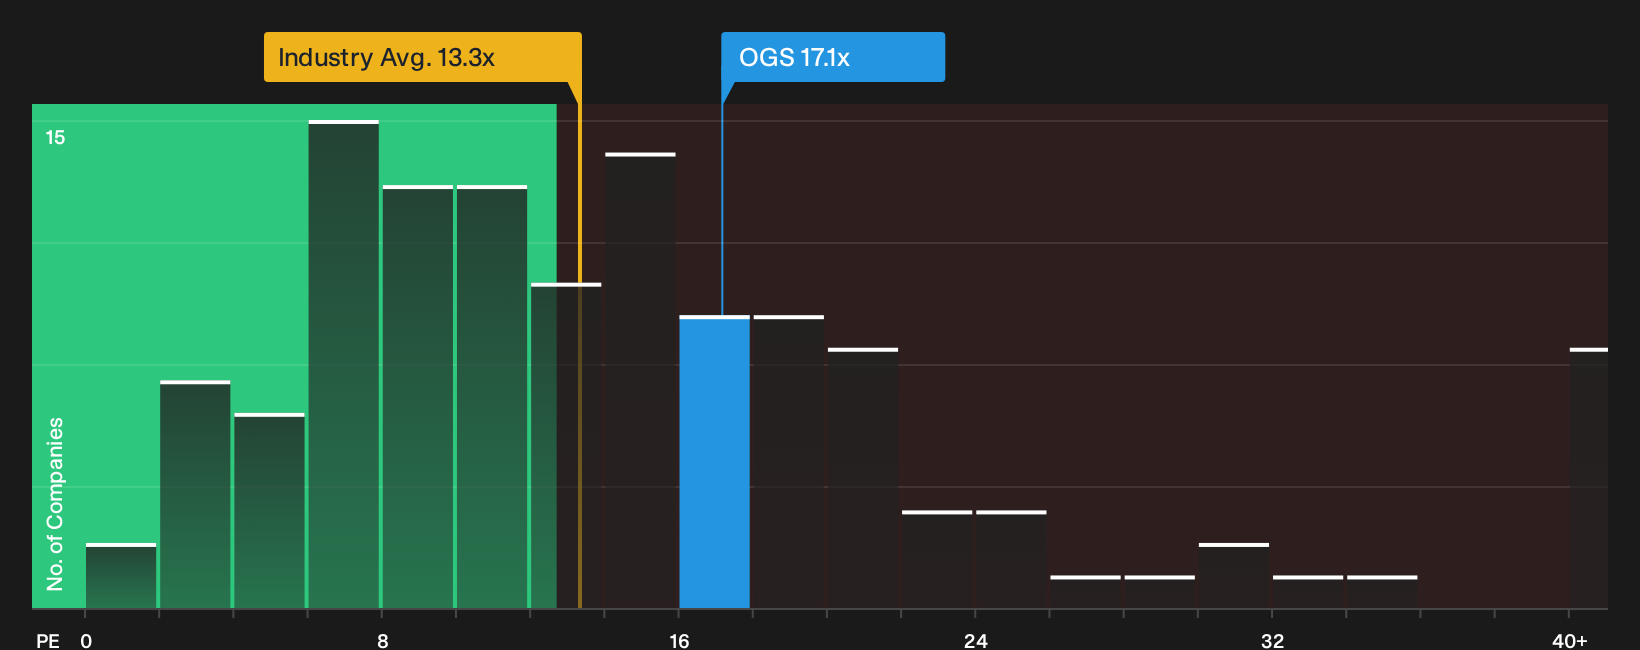
Looking at ONE Gas through its P/E, the picture is less forgiving than the 8% undervalued narrative. The stock trades on 17.1x earnings versus 14.4x for peers and 13.4x for the wider gas utilities group, while the fair ratio is estimated at 17.8x. That narrow gap suggests limited valuation cushion if sentiment weakens. Investors may want to consider how comfortable they are paying a premium for a regulated utility that is already priced close to this fair ratio.
For a closer look at how this pricing compares with fundamentals and peers, start with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on ONE Gas so far. If that tension between risk and reward has you on the fence, now is the time to pull up the numbers directly, pressure test the narratives, and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond ONE Gas?
Do not stop with ONE Gas. Use the Simply Wall Street Screener to uncover fresh opportunities, compare risk profiles, and pressure test your income and value watchlist.
- Target potential bargains that pair quality with attractive pricing by scanning our 29 high quality undervalued stocks before the crowd catches on.
- Strengthen your income stream by zeroing in on companies that aim to combine higher yields with resilient payouts through the 5 dividend fortresses.
- Reduce unpleasant surprises by focusing on companies that score well on financial resilience using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com