
What Guidewire Software Stock Means For Shareholders After Its AI And Cloud Expansion
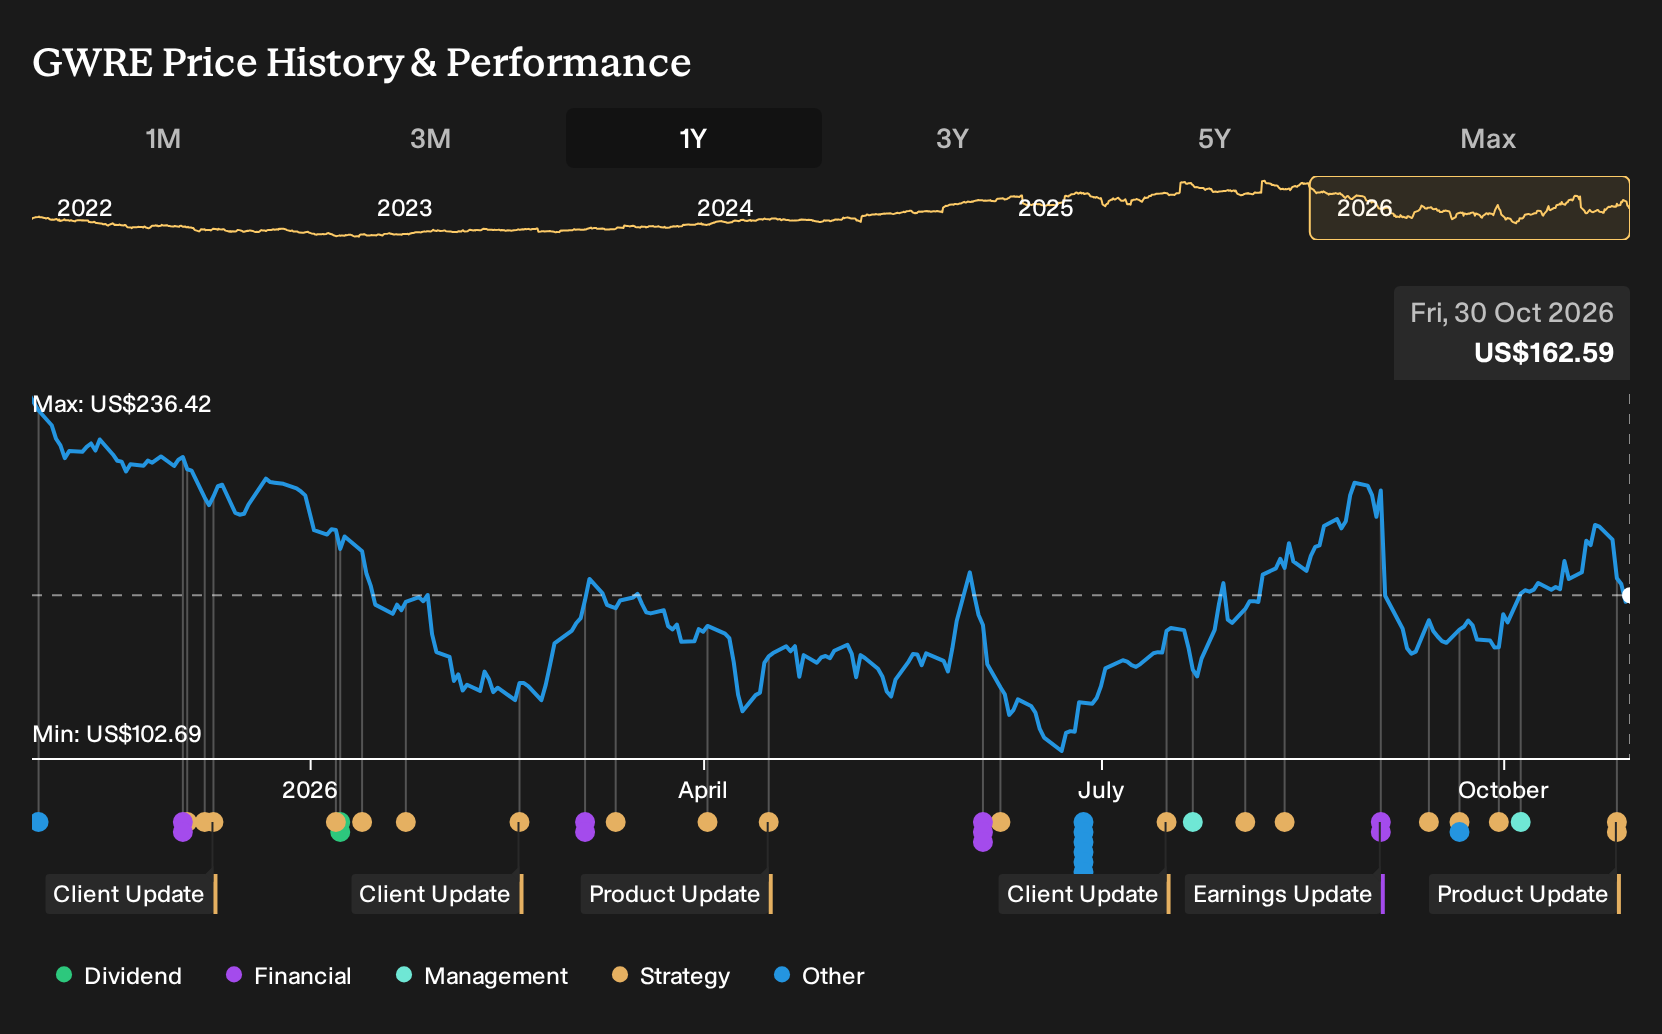
- Guidewire Software recently reported strong quarterly results alongside a new agentic AI insurance platform, expanded cloud products like PricingCenter and ProNavigator, and an agreement to acquire AI underwriting firm hyperexponential.
- The combination of robust recurring revenue metrics, deeper AI driven underwriting tools, and large insurer cloud deals strengthens the link between Guidewire Software’s product roadmap and long term customer spending.
- This article examines how Guidewire Software’s investment narrative is shaped by the new agentic insurance platform and the AI underwriting deal.
Guidewire Software Investment Narrative Recap
For Guidewire Software, the core belief is that property and casualty insurers keep shifting core systems and workloads to Guidewire Cloud and then layer on higher value products. The near term swing factor is how quickly existing customers adopt new AI centric offerings such as the agentic platform, PricingCenter, and ProNavigator to support recurring revenue and margins.
The main risk right now is execution. Insurers could slow IT spending or delay migrations, which would pressure fully ramped ARR and subscription growth. Integrating the new agentic tools and hyperexponential while keeping implementations on time and on budget is where expectations feel most exposed.
The new agentic insurance platform launch is the announcement that really ties this story together. Guidewire Software now pitches a single environment where agents, core policy systems, data, and controls sit on the same cloud foundation. This matters for insurers that want to move past small AI pilots and into governed production workflows.
For catalysts, that platform can influence how much value customers see in migrating more of their stack to Guidewire Cloud and paying for products like PricingCenter, UnderwritingCenter, and ProNavigator. The flip side is straightforward. If customers struggle to operationalise these agents or worry about cost, that could slow ARR per customer growth and cloud expansion.
Guidewire Software's current analyst narrative points to revenues of US$2.3b and earnings of US$359.7 million by 2029, reflecting forecast revenue growth of 15.7% a year and an earnings increase of about 2.6x from US$139.3 million today.
Uncover why Guidewire Software's fair value indicates a 31% potential upside to its current price, which could narrow quickly if sentiment around Guidewire Software shifts.
Exploring Other Perspectives
Some of the most optimistic analysts framed Guidewire Software’s risk very differently. They focused on whether the new agentic platform and hyperexponential deals eventually justify earlier high bar forecasts such as US$2.5b in 2029 revenue and US$434.5 million in earnings. Those projections pre date this launch, so opinions may shift as investors compare alternative views.
Explore 3 other Guidewire Software fair value estimates, including one that suggests potential upside of up to 57% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Guidewire Software research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Guidewire Software. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Guidewire Software's overall financial health at a glance.
Looking for more investment ideas beyond Guidewire Software?
Once you understand where Guidewire Software might fit in your portfolio, it can help to scan a wider field of opportunities using focused stock lists built around specific strengths.
- If you want potential upside with stronger fundamentals than the usual micro caps, take a look at 9 elite penny stocks with strong financials that pair smaller market values with healthier balance sheets and cash flows.
- For investors who care most about paying less for quality, start with a curated pool of 29 high quality undervalued stocks that combine solid financial profiles with lower implied expectations.
- When capital preservation sits at the top of your checklist, consider a filtered group of 30 resilient stocks with low risk scores screened for more resilient financial metrics and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com