
Simplex Holdings (TSE:4373) Revised Its Outlook After Half Year Results, Is The Premium Justified?
Simplex Holdings (TSE:4373) moved into focus after reporting half-year results to September 30, 2026, alongside a board decision to revise its full-year forecast, giving investors fresh data on earnings momentum.
Recent trading has been choppy for Simplex Holdings, with a 7.46% 7 day share price pullback even after a 0.78% gain on the latest session to ¥1,166. However, the 30 day share price return of 5.23% and year to date move of 13.65% suggest underlying momentum is still positive. That short term wobble sits against a much stronger backdrop, with total shareholder return of 10.92% over 1 year and more than double over 3 years, as the market reacts to the latest half year figures and the board’s forecast revision as signals about both growth potential and risk.
Scan Simplex Holdings alongside other IT and software-focused plays that are showing earnings momentum and forecast revisions in our hand picked 71 high quality undiscovered gems.
Simplex Holdings is clearly building a solid IT solutions franchise in Japan, yet the latest swing in the share price raises a sharper issue. Are you paying a fair price for that strength right now or stretching it?
Price-to-Earnings of 24.8x: Is it justified?
On the latest figures, Simplex Holdings trades on a P/E of 24.8x, which puts a clear premium on the current ¥1,166 share price compared with both its peers and the wider JP IT sector.
The P/E ratio compares what investors are paying today for each unit of earnings the business generates. For an IT solutions provider like Simplex Holdings, this measure often reflects how much the market is willing to pay for its earnings profile in areas such as consulting, subscription services, and software licensing.
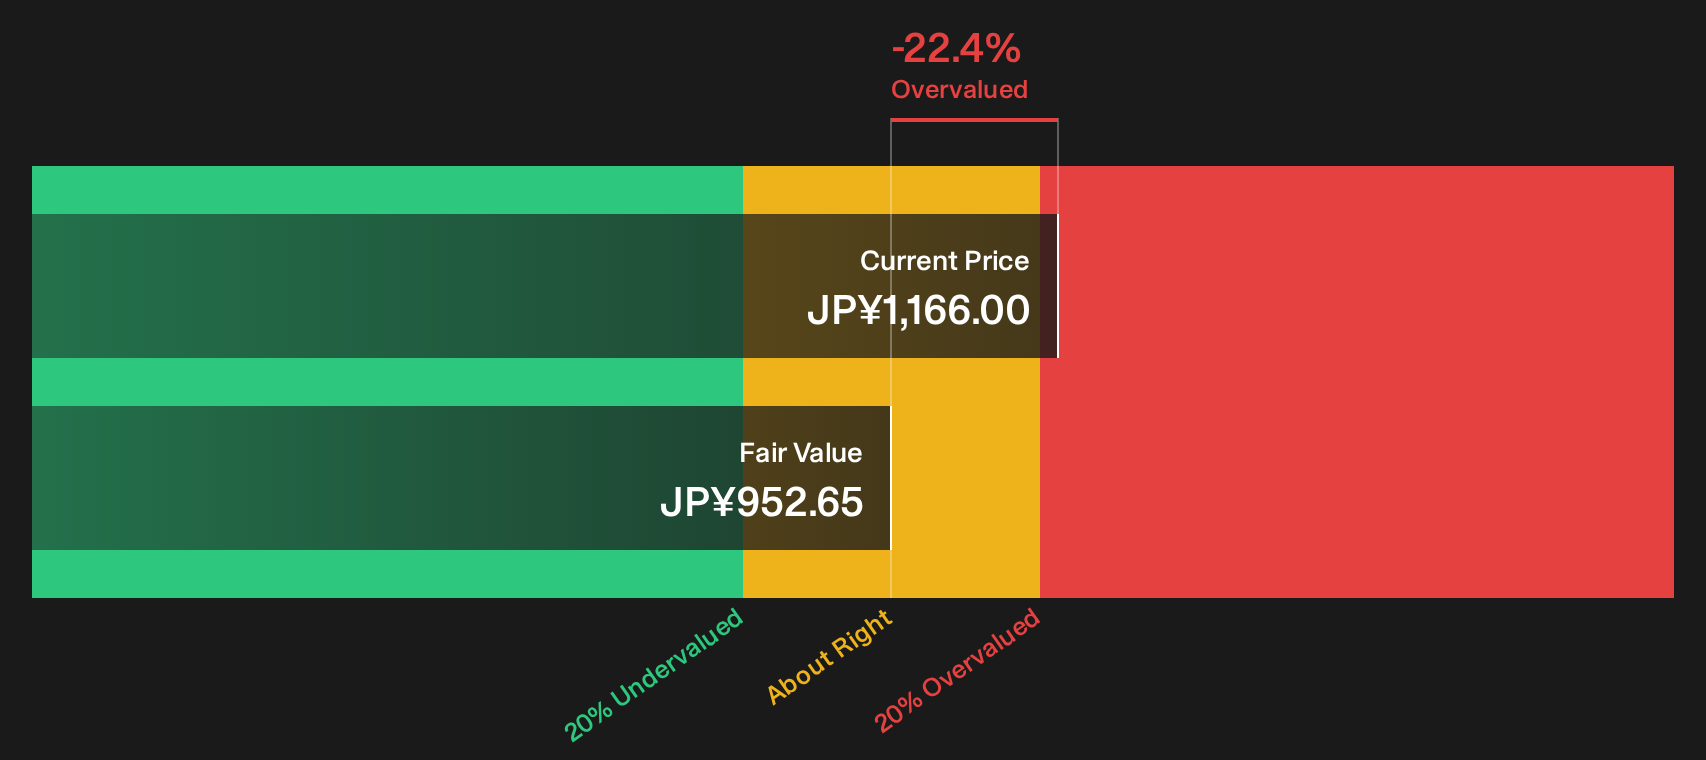
Analyst forecasts point to earnings growth of 15.9% a year and revenue growth of 13% a year, which is quicker than the broader JP market but below the 20% threshold often associated with high growth. That combination suggests the current earnings premium is pricing in solid progress rather than aggressive expansion, while the SWS DCF model points to a future cash flow value of ¥952.65, which is below the latest close.
The gap becomes sharper when you line Simplex Holdings up against its reference points. The JP IT industry sits at a P/E of 16.1x and the peer average is 22.8x, so the stock carries a higher earnings multiple than both the sector and immediate comparables. At the same time, the estimated fair P/E ratio is also 24.8x, which signals the current earnings-based valuation is already at the level the market could move towards rather than below it.
Explore the SWS fair ratio for Simplex Holdings.
Result: Price-to-Earnings of 24.8x (OVERVALUED)
Still, the Simplex Holdings story can be knocked off course if earnings growth underwhelms against that 24.8x P/E, or if valuation multiples compress further.
Find out about the key risks to this Simplex Holdings narrative.
Another view on Simplex Holdings’ value
The earnings multiple paints Simplex Holdings as fully priced, yet the SWS DCF model tells a different story. On that cash flow view, an estimated value of ¥952.65 sits below the current ¥1,166 share price, which screens as overvalued. So how much weight do you want to put on growth translating cleanly into cash over time?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Simplex Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Simplex Holdings is mixed, which is exactly when it pays to inspect the numbers yourself and pressure test the story. If you want a quick read on what the market sees as the bright spots, start with the 3 key rewards.
Looking for more investment ideas beyond Simplex Holdings?
Do not stop your research with Simplex Holdings. Broaden your watchlist with fresh ideas that could fit different roles in your portfolio.
- Target potential mispricings by scanning companies that combine quality fundamentals with attractive valuations through the 15 high quality undervalued stocks.
- Strengthen your income focus by reviewing stocks with higher yields and resilient cash flows using the 27 dividend fortresses.
- Lower portfolio stress by concentrating on companies that carry sturdier finances and cleaner balance sheets via the list of solid balance sheet and fundamentals (22 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com