
Is Emerson Electric (EMR) Fairly Valued As Earnings Expectations Rise?
Emerson Electric (EMR) is back in focus after Wall Street analysts lifted their earnings expectations for the upcoming quarter, citing higher consensus EPS forecasts and anticipated net sales changes across several business segments.
Recent trading captures that shift in sentiment. Emerson Electric’s share price has climbed 6.34% over the past 30 days and 21.44% year to date, while total shareholder return sits at 20.03% over one year and close to 89.06% across three years. This suggests that momentum has been building rather than fading as earnings expectations improve.
Scan beyond Emerson Electric and identify other industrials with building momentum using the curated 39 power grid technology and infrastructure stocks as a starting point for your next ideas.
Emerson Electric looks like a solid industrial platform, with rising expectations already baked into the share price after its recent run. The real test now is whether that quality is being overpaid for or not.
Most Popular Narrative: 5% Undervalued
On the most followed view, Emerson Electric is worth $173.68 a share, compared with the last close at $164.94, which frames the recent rally as only part of the story rather than the end of it.
Large-scale investments in power generation, LNG and life sciences driven by rising energy security concerns, electrification and sustainability initiatives are driving significant greenfield and modernization projects in regions such as North America, Asia and the Middle East. This is visible in the growth in power orders, the expansion of the power project funnel to about US$3b and the US$2.2b LNG funnel, and could support revenue and operating margin resilience.
See why 60 investors see Emerson Electric as 5% undervalued.
Result: Fair Value of $173.68 (UNDERVALUED)
Still, conflict-related disruption in the Middle East and softer demand in China could slow Emerson Electric project execution and challenge the most optimistic earnings path.
Find out about the key risks to this Emerson Electric narrative.
Another View: What Emerson Electric’s P/E Says
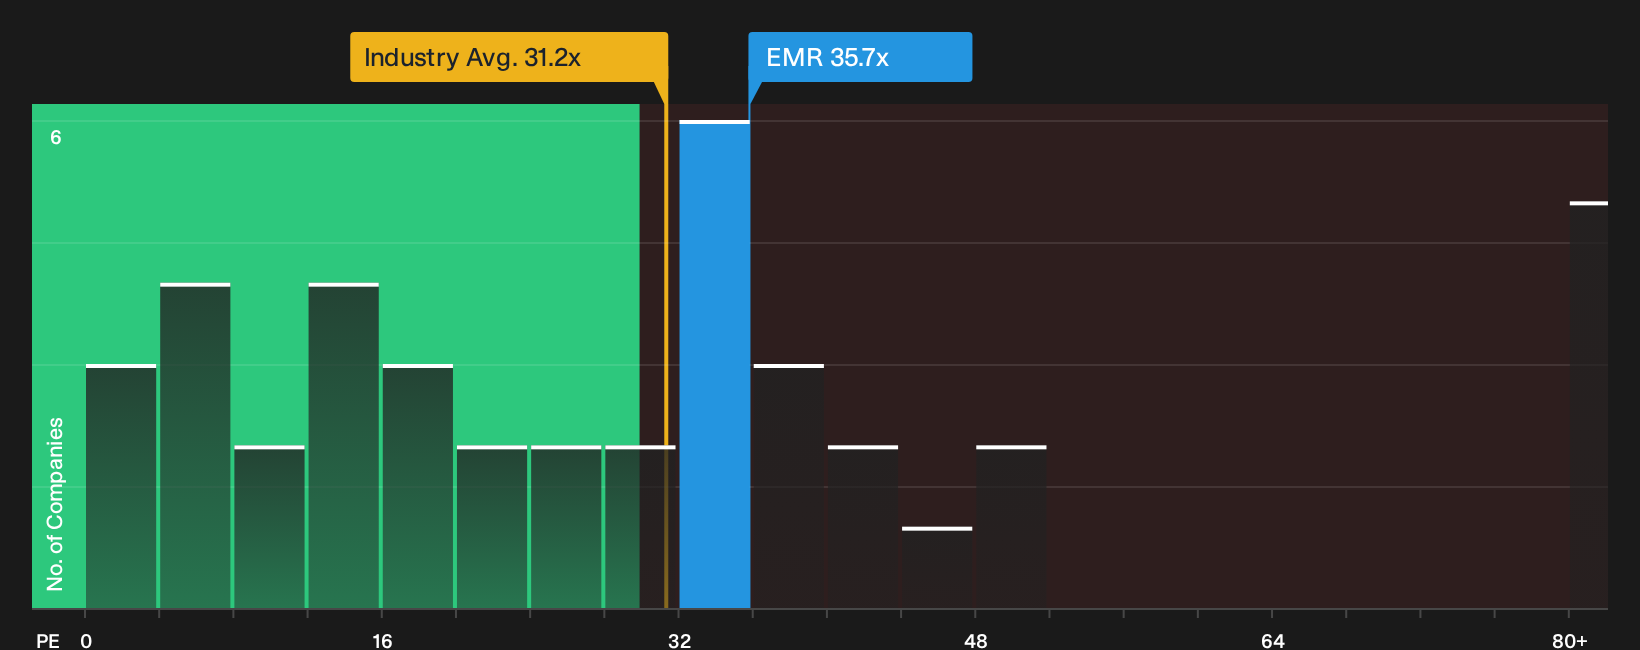
The SWS fair ratio work paints a tighter picture. Emerson Electric trades on a P/E of 35.7x, while the fair ratio is 29.5x, above both that mark and the US Electrical sector on 31.2x. That points to valuation risk rather than a clear bargain. Which signal do you put more weight on?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Emerson Electric’s valuation story. That is the signal so far, and it is your cue to dig into the details and stress test both the upside case and the concerns by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Emerson Electric?
Do not stop your research with Emerson Electric. Broaden your watchlist now so you can spot strong opportunities before they move out of reach.
- Target stronger balance sheets and steadier financial profiles by running the list of solid balance sheet and fundamentals (25 results) that filters for robustness first.
- Hunt for potential mispricings by checking the 29 high quality undervalued stocks that focuses on quality fundamentals paired with lower implied expectations.
- Build an income focused shortlist by reviewing the 5 dividend fortresses to see which higher yielding payers still screen for resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com