
Terex (TEX) Beat In Q3, Is The Stock Still A Bargain?
Why Terex Stock Is Back In Focus After Q3 2026
Terex (TEX) grabbed fresh attention after its third quarter 2026 earnings release, a refined full year sales outlook of US$8.0b to US$8.2b, and approval of a US$500 million share repurchase plan.
The share price reaction has been mixed. Terex trades at US$56.15 after a 9.48% 7 day share price return and a 6.75% 30 day gain, yet the 90 day share price return is down 10.65% while the 1 year total shareholder return is 23.45%. This suggests longer term holders have still been rewarded as recent earnings, guidance and the new buyback reset expectations.
Scan how Terex compares with other capital goods players reacting to earnings, guidance and buybacks by running through our hand picked list of 39 power grid technology and infrastructure stocks
Terex has bounced on strong Q3 figures and a fresh US$500 million buyback, so the real question now is whether most of the opportunity is already priced in or if value still lies ahead. The valuation work starts at this point.
Most Popular Narrative: 30% Undervalued
Terex is trading at $56.15 against a widely followed fair value estimate of $79.94, so the current setup hinges on whether the business can align with the growth and margin profile implied by that gap.
The shift toward a more North America centric specialty equipment mix, with over 80% of pro forma 2025 revenue now in North America and a large share tied to municipal and utility markets, together with industry forecasts of 8% to 15% annual U.S. utility CapEx growth through 2030 and a planned 20% to 30% Utilities capacity expansion, positions Terex to capture multi year demand for grid and infrastructure equipment that could support revenue and earnings.
See why 13 investors see Terex as 30% undervalued.
Result: Fair Value of $79.94 (UNDERVALUED)
Still, the Terex story can crack if margin execution stumbles again, or if Environmental Solutions delivers softer growth and profitability than the narrative assumes.
Find out about the key risks to this Terex narrative.
Another View: What Terex’s P/E Is Telling You
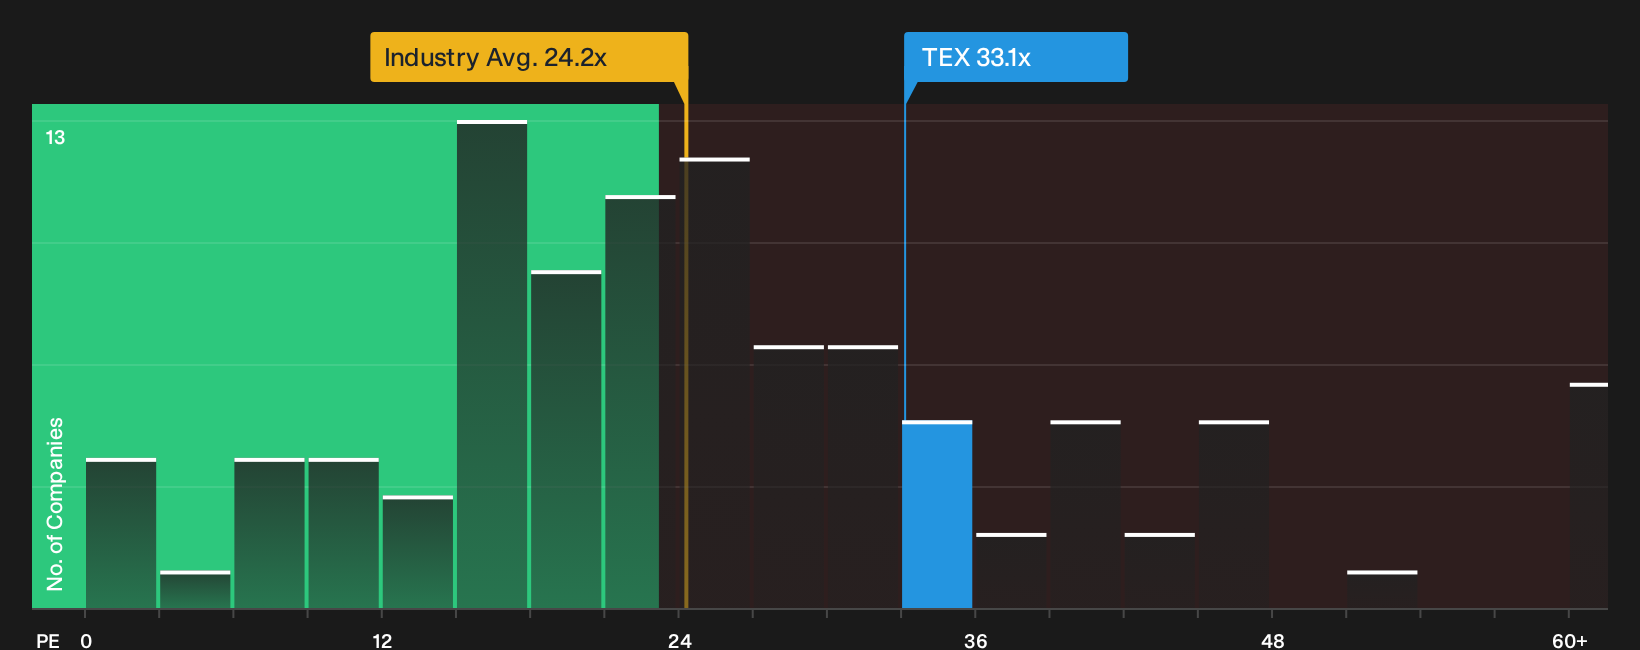
The first narrative leans on fair value of $79.94, yet Terex currently trades on a P/E of 33.1x. That is richer than both the US Machinery industry at 24.8x and its peer average of 18.6x, even though the fair ratio sits higher at 62.3x. This raises the question of whether the market is already baking in a lot of good news, or whether this pricing still leaves room for upside if the story plays out.
For a closer look at what this valuation gap might mean in practice, and how it could shift if sentiment turns, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Terex so far and plenty of opinions flying around. If you want to move quickly and build your own conviction from the full picture of concerns and potential upsides, start with the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Terex?
If Terex has your attention, round out your watchlist by scanning other opportunities where valuations, balance sheets and income potential tell a different story.
- Zero in on proven quality and potential mispricing by sorting through a curated 29 high quality undervalued stocks that filters for stronger fundamentals and appealing valuation signals.
- Strengthen the foundation of your portfolio by using the list of solid balance sheet and fundamentals (25 results) to focus on businesses with sturdier finances and fewer balance sheet red flags.
- Hunt for underfollowed potential by reviewing a targeted 18 high quality undiscovered gems that highlights companies with strong metrics but limited current market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com