
Kohl's (KSS) Launches Holiday Offers And Refreshes Its Board, Is The Upside Already Priced In?
Kohl's (KSS) is back in focus after rolling out a packed holiday playbook built around Black Friday Early Access, Sephora at Kohl's promotions, and budget friendly gift tiers across key categories.
The holiday push and board refresh have arrived against a backdrop where momentum in Kohl's share price has picked up. After a 30 day share price return of 31.69% and a 90 day share price return of 27.01%, the retailer now sits at US$24.31. The 1 year total shareholder return of 53.94% contrasts with a weaker 5 year total shareholder return of 42.91%, highlighting a difference between recent performance and longer-term results that may be influencing how investors view both its prospects and risks.
Explore how Kohl's renewed momentum compares with other value-focused retailers by checking the hand picked 29 high quality undervalued stocks that feature stronger balance sheets and cash flow support.
For Kohl's, a 54% one year shareholder return against a weaker five year record raises a simple tension. Are investors finally reassessing the underlying business, or has sentiment simply shifted in response to the recent holiday results and board-related headlines?
Most Popular Narrative: 30% Overvalued
On the most followed view, Kohl's fair value sits at $18.73, well below the recent $24.31 close. This puts the holiday driven rally against a more cautious long range valuation built on flat sales and tight margins.
Expanded coupon eligibility and sharper pricing aimed at presenting Kohl's as a value option for constrained households increase the risk that heavier promotions become embedded in the model. This can cap gross margin progress even as proprietary brands and inventory discipline aim to support net margins.
See why 27 investors see Kohl's as 30% overvalued.
Result: Fair Value of $18.73 (OVERVALUED)
Still, if Sephora at Kohl's continues to affect roughly 10% of sales or if store traffic drifts lower again, that overvaluation narrative could unravel quickly.
Find out about the key risks to this Kohl's narrative.
Another View On Kohl's Valuation
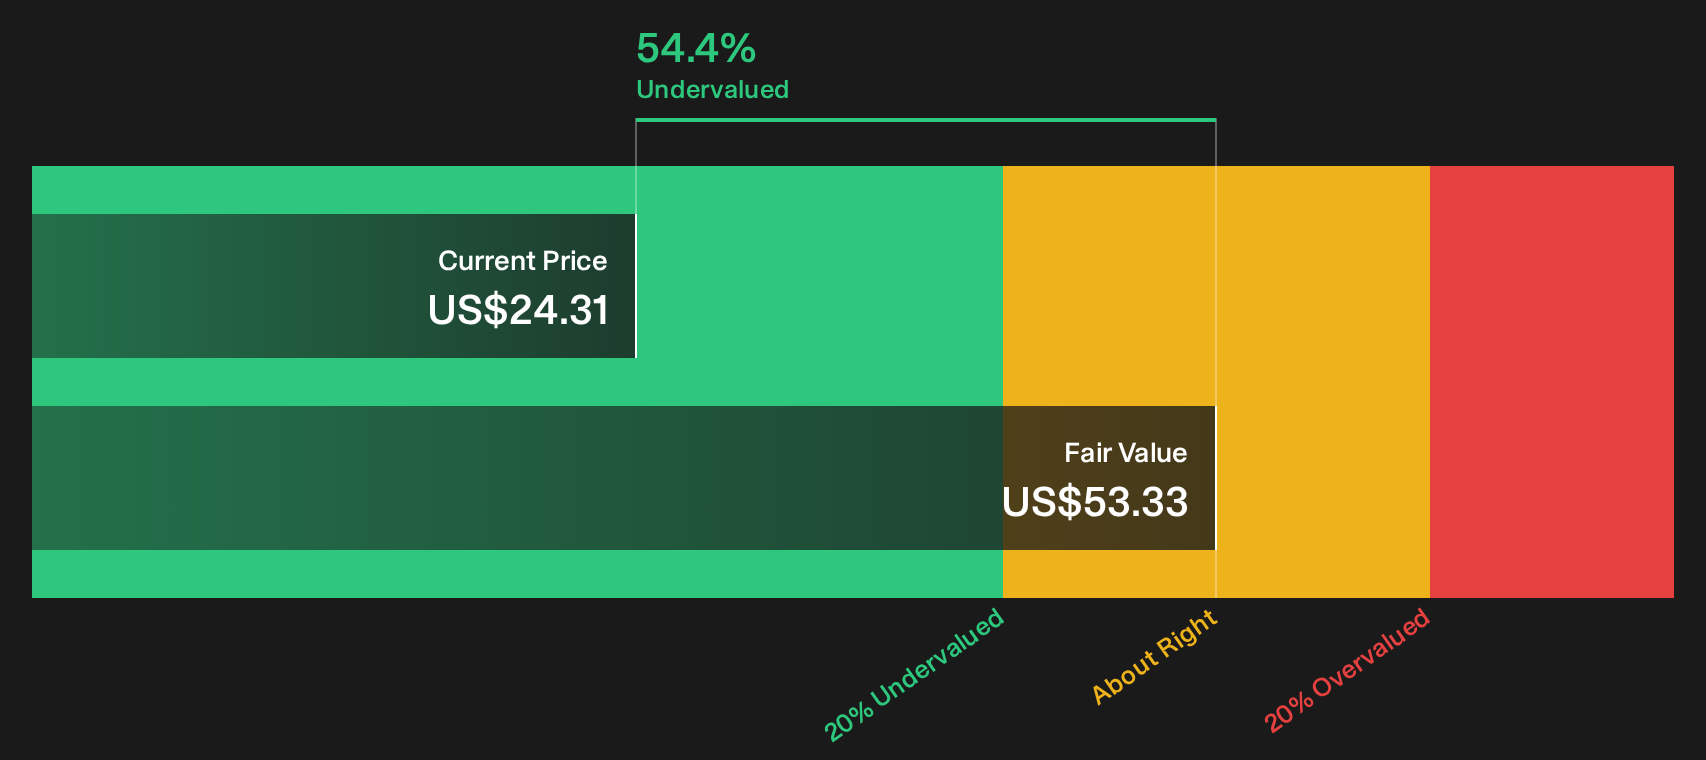
A different lens tells a very different story. On Simply Wall St's DCF model, Kohl's estimated future cash flows point to a fair value of $53.33, which is well above the current $24.31 price. That clashes directly with the $18.73 analyst consensus and raises the question of which framework deserves more weight.
Before leaning too hard on either signal, it helps to see how this cash flow view is built and what would need to hold true for it to remain valid over time. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed views on Kohl's valuation and business quality are clear. Move quickly, test the data yourself, and weigh both the upside and the downside using our 3 key rewards and 2 important warning signs
Looking for more ideas beyond Kohl's?
If Kohl's has sharpened your focus on valuation and quality, do not stop here. Use carefully built filters to surface other opportunities that fit your checklist.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) that may better match your comfort with financial strength.
- Hunt for potential value setups by reviewing the 29 high quality undervalued stocks that combine quality traits with prices that differ from their estimated worth.
- Spot under followed stories before they hit the spotlight by working through the 18 high quality undiscovered gems that already clear basic quality hurdles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com