
Should Raised EPS Outlook Require Action From Flowserve (FLS) Investors?
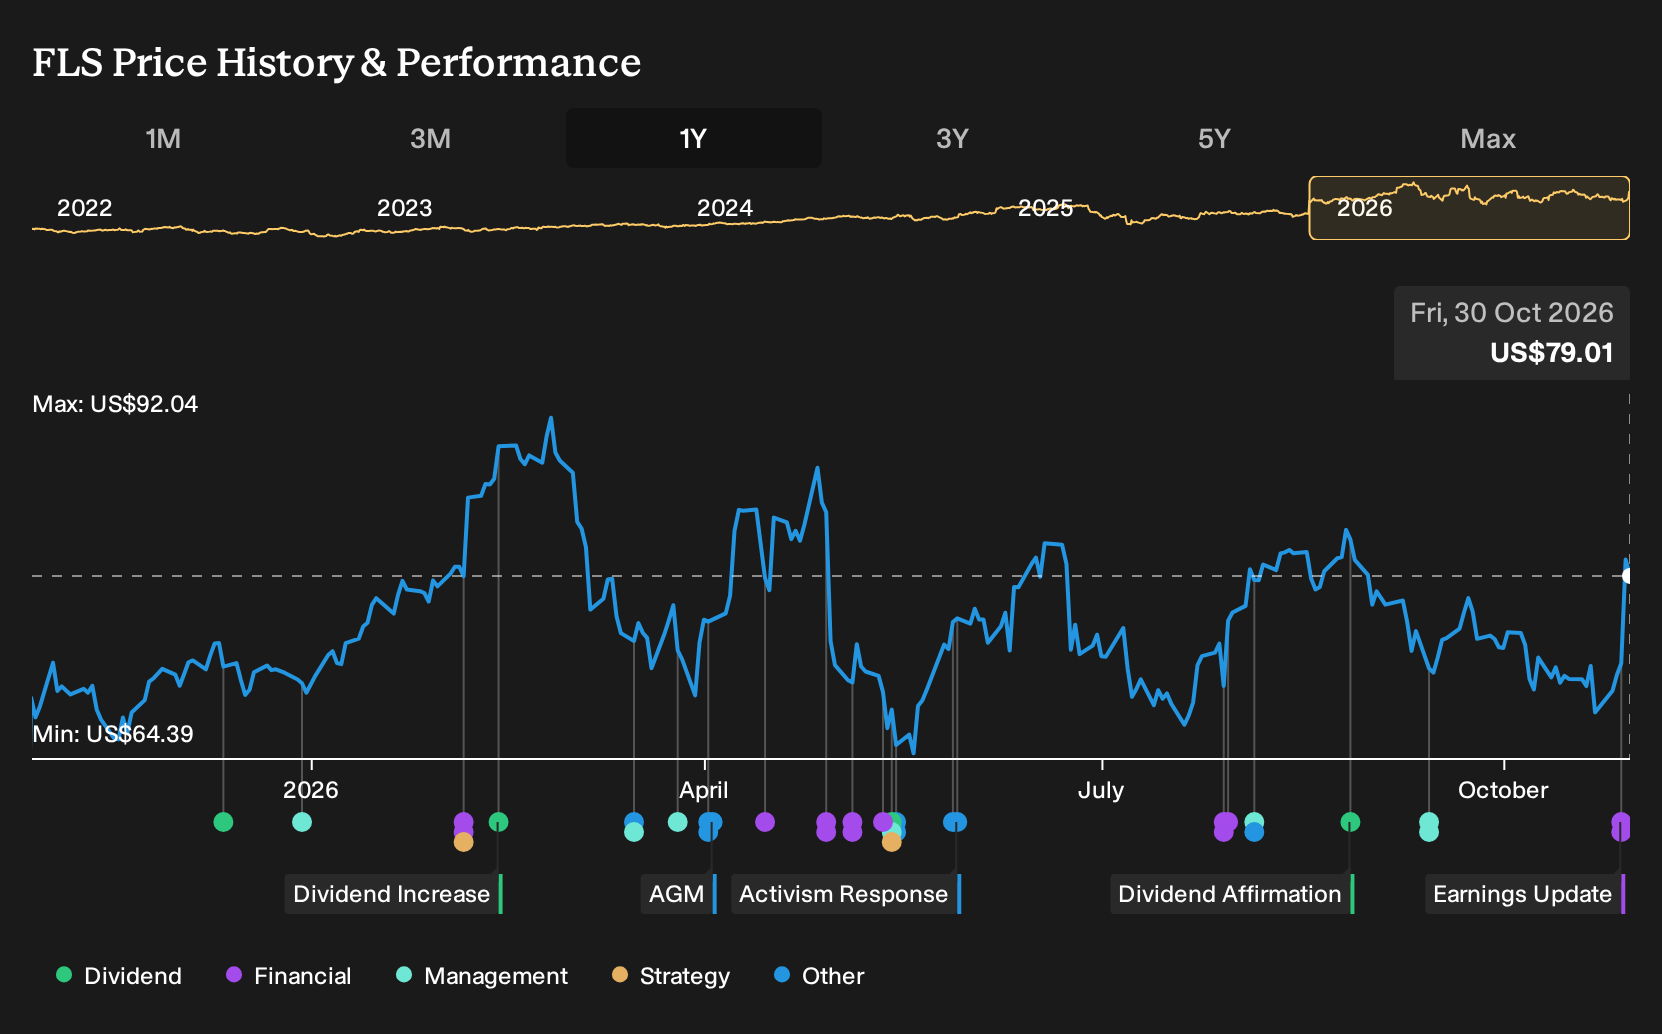
- Flowserve reported Q3 2026 sales of US$1,237.77 million and net income of US$103.04 million, alongside record bookings, margin expansion and a higher full year adjusted EPS outlook, despite lowered sales guidance tied to Middle East project delays.
- The business combined tighter execution, including cost and portfolio work, with an expanded share repurchase authorization to US$500 million, signaling confidence in earnings durability even as regional disruption pushed management to trim 2026 sales expectations.
- We will now look at how Flowserve's higher adjusted EPS guidance, despite Middle East delays, could reshape its investment narrative.
Scan beyond Flowserve and line up other infrastructure related plays that score well on balance sheet strength and fundamentals with this curated list: list of solid balance sheet and fundamentals (25 results).
Flowserve Investment Narrative Recap
To own Flowserve, you need to believe the margin work, aftermarket expansion and power and nuclear exposure matter more than short term swings in project timing. The key near term catalyst is execution on that record US$3.5b backlog and the ability to keep converting bookings into higher profitability despite pockets of disruption.
The biggest current risk sits in the Middle East project delays, which are already affecting activity and fourth quarter sales expectations. Recent Q3 results, with softer reported net income and lowered sales guidance, underline that regional issues are real but do not appear to alter management’s focus on earnings quality and margin progress.
The most relevant update here is Flowserve’s move to raise full year adjusted EPS guidance while slightly trimming 2026 sales growth expectations tied to Middle East delays. That pairing puts execution squarely in focus. It shifts attention from pure top line growth to whether cost actions, mix and backlog quality can support earnings delivery.
For you as an investor, that announcement links directly to the main catalysts analysts have highlighted. The Flowserve Business System, ongoing aftermarket strength and added valve exposure from Trillium all feed into the earnings outlook that underpins that higher adjusted EPS range. The risk is straightforward: if those levers underperform, the earnings bridge becomes harder to sustain.
Flowserve's narrative projects US$5.6b revenue and US$737.9 million earnings by 2029. That path assumes 6.5% yearly revenue growth and an earnings increase of about US$366.6 million from US$371.3 million today.
Uncover how Flowserve's fair value indicates a 13% potential upside to its current price before Flowserve's discount and reality move closer together.
Exploring Other Perspectives
One bullish angle on Flowserve leans heavily on free cash flow. The most optimistic analysts were banking on about US$5.8b of revenue and roughly US$738.2 million of earnings by 2029, with around 90% cash conversion. It is easy to see how that upbeat cash story might be reconsidered after this guidance cut, so it makes sense to explore several viewpoints before deciding where you land.
Explore 4 other Flowserve fair value estimates, including one that suggests as much as 34% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Flowserve research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Flowserve. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Flowserve's overall financial health at a glance.
Looking For More Ideas Beyond Flowserve?
If the Flowserve story has sharpened your thinking, use that same lens across the wider market and line up other candidates that fit your risk, income and quality preferences.
- For investors who want potential upside with strict quality filters, scan a 18 high quality undiscovered gems that pair solid fundamentals with less crowded ownership.
- If capital preservation sits high on your list, focus on a 30 resilient stocks with low risk scores that score well on resilience and downside protection.
- For those building a watchlist around income and stability, filter for a 5 dividend fortresses that combines higher yields with consistent fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com