
2% Overvalued HCA Healthcare (HCA) On Q3 Revenue Beat And Reaffirmed Guidance
HCA Healthcare (HCA) has just put a fresh marker down for investors, pairing a third quarter revenue beat with reaffirmed full year guidance and detailed commentary on payer mix and elective procedure pressures.
Recent trading has been choppy for HCA Healthcare, with the share price slipping 1-day yet still delivering a 10.88% 30-day share price return and a 17.54% 90-day move. The 3-year total shareholder return of 109.73% and 5-year total shareholder return of 98.75% show how the stock has rewarded patient investors as dividends, buybacks and price gains compound around these latest earnings, dividend and repurchase announcements.
Scan how HCA Healthcare stacks up alongside other hospital and healthcare operators by reviewing our curated list of list of solid balance sheet and fundamentals (25 results)
After a sharp multi month rally and fresh buybacks, HCA Healthcare now asks a simple question of investors: Does the current valuation still leave enough upside to justify the operating and policy risks?
Most Popular Narrative: 2% Overvalued
On the most followed narrative, HCA Healthcare screens as modestly overvalued, with a fair value of about $461.81 against a last close of $473.19, so the current price already bakes in a fair amount of execution on volume, cost control and capital deployment.
The main thing that has to go right is that HCA Healthcare continues to offset payer mix and coverage headwinds, including health insurance exchange and Medicaid shifts, with its cost program, capital deployment and growing ambulatory network.
The current view that HCA Healthcare is fairly valued and bullish implies that the share price already reflects steady delivery on the 4 to 6% long-term revenue and EBITDA growth algorithm alongside sustained shareholder returns.
See why 35 investors see HCA Healthcare as 2% overvalued.
Result: Fair Value of $461.81 (OVERVALUED)
Still, pressure from weaker elective surgery volumes and a tougher payer mix, including shifts in Medicaid and exchange coverage, could challenge that consensus view.
Find out about the key risks to this HCA Healthcare narrative.
Another View: HCA Healthcare On Earnings Multiples
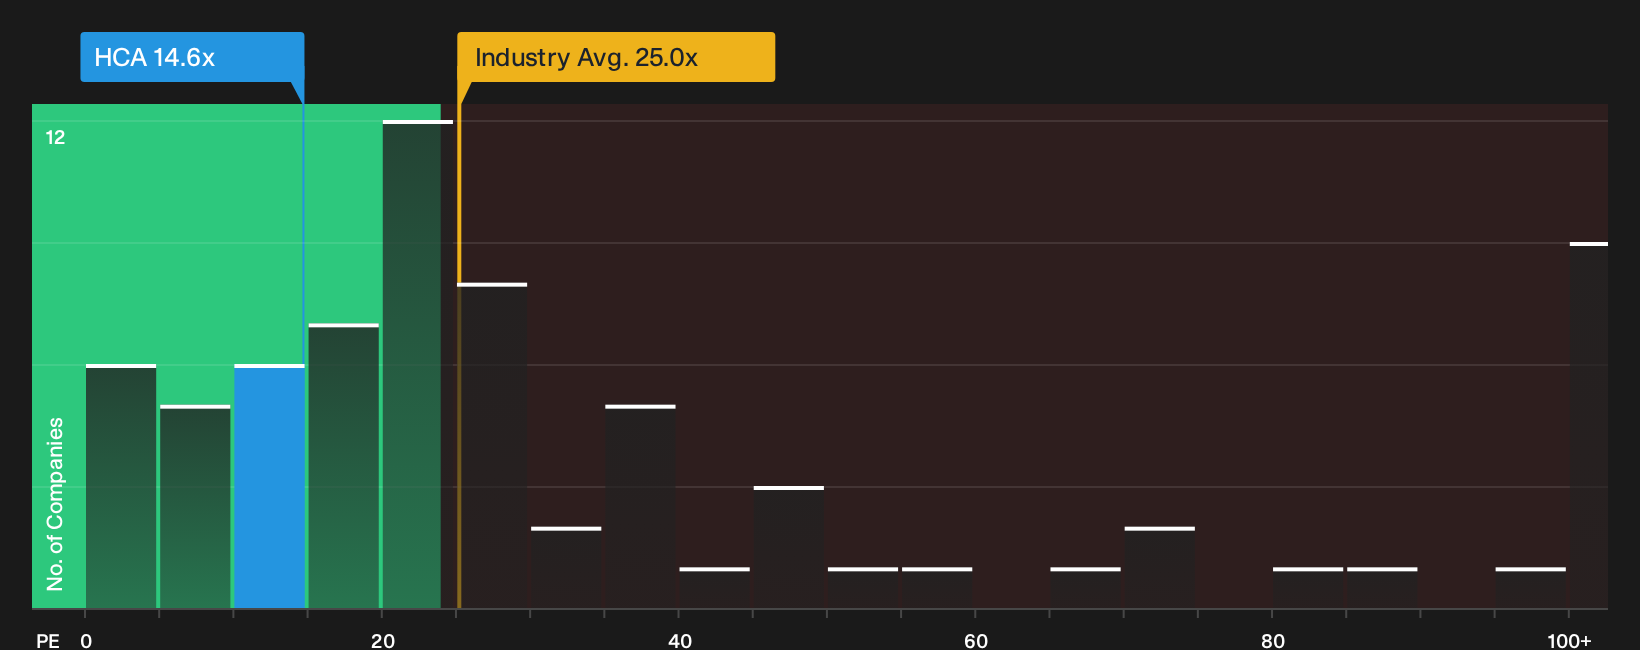
Analysts call HCA Healthcare 2% overvalued on a fair value of $461.81, yet the stock trades on a P/E of 14.6x versus a Healthcare industry average of 25x and a fair ratio of 26.9x. That gap suggests the market could shift a long way before valuations converge, so which signal do you trust more right now?
For a deeper look at how those earnings ratios stack up against peers, check the valuation breakdown and see what the numbers imply for risk and opportunity See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the HCA Healthcare story so far. Act while the details are fresh and weigh the upside against the red flags using the 3 key rewards and 2 important warning signs.
Looking for more HCA Healthcare investment ideas?
If you only stop with HCA Healthcare, you could miss other opportunities that fit your style. Put a few minutes into lining up your next candidates.
- Target dependable income streams by scanning companies that aim to pay robust yields and protect capital through the 5 dividend fortresses.
- Hunt for quality at a discount using the 29 high quality undervalued stocks to spot financially sound businesses the market may be overlooking.
- Stack your watchlist with resilient candidates by focusing on companies that carry sturdier finances and steadier risk profiles via the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com