
Did Stronger Quarterly Earnings Just Shift Community Financial System's (CBU) Investment Narrative?
- Community Financial System reported third quarter 2026 net interest income of US$143.54 million and net income of US$61.3 million, with basic earnings per share from continuing operations of US$1.16, along with higher net charge offs and continued share repurchases and dividends.
- The combination of strong earnings, record performance across banking, insurance and wealth management, rising net charge offs, and ongoing capital returns highlights both earnings power and credit and cost discipline as key watchpoints for Community Financial System.
- Next, the focus will be on how Community Financial System's stronger earnings and record fee businesses may reshape the existing investment narrative.
Scan how Community Financial System's latest earnings, rising net charge offs, and capital returns stack up against other banks with a list of solid balance sheet and fundamentals (25 results).
Community Financial System Investment Narrative Recap
To own Community Financial System, you need to be comfortable with a regional bank leaning on both interest income and a growing mix of fee businesses. The latest quarter showed net interest income of US$143.54 million and net income of US$61.3 million alongside record performance in banking, insurance and wealth. The near term catalyst remains how effectively management turns that broader platform into consistent earnings while redeploying securities into higher yielding loans.
The biggest risk right now sits with rising credit costs and expense creep. Net charge offs climbed to US$5.1 million, driven by two specific commercial relationships, and core noninterest expenses are already guided higher for 2026. If problem credits broaden or new branches and acquisitions do not generate enough revenue, margin pressure could outweigh the benefit of stronger fee and lending activity.
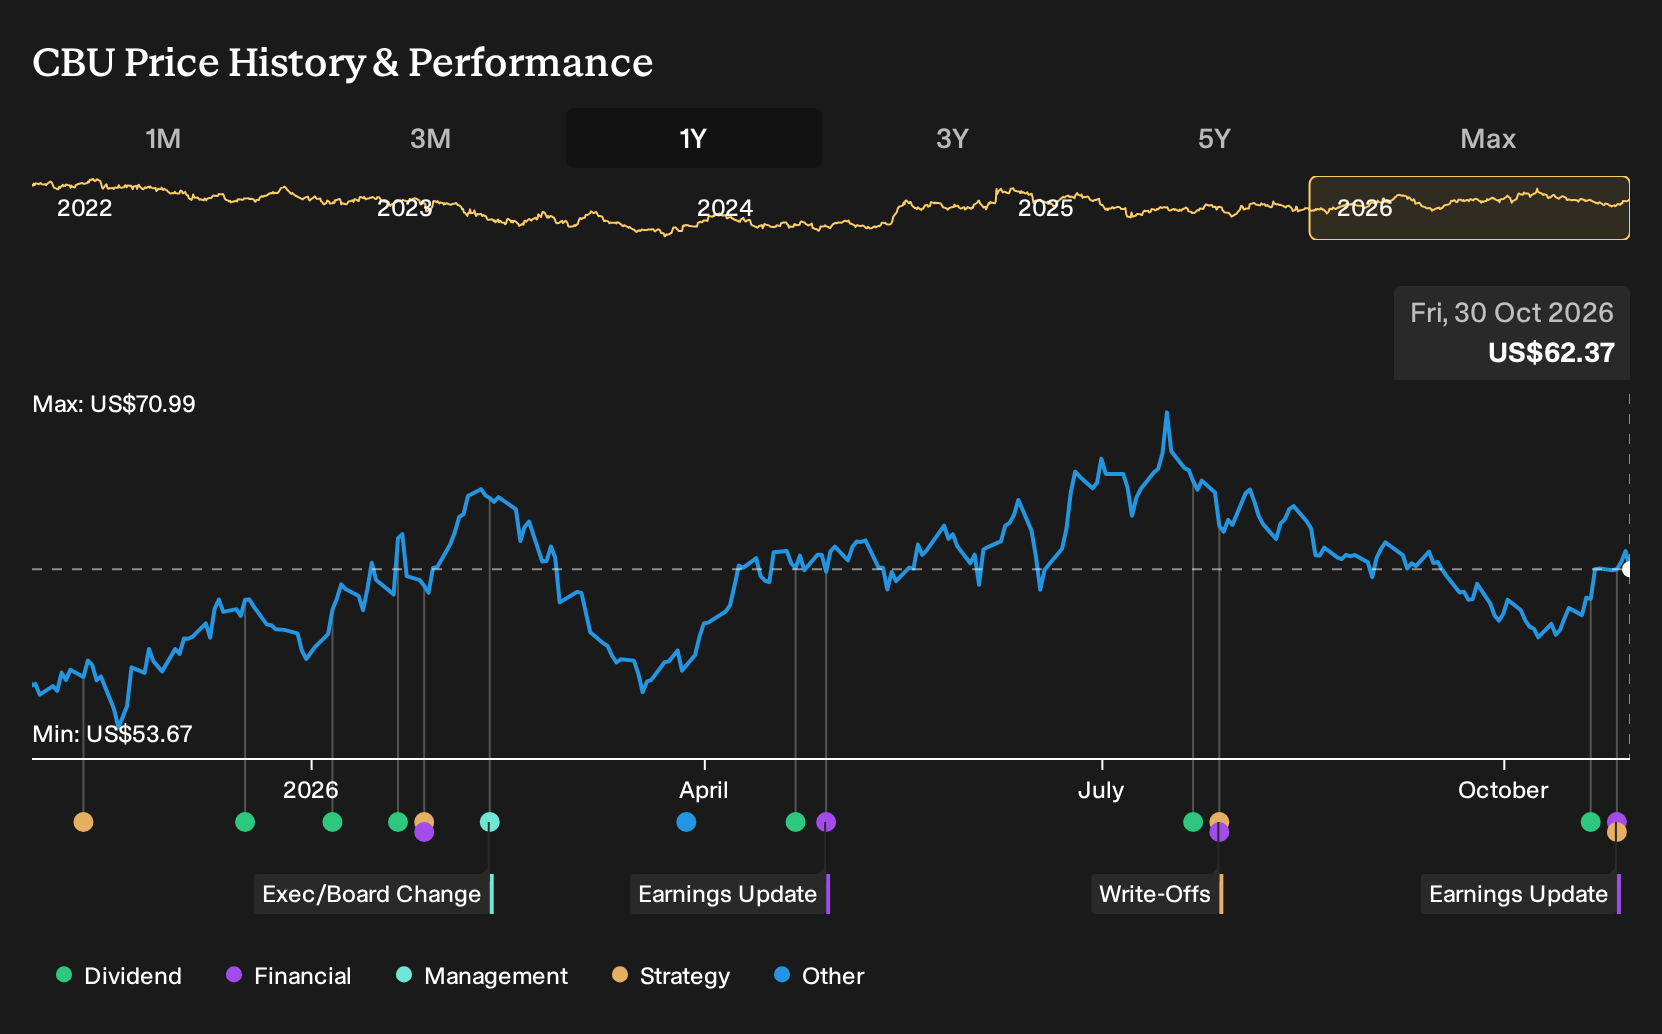
The most relevant recent move for shareholders is the ongoing share repurchase. Between July and September 2026, Community Financial System bought back 250,000 shares for US$16.16 million, completing a 508,471 share program that totaled US$32.11 million. For you as an investor, that matters because it affects per share metrics such as earnings and dividend coverage at the same time as profits are growing.
Buybacks also sit alongside a US$0.49 quarterly dividend declared on October 21, 2026, which keeps capital return in focus while the bank invests in branches, technology and fee acquisitions. The key question is execution. If earnings, fee income and loan growth continue to support these cash returns without stretching the balance sheet or undermining credit quality, the current catalysts around deposit growth and higher yielding loans may remain in place. If that does not occur, capital actions could become harder to sustain at the current pace.
Community Financial System's current earnings are US$229.0 million, with analysts forecasting US$335.6 million of profit and about US$1.1b of revenue by 2029. That outlook assumes revenue expands by 9.8% per year and earnings rise by roughly US$106.6 million over that period.
Uncover why Community Financial System's fair value indicates an 11% potential upside to its current price that could close faster than you expect.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$69 to about US$106 per share, so retail views on Community Financial System stretch from modest optimism to far richer valuations. In light of that spread, rising noninterest expenses and underperforming insurance operations give you reasons to weigh credit, cost and acquisition execution risks carefully.
Explore another Community Financial System fair value estimate, including one that suggests potential upside of up to 70% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Community Financial System research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Community Financial System. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Community Financial System's overall financial health at a glance.
Looking for more investment ideas beyond Community Financial System?
Once you have weighed Community Financial System on its own merits, it can help to compare that view with a broader watchlist of companies that fit different risk and return profiles across the market.
- If you want resilient balance sheets front and center, scan our list of solid balance sheet and fundamentals (25 results) that pair stronger financial footing with more durable fundamentals.
- For investors hunting for value opportunities, sort through 29 high quality undervalued stocks identified by fundamentals rather than headlines.
- Income focused readers can narrow in on payout strength and consistency by reviewing 5 dividend fortresses that emphasize higher yields supported by underlying cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com