
Revenue Growth And Wider Loss Could Be A Game Changer For Scatec (OB:SCATC)
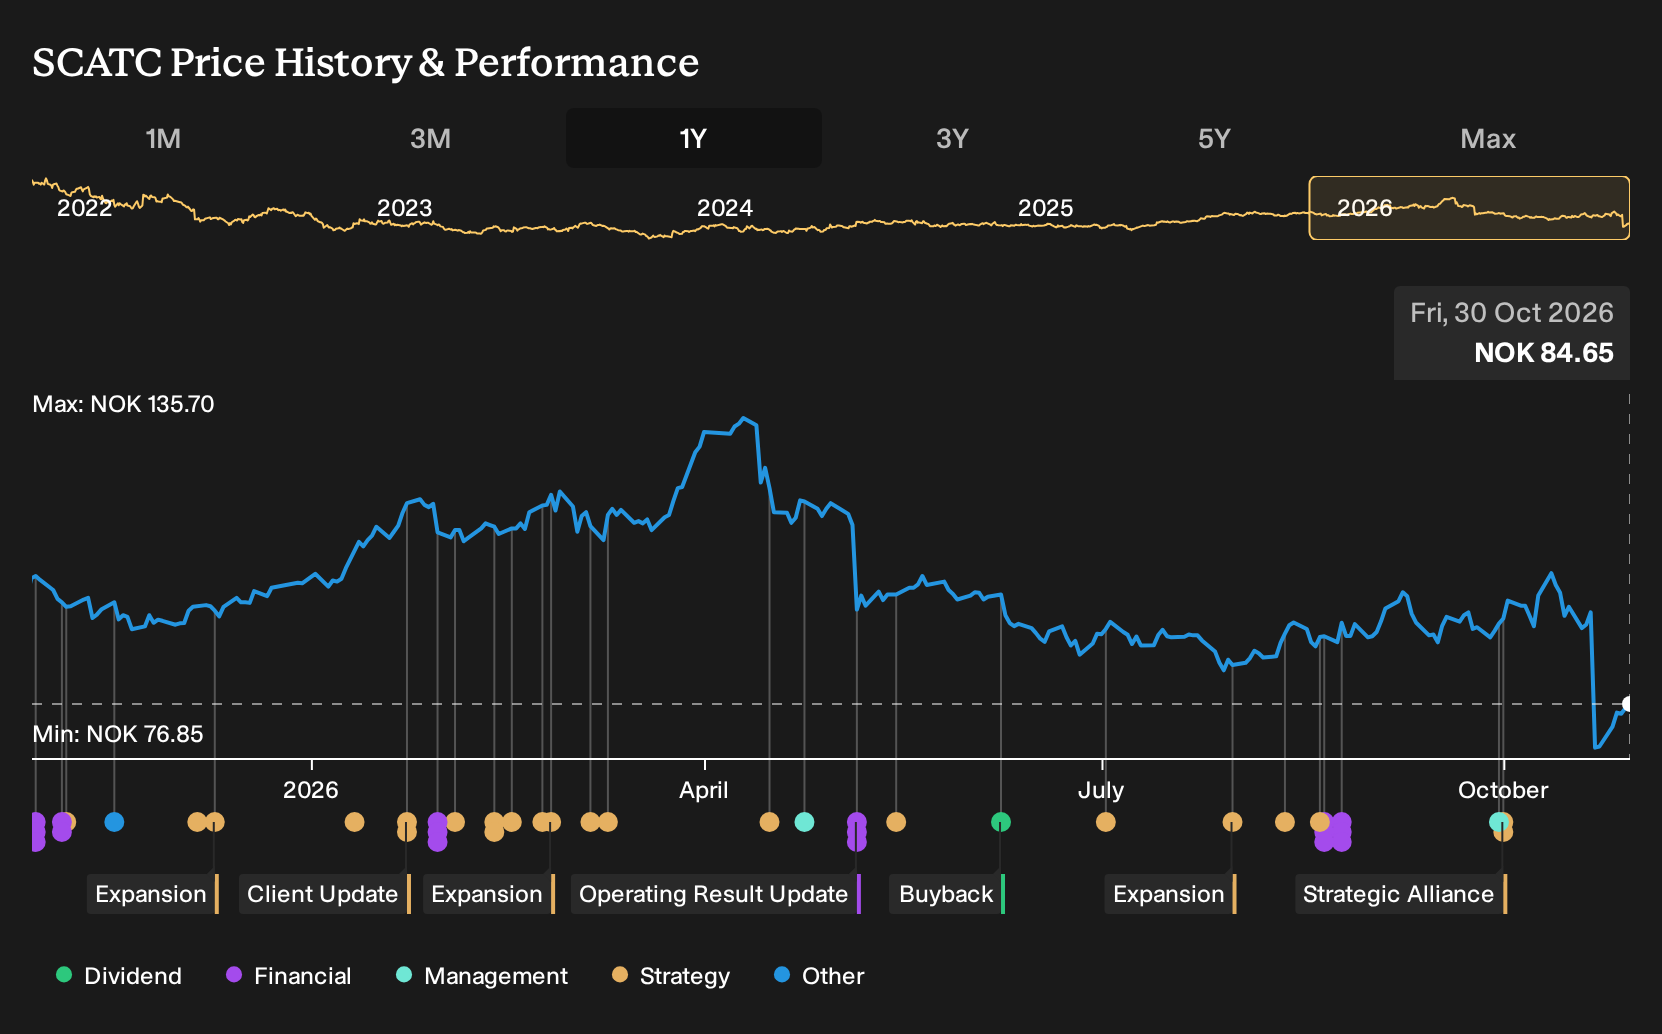
- Scatec reported third quarter 2026 results with sales of NOK 1,406 million, revenue of NOK 1,677 million and a net loss of NOK 1,003 million, alongside a basic loss per share from continuing operations of NOK 6.27.
- Across the first nine months of 2026, Scatec showed higher sales than the prior year but moved from net income to a NOK 1,229 million loss, indicating pressure on profitability despite a still active renewables portfolio.
- We will now look at how Scatec's investment narrative is challenged by rising net losses despite higher reported quarterly revenue.
Scatec Investment Narrative Recap
To own Scatec, an investor needs to believe that the large renewables and storage portfolio can eventually translate into steadier earnings despite volatility along the way. The latest quarter complicates that story. Revenue was NOK 1,677 million, yet the firm reported a net loss of NOK 1,003 million, which keeps attention squarely on cash generation and cost discipline.
In the near term, the key catalyst is execution on moving projects from pipeline to operation while managing debt and interest costs that are not well covered by current earnings. The biggest risk right now sits in that funding structure and in operational shocks such as weather, currency and geopolitical events that have already affected guidance.
The latest earnings announcement for the third quarter and first nine months of 2026 is the main reference point investors will work from. Scatec reported quarterly sales of NOK 1,406 million and a net loss of NOK 1,003 million, and for the nine-month period sales of NOK 3,571 million with a net loss of NOK 1,229 million versus net income a year earlier.
Those figures tie directly into existing catalysts. A sizeable 12.3 GW generation and 6.8 GWh storage portfolio only creates value if projects reach operation on time and at acceptable returns while interest costs remain manageable. With earnings currently under pressure and guidance previously cut on currency, weather and asset damage, the burden of proof now sits on consistent project delivery and tighter financial control.
What The Analyst Scenario Implies For Scatec
Scatec's narrative projects NOK 13.0b revenue and NOK 3.0b earnings by 2029. This is based on analysts assuming 49.5% yearly revenue growth and an earnings swing of about NOK 3.3b from earnings today of a NOK 282.0m loss to the 2029 consensus earnings level.
Uncover why Scatec's fair value indicates a 54% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Scatec attracts a wide spread of fair value views from the Simply Wall St Community, with three retail estimates stretching from NOK 12.68 to NOK 130.38. That gap reflects how differently you might weigh the sizeable project pipeline against recent net losses and guidance cuts. Use those contrasting opinions to test your own thesis.
Explore 2 other Scatec fair value estimates, including one that suggests as much as 85% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your Scatec research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Scatec. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Scatec's overall financial health at a glance.
Looking For More Ideas Beyond Scatec?
If Scatec has sharpened your view on risk, income and balance sheet strength, it can help to line it up against other companies with clear, data driven filters. The Simply Wall St Screener lets you move from a single story to a broader watchlist in a few clicks.
- If resilience is top of mind, check out a 216 resilient stocks with low risk scores that may hold up better when conditions turn rough.
- If you care most about robust finances, compare Scatec with a list of solid balance sheet and fundamentals (199 results) to see which businesses carry less balance sheet strain.
- If you want potential mispricings on your radar, line up Scatec against a 603 high quality undiscovered gems and see which stories the market might be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com