
Did Banco do Brasil's Fall Catch You Out? What Investors Missed
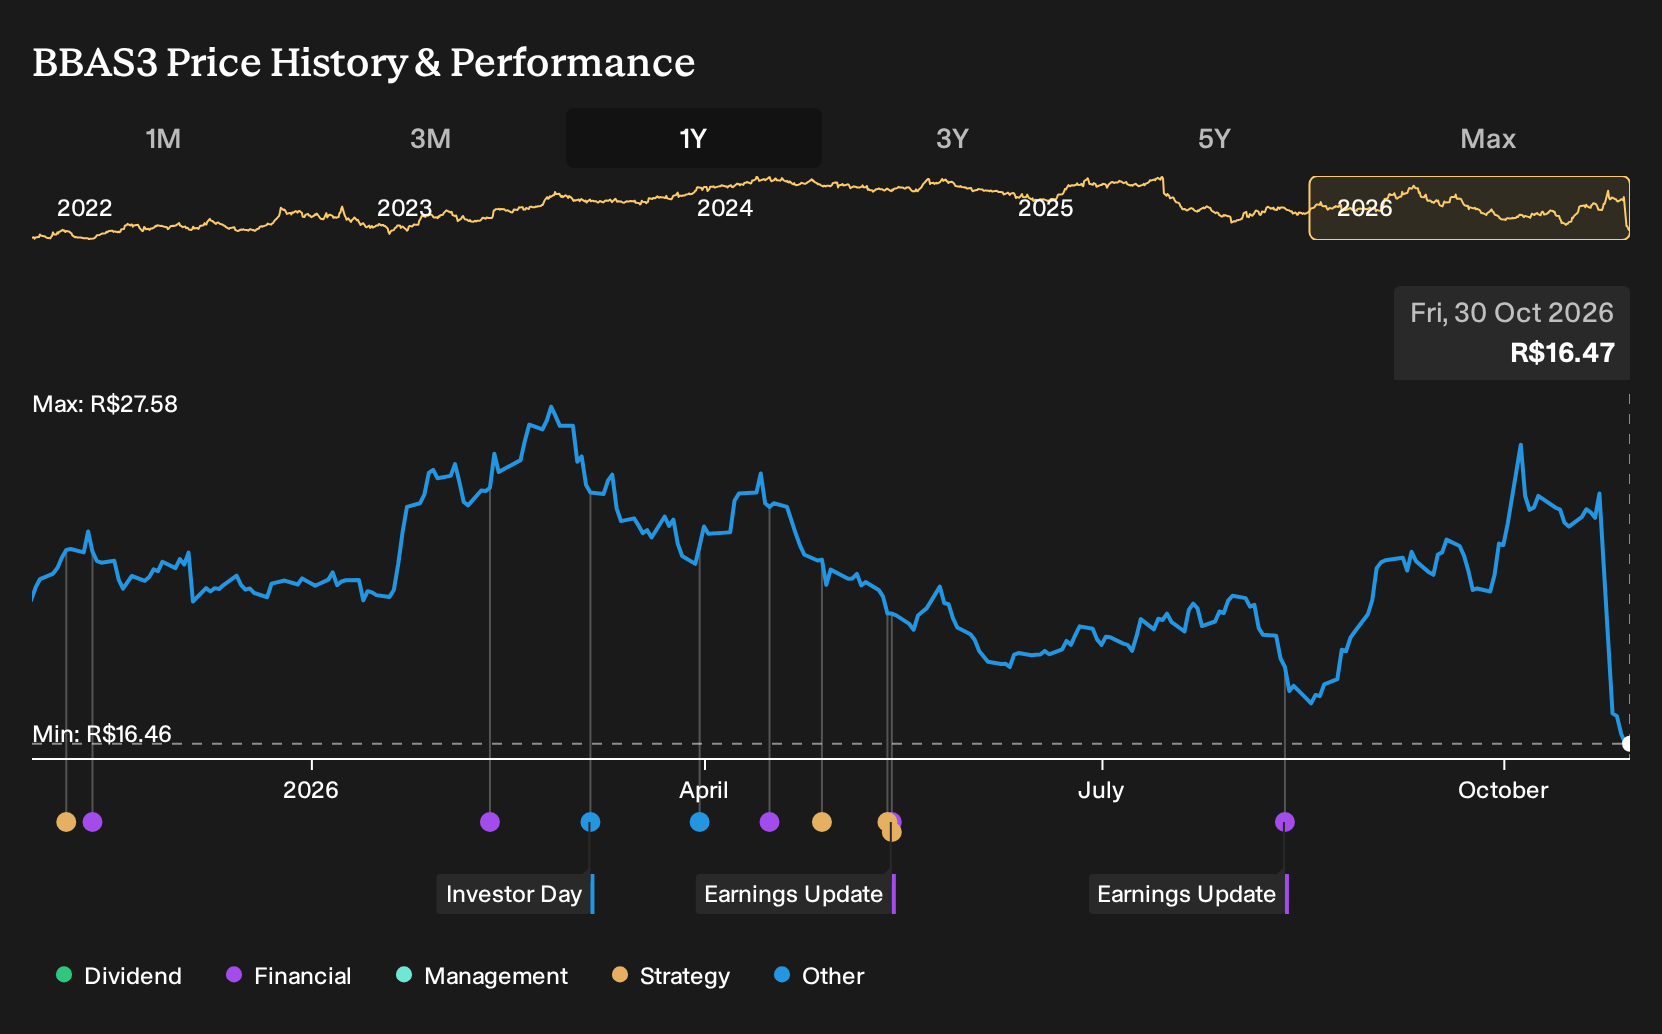
Banco do Brasil looked like a textbook case of digital acceleration and financial inclusion meeting a rising middle class, yet holding through the past year hurt. For Banco do Brasil shareholders, the loss over the past year was 22.5%, including dividends. Revenue for Q2 2026 was similar to Q2 2025, while net income and margin slipped. If you had bought on 30 October 2025, what early clues were on record that this weaker profitability could bite your return?
If the move has made Banco do Brasil harder to judge, start where the gap is still open and scan 195 high quality undervalued stocks.
The Two Banco do Brasil Stories Investors Had To Weigh
The shares cost R$21.63 at the start of the period, and you were really choosing between two very different stories about where Banco do Brasil might go next.
The bullish narrative pointed to a Fair Value of R$39, a notional upside figure based on strong digital execution and Brazil's middle class expanding. Supporters leaned on private payroll lending and agribusiness strengths, plus access to 20 million pre-approved margins through eSocial, as fuel for higher quality, lower risk credit.
The bearish view argued for a Fair Value of R$20, an implied downside anchored in slower digital progress and intense fintech competition. That camp worried about political influence over lending, heavy agribusiness and MSME exposure, and tighter rules like Resolution 4966 raising provisions and squeezing profitability.
What The Banco do Brasil Results Put To The Test
The clearest new fact was the Q2 2026 result. Banco do Brasil reported revenue of R$21,915.374m against R$21,873.133m a year earlier, while net income slipped from R$2,782.083m to R$2,397.643m and net margin moved from 12.7% to 10.9%. That combination cut both ways for the bullish and bearish profitability stories.
The lesson is straightforward. When a thesis leans on higher quality earnings, track whether net margin is holding up against roughly flat revenue, rather than focusing only on whether the top line looks steady.
What You Are Being Asked To Believe In Banco do Brasil Today
Banco do Brasil now trades at R$16.47. The selected Narrative sees Fair Value above this level and ties that gap to how well the group can use digital tools and its wider conglomerate to support earnings while credit costs remain elevated.
Your decision at this price rests on one main belief. A buyer would need to think agribusiness and retail credit clean up can be executed well enough that cost of risk eventually settles within management’s intended range.
"The ongoing digital acceleration at Banco do Brasil, including the rapid build out of over 2,300 analytical AI models and widespread use of employee built AI agents that have freed up around 1.5 million working hours and lifted loan renegotiation conversion multiples, continues to support the view that cost efficiency and credit recovery productivity can feed into net margins and earnings."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
How Could You Get There Earlier?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 30% below our estimate - sells the cloud and AI backbone enterprises plug into existing workflows and codebases.
- Company 2 - 45% below our estimate - expands a design led lifestyle label through heavier Asia focused retail and digital investment.
- Company 3 - 47% below our estimate - converts modular building methods and digital project tools into margin focused construction contracts.
Three companies from the same screener. Open every one of the 199 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com