
Tokuyama (TSE:4043) Q2 Earnings Contrast Revenue Growth With Profit Squeeze
Tokuyama entered this Q2 2027 earnings day with a stock that has drifted sideways in the very short term and only modestly higher over three months, yet still trades far below one popular discounted cash flow estimate of fair value. That gap set up big expectations.
The actual print delivered a different kind of story. Revenue reached ¥93,022 million while basic earnings per share came in at ¥66.91, and the share price closed at ¥3,932 on October 30. The immediate reaction was muted, but the real tension sits in the squeeze on profitability that runs through these latest numbers.
Like the value on Tokuyama but uneasy about the pressure on profitability in this latest report? Benchmark it against a list of solid balance sheet and fundamentals stocks (21 results) to see how other financially robust businesses stack up on earnings quality.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥93,022 million vs. ¥81,928 million (higher year on year)
- Net Income (Excl. Extra Items, Q2 2027 vs Q2 2026): ¥4,777 million vs. ¥7,234 million (declined year on year)
- Basic EPS (Q2 2027 vs Q2 2026): ¥66.91 vs. ¥100.55 (fell year on year)
- Trailing 12M Net Income (Excl. Extra Items, Q2 2027 vs Q2 2026): ¥20,041 million vs. ¥23,892 million (lower over the past year)
Earnings growth forecasts look much faster than revenue and margins. Ask Charlie what makes Tokuyama look undervalued here.
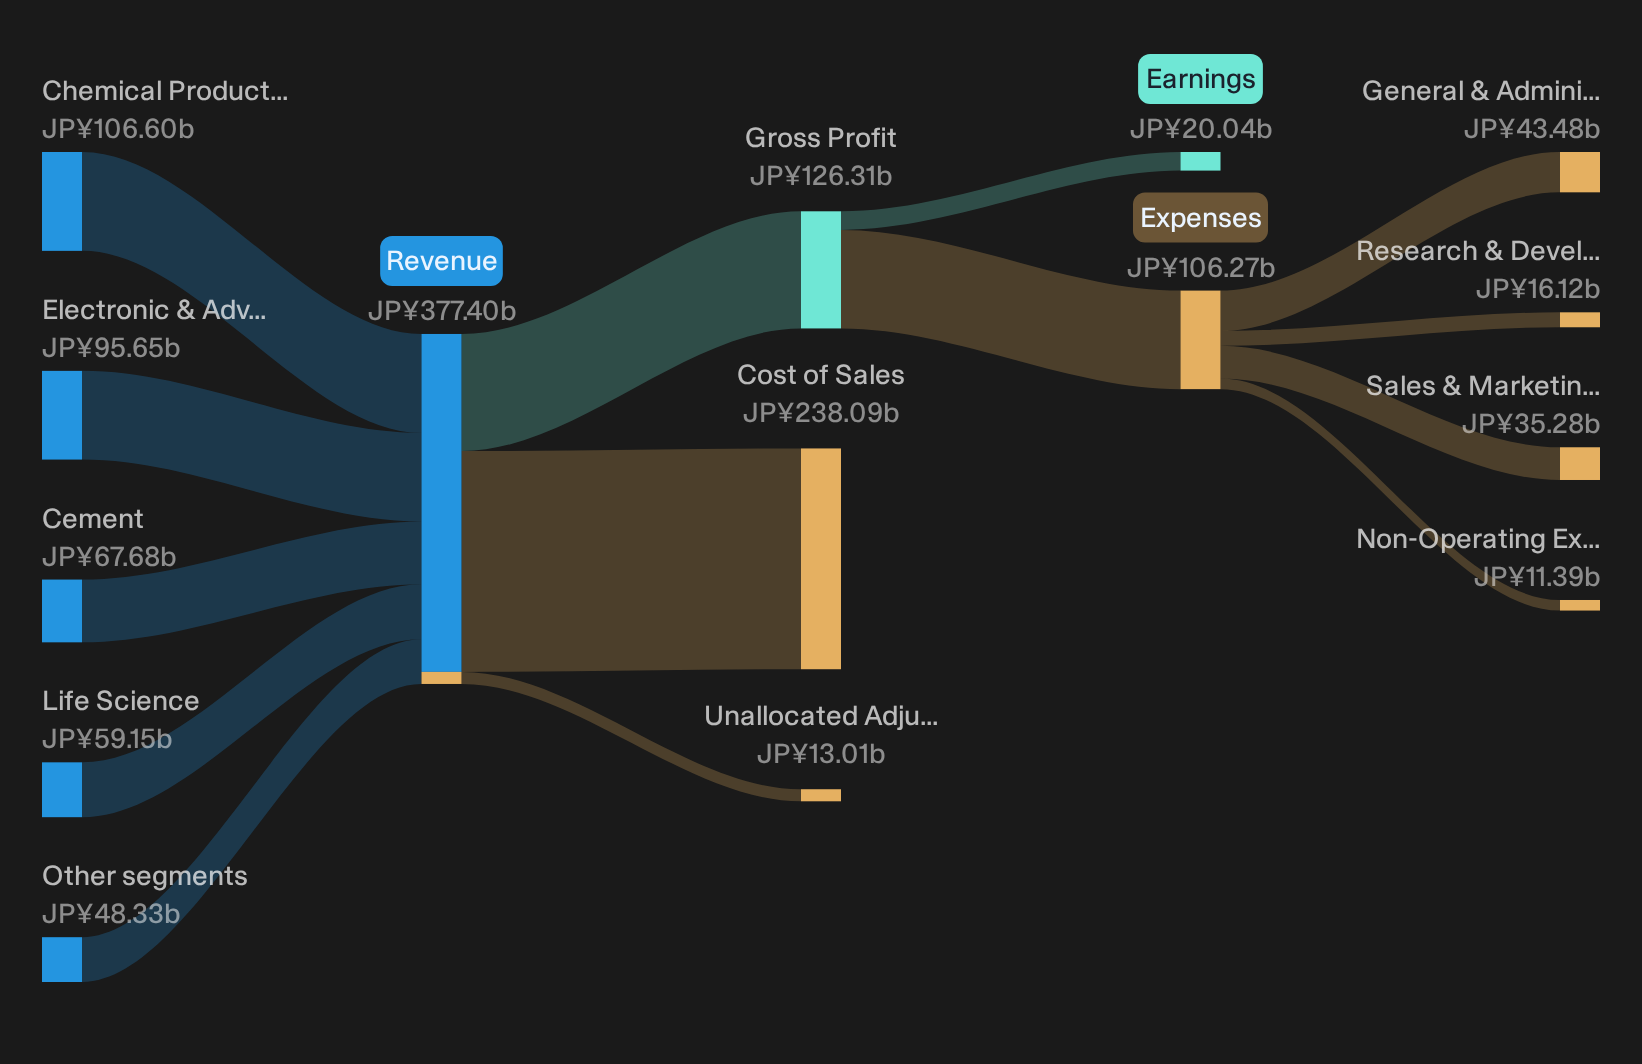
Tokuyama bullish story meets mixed earnings reality
Tokuyama’s diversified profile still has some support from the top line. Revenue reached ¥93,022 million, higher than the prior year, which fits a view that the broader portfolio can keep sales ticking over even when parts of the cycle feel soft. For investors focused on the electronics and higher value materials pitch, steady overall turnover provides raw fuel for any future mix shift. The share price holding roughly flat over 7 and 90 days also hints that the market is not abandoning that constructive angle on the business model.
Profit squeeze keeps the cautious Tokuyama view alive
Where the bullish story runs into trouble is profit. Net income excluding extra items declined to ¥4,777 million and basic EPS fell to ¥66.91. Trailing 12 month earnings also moved lower to ¥20,041 million. That pattern supports concerns that cyclical chemicals and cement can drag on group profitability even when revenue rises. The slight drop over 30 days in the share price suggests investors are already weighing this margin pressure. For anyone worried about the more traditional industrial exposure, these results do not yet soften that cautious narrative.
With earnings still under pressure and margins thinner than last year, the real question is whether Tokuyama has the balance sheet strength to ride this out. Check the full financial health analysis of Tokuyama stock before you assume the cash and debt picture is comfortable.Find Hidden Value Opportunities
Tokuyama just showed how revenue support can coexist with pressure on margins and a flat share price. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 32% below our estimate - runs a payment infrastructure that lets merchants plug into multiple cashless options through a single platform.
- Company 2 - 33% below our estimate - supplies the precision photomasks chipmakers rely on as designs shrink and tolerances tighten in production.
- Company 3 - 34% below our estimate - feeds device makers with specialty optical and electronic materials that fit into high-spec screens, sensors and communication hardware.
That is three of the list. See the full list of 15 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com