
Block (XYZ) Could Be 23% Undervalued Ahead Of Its Third Quarter Report
Block (XYZ) heads into its upcoming third quarter report with expectations for higher earnings and revenue, after analysts raised profit forecasts over the past month and interest in the stock picked up.
The share price has climbed 16.99% year to date to US$76.22, even though the 90 day share price return is down 6.18%. This suggests that enthusiasm around Block’s upcoming earnings has built over the year, while more recent trading has cooled.
Scan for other payment and fintech stocks where sentiment and earnings expectations are also heating up by running the curated 29 high quality undervalued stocks alongside Block on your watchlist.
After a choppy few months, Block is still up strongly for the year and trading below analyst price targets. Is this a reasonable entry now, or would it make more sense to wait for a deeper pullback once the valuation becomes more compelling?
Most Popular Narrative: 23% Undervalued
Block’s most followed valuation narrative places fair value at about $98, compared with the latest close of $76.22. That gap reflects a view that the market is underpricing how its ecosystems and financial infrastructure could translate into future cash flows when discounted at 7.54%.
The rapid acceleration in new product launches, now supported by an AI native operating model that has lifted code changes per engineer 150% since early 2026 and helped ship 130 Square features in the first half of 2026, points to sustained improvements in Cash App and Square feature velocity that can support higher revenue and operating leverage over time.
See why 192 investors see Block as 23% undervalued.
Result: Fair Value of $98.36 (UNDERVALUED)
Still, the Block narrative can unravel if Cash App user growth stays sluggish, or if fresh regulatory or fraud issues push compliance costs and lending risk higher.
Find out about the key risks to this Block narrative.
Another View: Block Looks Expensive On Earnings
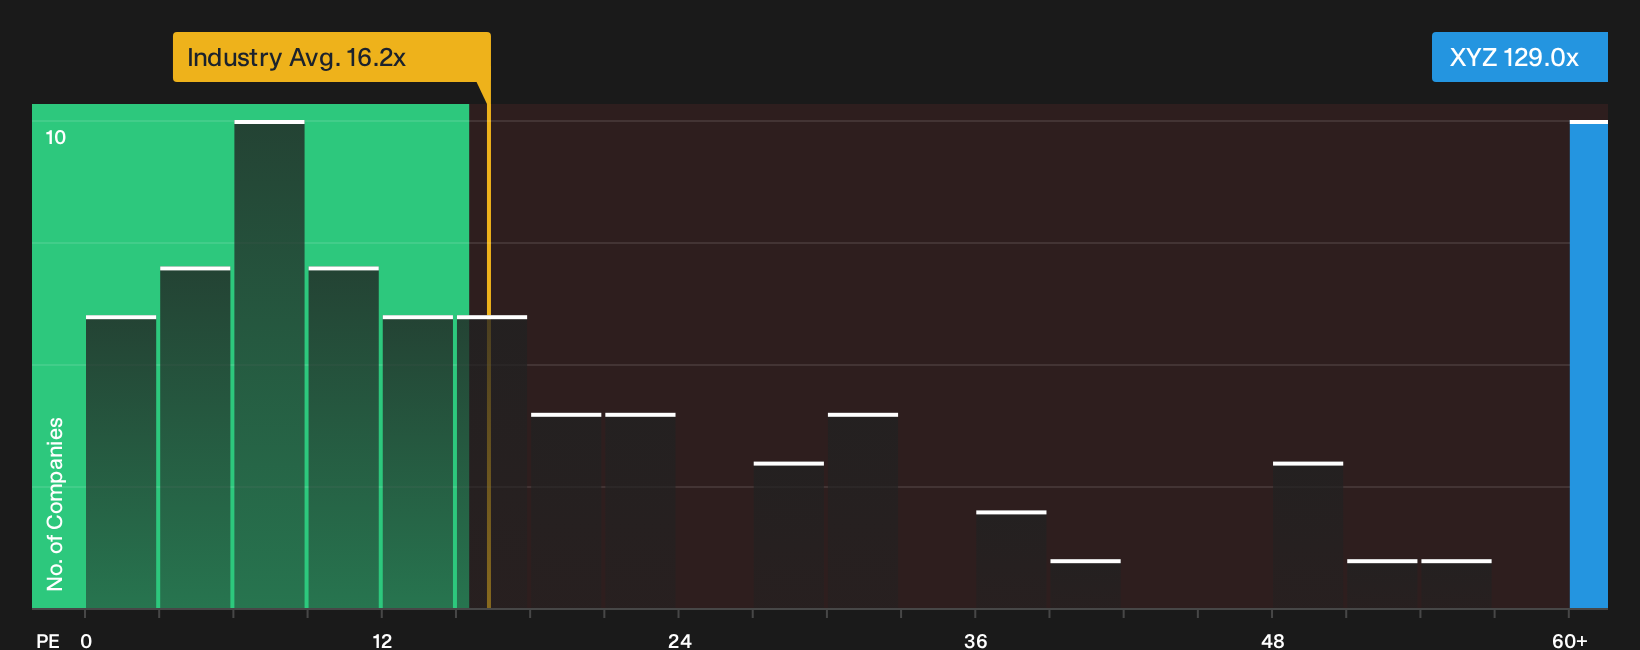
The story changes when you look at Block through a simple P/E lens. The stock trades at about 129x earnings, compared with roughly 16x for the US Diversified Financial industry and about 12x for peers, while the fair ratio sits closer to 30x. That gap points to real valuation risk if expectations reset.
If you prefer to lean on simple earnings multiples instead of detailed models, it is worth considering how the gap between today’s P/E, the peer group, and the fair ratio could close over time, and what that might imply for your downside and upside skew. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinions are mixed about whether Block’s setup feels attractive or stretched right now. Move quickly to inspect the full picture for yourself, including 3 key rewards and 3 important warning signs
Looking for more Block investment ideas?
If you only stop at Block, you risk missing other stocks with cleaner balance sheets, stronger income streams, and fresh upside stories flagged by the Simply Wall St screener.
- Target resilient balance sheets by reviewing the list of solid balance sheet and fundamentals (25 results) that could help steady your portfolio when sentiment cools.
- Hunt for mispriced opportunities using the 18 high quality undiscovered gems that pair solid fundamentals with low market attention.
- Reinforce your income stream by focusing on the 5 dividend fortresses that aim to combine higher yields with staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com