
UroGen Pharma (URGN) Following Durable JELMYTO Data Is Its Bladder Cancer Story Fully Valued
UroGen Pharma (URGN) is back in focus after publishing final five-year Olympus follow-up data on JELMYTO, highlighting durable responses in low-grade upper tract urothelial cancer that may influence how investors assess its urology-focused pipeline.
Recent trading tells a mixed story for UroGen Pharma. The share price has pulled back over the past month, with a 30-day share price return of down 19.57% adding to a 90-day decline of 14.54%. Yet year-to-date share price return is up 43.9%, and the 3-year total shareholder return of 182.45% points to strong longer term enthusiasm as investors weigh the JELMYTO data, the UGN-103 NDA progress, and upcoming earnings expectations.
Scan biopharma ideas shaped by similar clinical catalysts by checking out the hand-picked 18 high quality undiscovered gems that could be flying under most investors' radar.
UroGen Pharma now has durable JELMYTO data, an accepted UGN-103 filing, and a share price that has surged over 40% this year. The puzzle is whether that clinical story is already fully embedded in today’s US$32.68 quote.
Most Popular Narrative: 46% Undervalued
Against UroGen Pharma's last close of $32.68, the most followed valuation story anchors on a fair value of about $60 and ties that gap directly to expectations for Zusduri and the broader bladder cancer franchise.
The shift toward minimally invasive, office-based therapies (away from repeated surgeries) and long-term durability data for ZUSDURI align with industry-wide transitions in care standards, supporting broader market penetration and the company's ability to command premium pricing, thereby improving future net margins and profitability. Expansion of the pipeline, including UGN-103 and other next-generation formulations, reduces reliance on a single product and supports more durable earnings power if execution matches expectations.
See why 15 investors see UroGen Pharma as 46% undervalued.
Result: Fair Value of $60 (UNDERVALUED)
Still, the story can break if UroGen Pharma's heavy operating losses persist or if Zusduri adoption and reimbursement progress fall short of analyst assumptions.
Find out about the key risks to this UroGen Pharma narrative.
Another View: What Multiples Say About UroGen Pharma
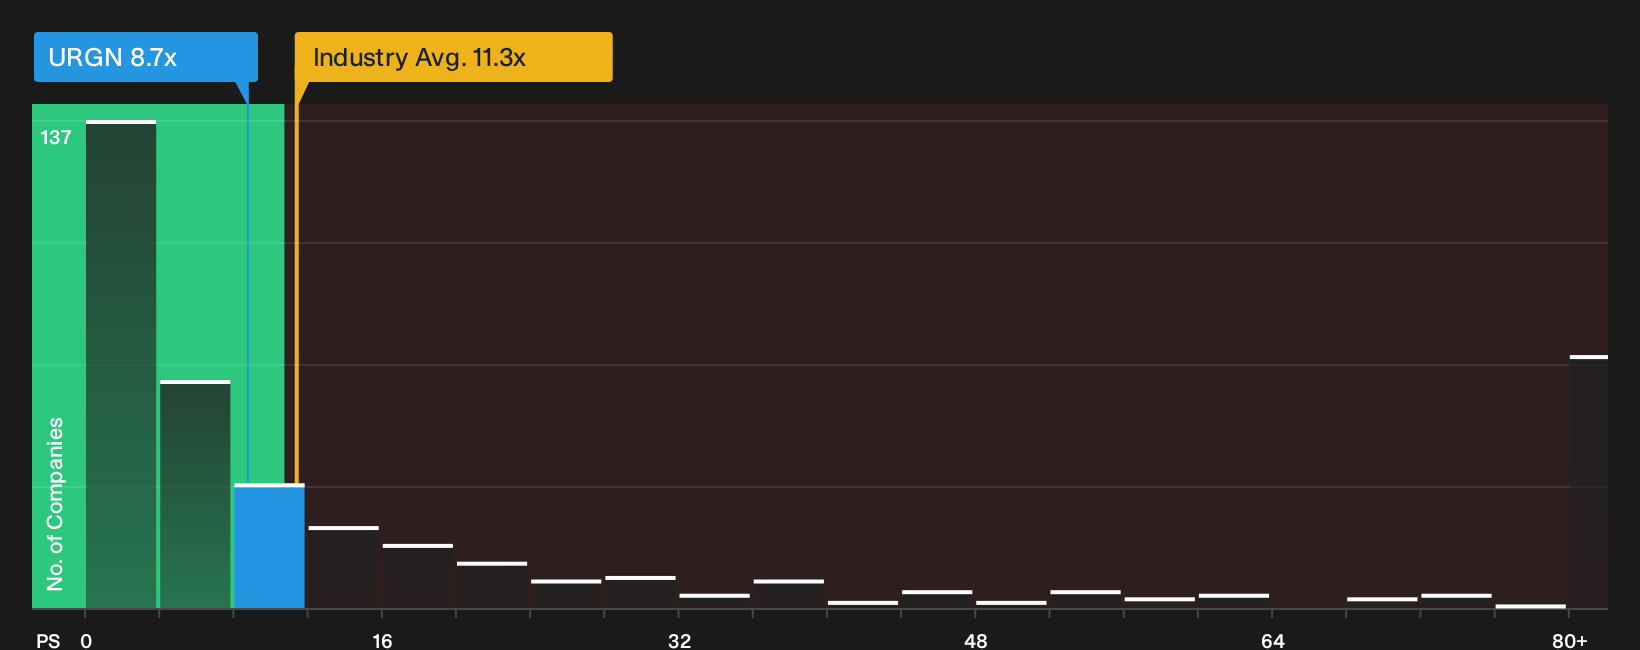
Fair value stories built on analyst targets meet a different picture when you look at the simple P/S ratio. UroGen Pharma trades around 8.5x sales, which is expensive versus closer peers on 3.5x but cheaper than the wider US Biotechs group on 11.6x. That spread hints at both upside potential and valuation risk if sentiment towards bladder cancer specialists cools.
For a closer read on what this pricing gap might mean in practice, including how it lines up against a fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this UroGen Pharma story points in different directions, so move quickly, review both the risks and the upside, then weigh the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond UroGen Pharma?
If you stop with UroGen Pharma, you miss a wider field of opportunities. Put a few minutes into scanning fresh setups and you give yourself more options.
- Target potential mispricing by running through a focused pool of quality companies using the 29 high quality undervalued stocks.
- Prioritize resilience and positions that may help you sleep better at night by filtering for sturdier balance sheets with the list of solid balance sheet and fundamentals (25 results).
- Hunt for income-focused opportunities that still keep quality in view by reviewing the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com