
Thomson Reuters (TSX:TRI) Is Drawing Fresh Attention, What Is Behind It?
Thomson Reuters (TSX:TRI) just paired a higher 2026 revenue growth outlook with strong free cash flow, a completed $600 million buyback, and an agreement to sell control of its Global Print unit.
The CoCounsel Tax, Audit & Accounting launch and the higher 2026 revenue outlook arrive after a sharp 30 day share price return of 19.41% and a 90 day gain of 20.24%, even as the 1 year total shareholder return has declined 21.03%. This suggests momentum in Thomson Reuters is improving in the short term, while long term holders are still under water.
Spot similar AI powered compounders and balance sheet backed growers by scanning our hand picked 39 profitable AI stocks that aren't just burning cash. These echo the Thomson Reuters playbook of cash funded product investment.Thomson Reuters looks like a high quality information and software franchise, supported by cash funded AI investment and buybacks. After a sharp move in the share price, is that strength already fully reflected in what you pay today?
Most Popular Narrative: 17% Undervalued
On the latest numbers, the most followed narrative sees Thomson Reuters fair value at CA$199.37 against a last close of CA$165.36, which puts the spotlight firmly on its AI driven contract mix and recurring software base.
The main factor that would need to go right is sustained execution on AI product adoption across the Big 3 segments, along with addressing go to market issues in tax and audit, so that current growth and margin goals remain on track.
Resolution of go to market confusion in tax products such as SurePrep and the Ready to Review or Ready to Advise suite, where leadership and talent changes are already in motion, leaves room for Thomson Reuters to translate existing AI capabilities in Tax, Audit and Accounting into higher transactional activity and potentially better segment margins.
See why 2 investors see Thomson Reuters as 17% undervalued.
Result: Fair Value of CA$199.37 (UNDERVALUED)
Still, the bullish Thomson Reuters script can break if AI rivals narrow its content edge, or if Tax, Audit & Accounting execution issues drag on longer.
Find out about the key risks to this Thomson Reuters narrative.
Another View: What P/E Says About Thomson Reuters
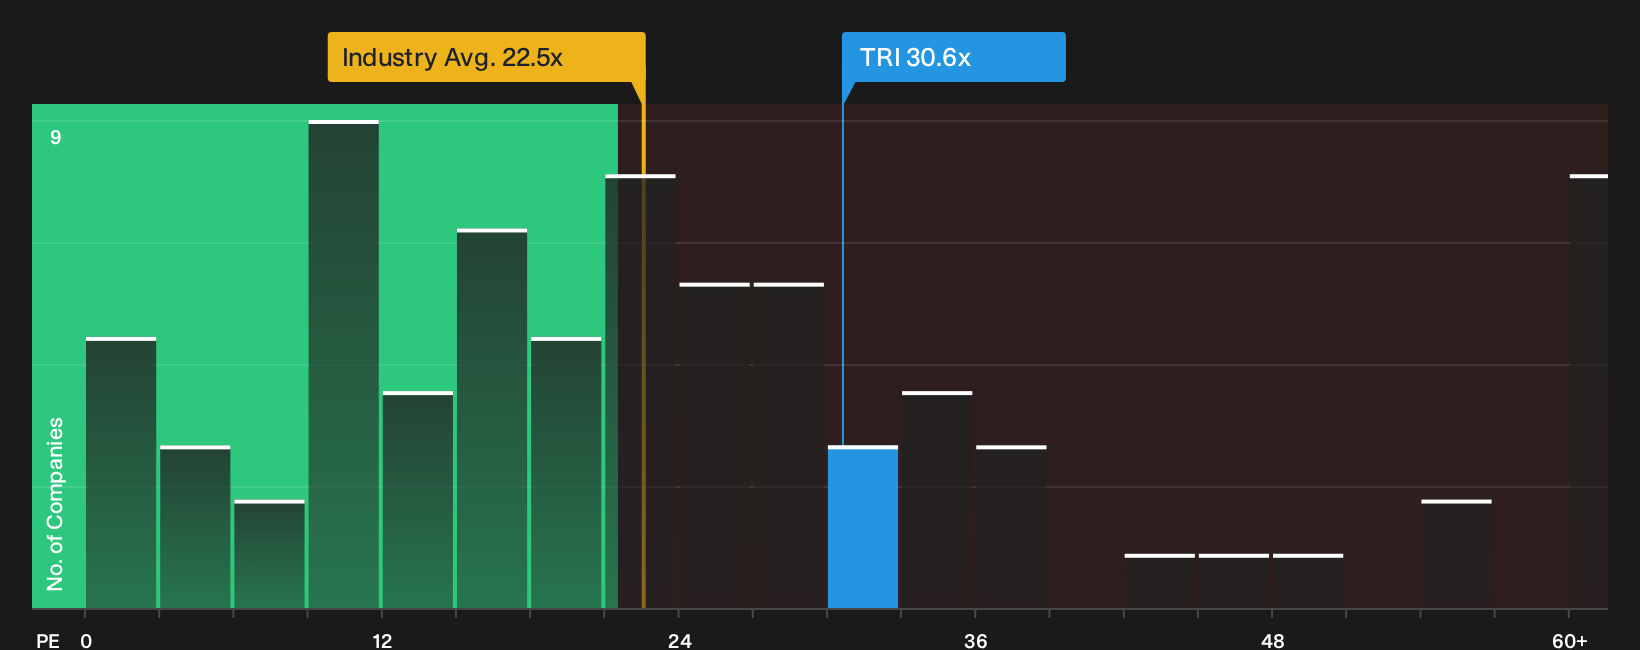
The bullish narrative leans on fair value estimates, yet Thomson Reuters currently trades on a P/E of 30.6x while the North American Professional Services group sits at 22.5x and the fair ratio is 29.4x. That premium points to less room for error if growth or margins disappoint.
For a closer look at how that current price stacks up against what the numbers imply, review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Thomson Reuters often spark debate, so use that tension as a prompt to move quickly and review the underlying data yourself. To weigh both the upside potential and the concerns already flagged by other investors, start with the 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Thomson Reuters?
If you stop with just Thomson Reuters, you miss a wider set of cash generative, resilient, and overlooked opportunities that could better match your portfolio goals.
- Target potential bargains by scanning a curated 3 high quality undervalued stocks that filters for quality businesses trading below what their fundamentals may justify.
- Strengthen your income stream with a hand picked 3 dividend fortresses focused on companies pairing higher yields with sturdier balance sheets.
- Reduce portfolio stress by reviewing a 7 resilient stocks with low risk scores built around resilient operators with lower risk scores and solid financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com